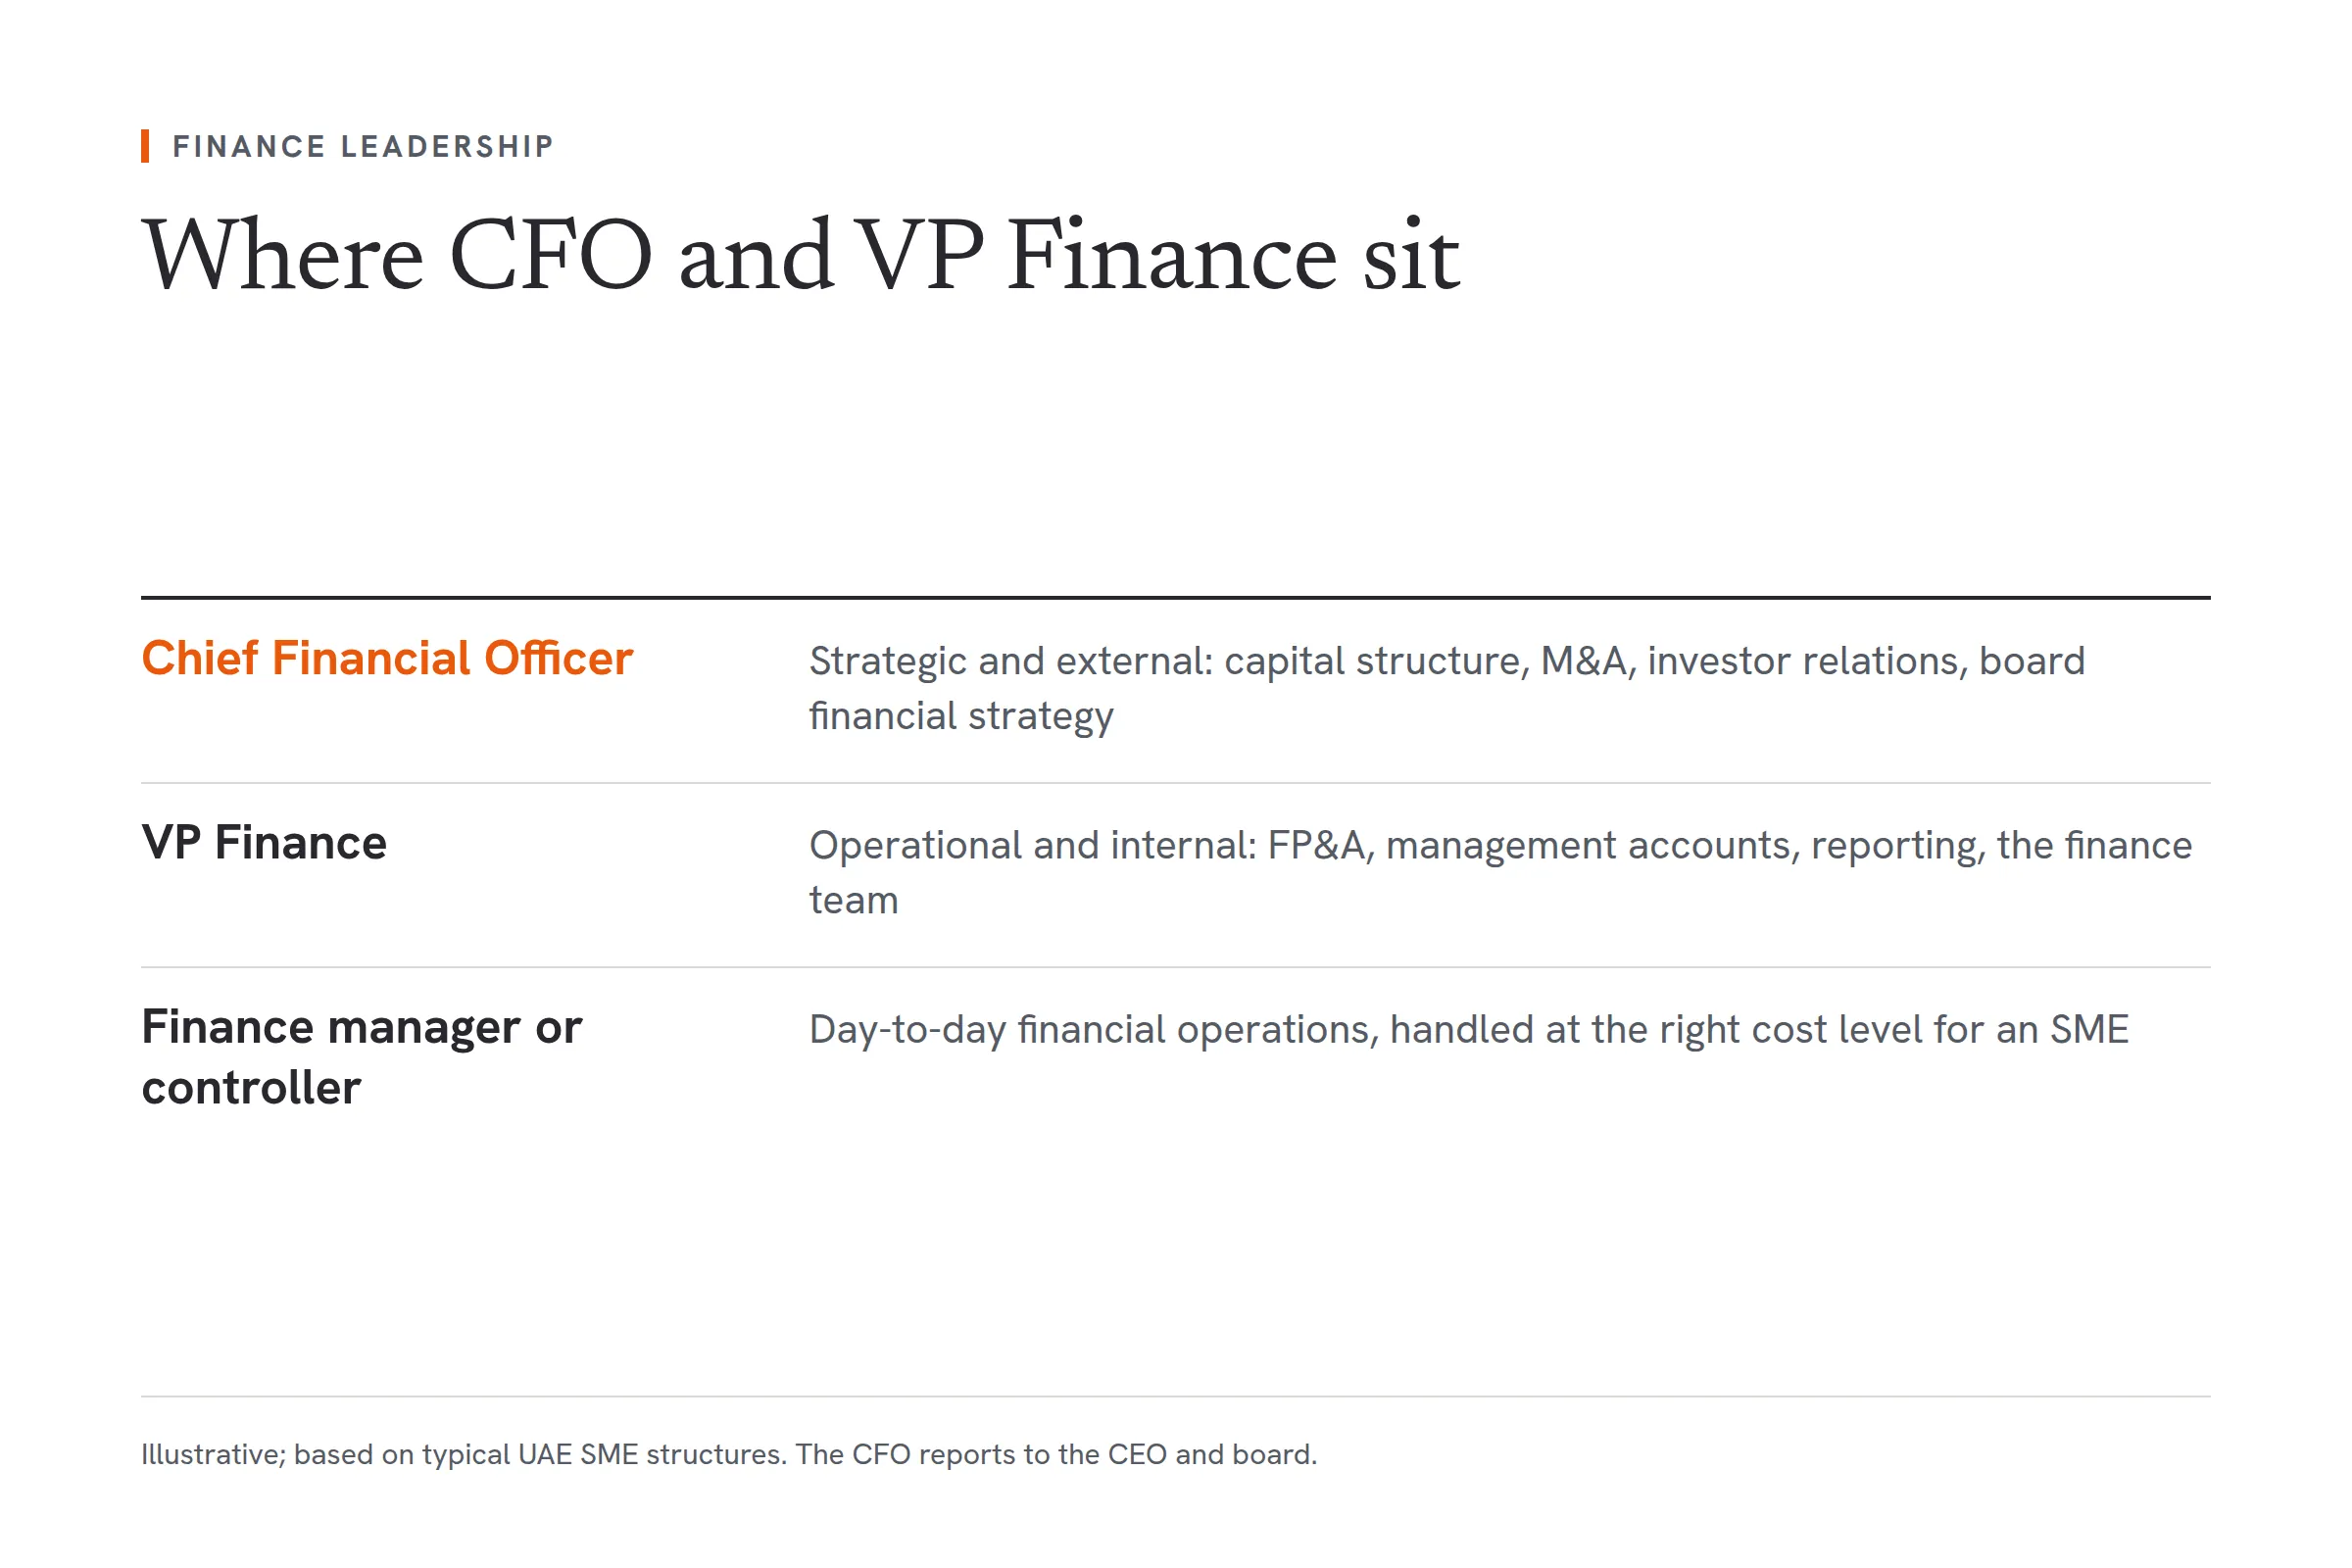
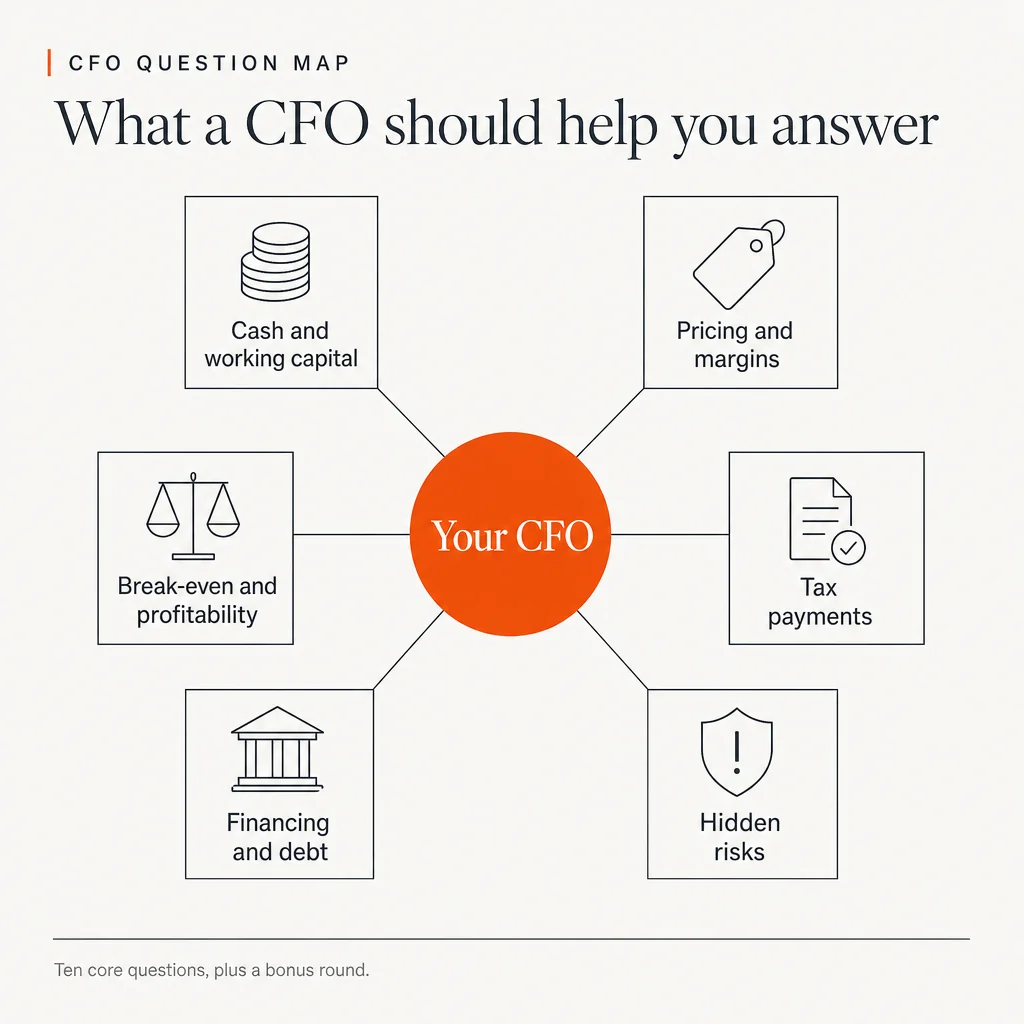
A CFO should be able to answer ten questions about your cash, margins, tax and financing without reaching for a spreadsheet. Running a business often feels like juggling flaming swords: growing, managing teams, satisfying customers and somehow not running out of money. That is where a Fractional CFO comes in. When the financial picture gets murky, these are the questions a Chief Financial Officer (CFO) should help you answer, the same themes we cover in our CFO vs VP Finance guide when founders are unsure which senior finance role they actually need.
The examples below are illustrations of how each question plays out, not client case studies.
1. “What will our cash position look like in three months?”
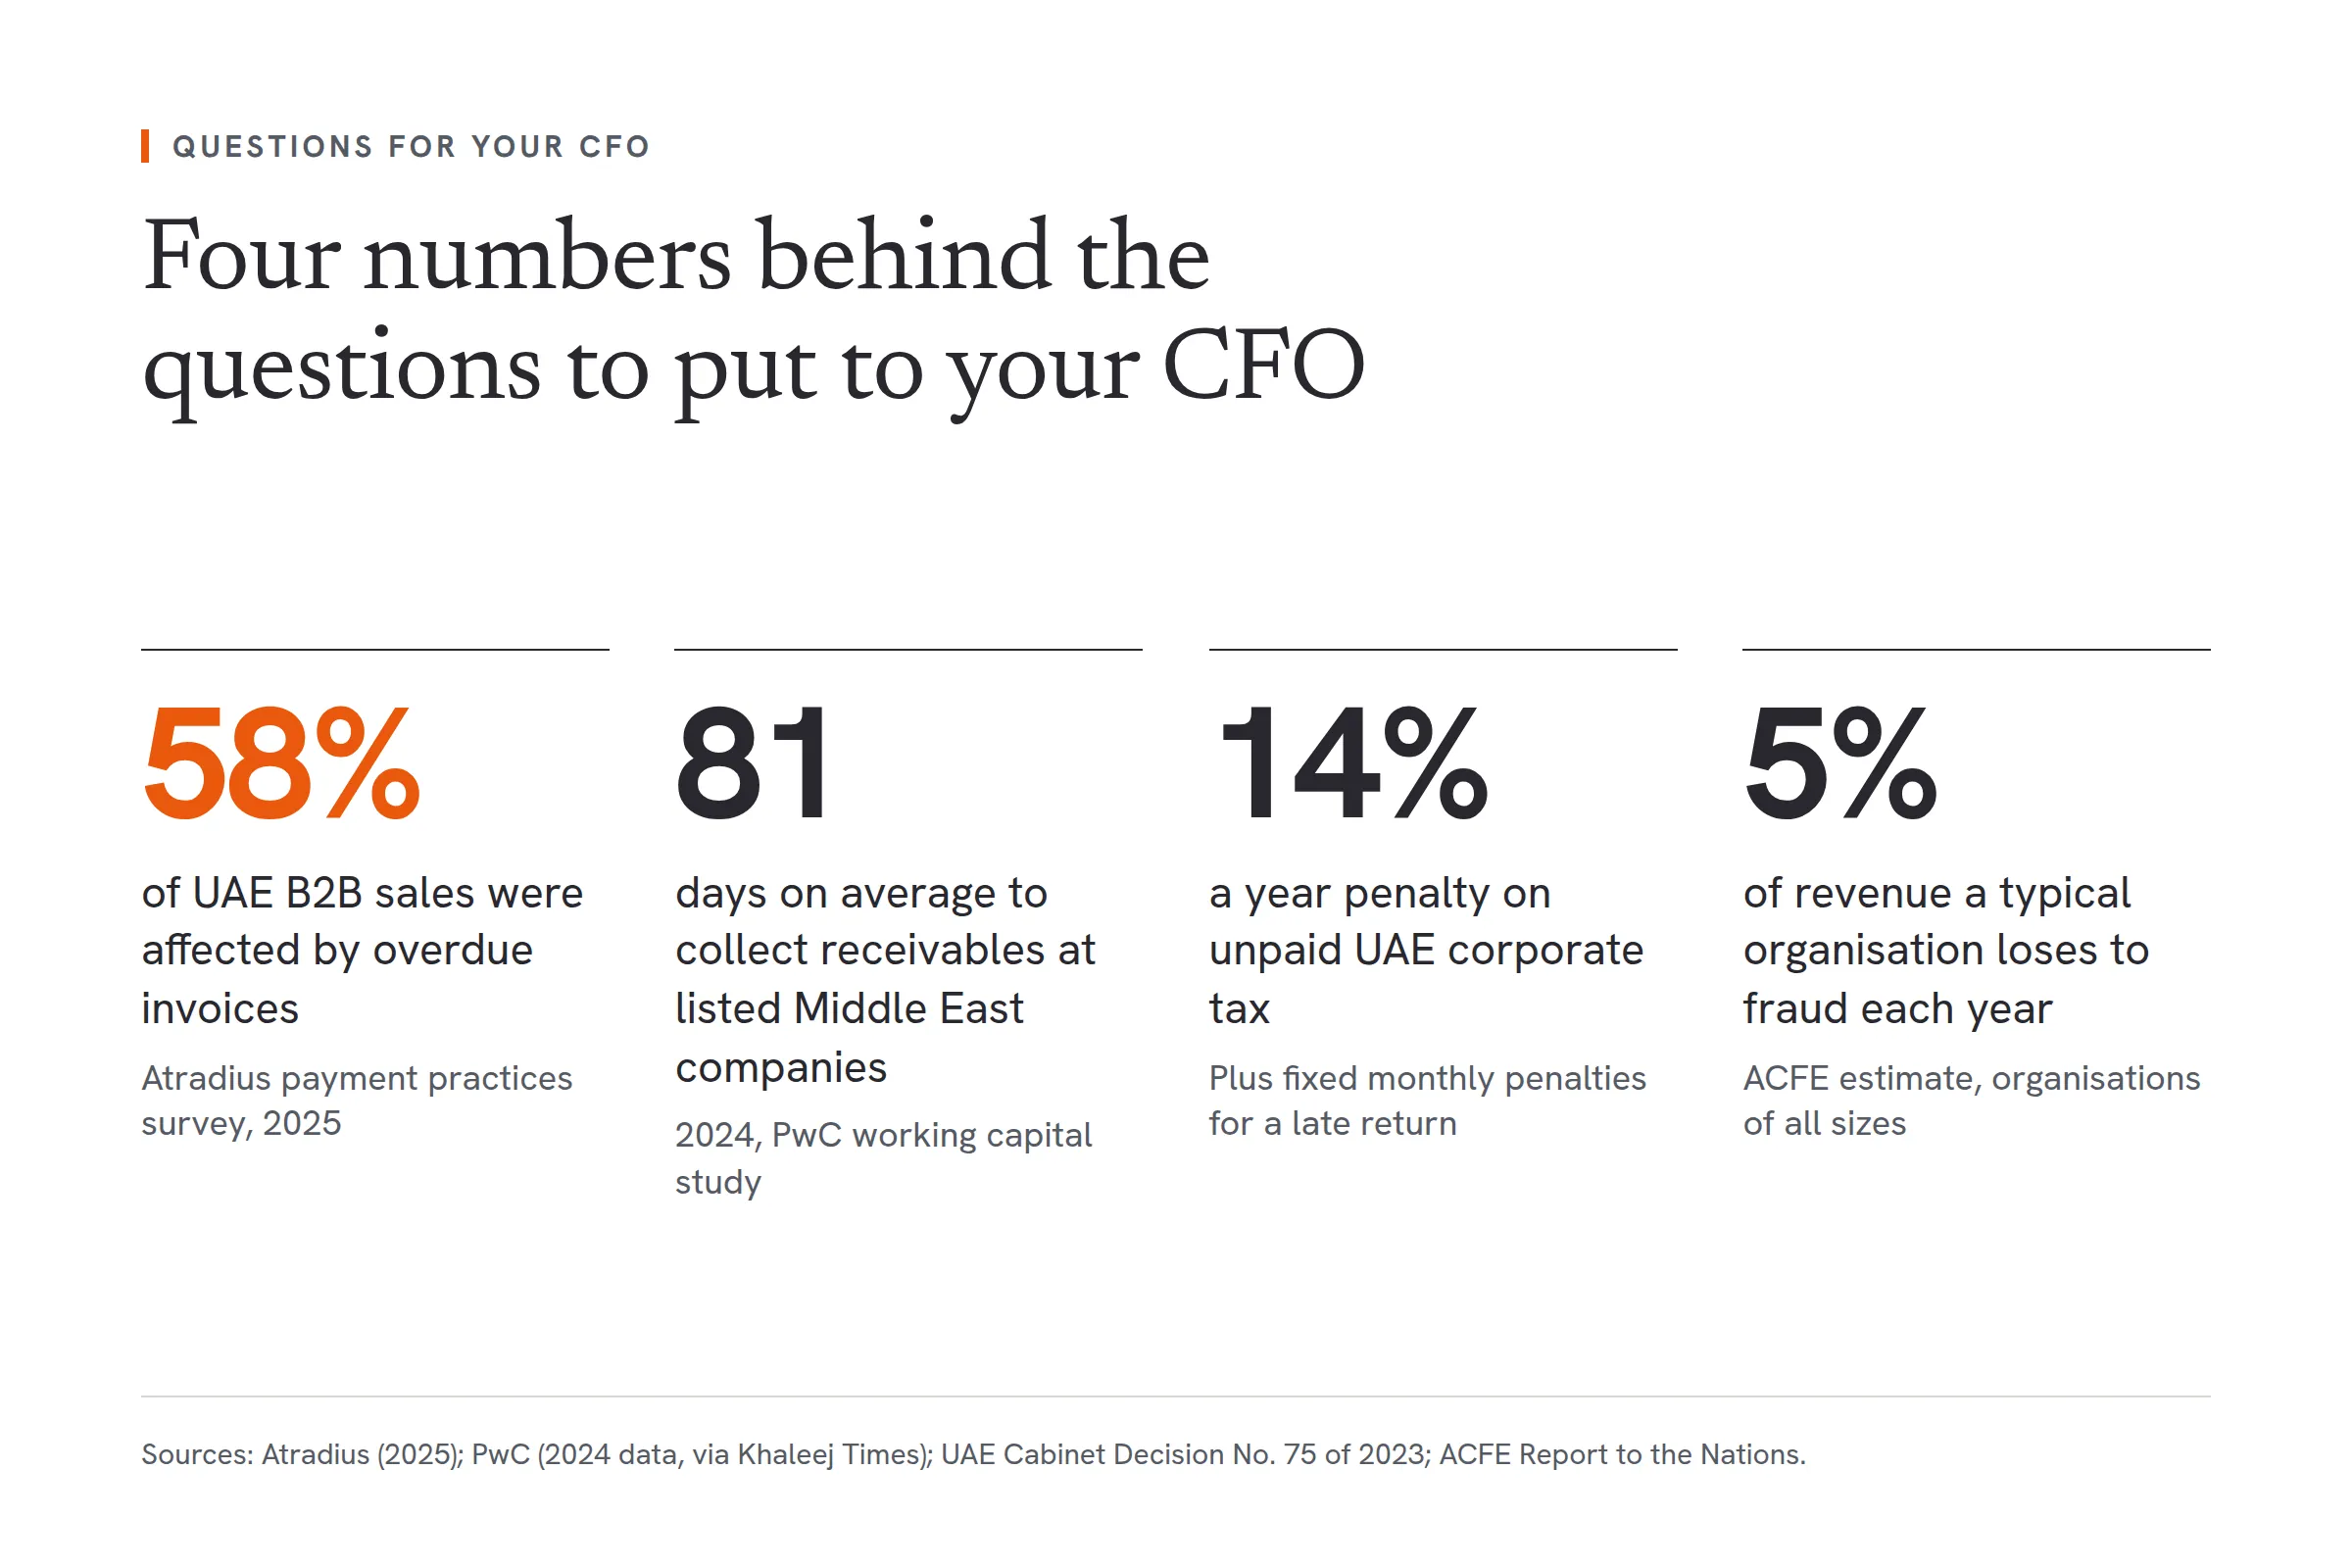
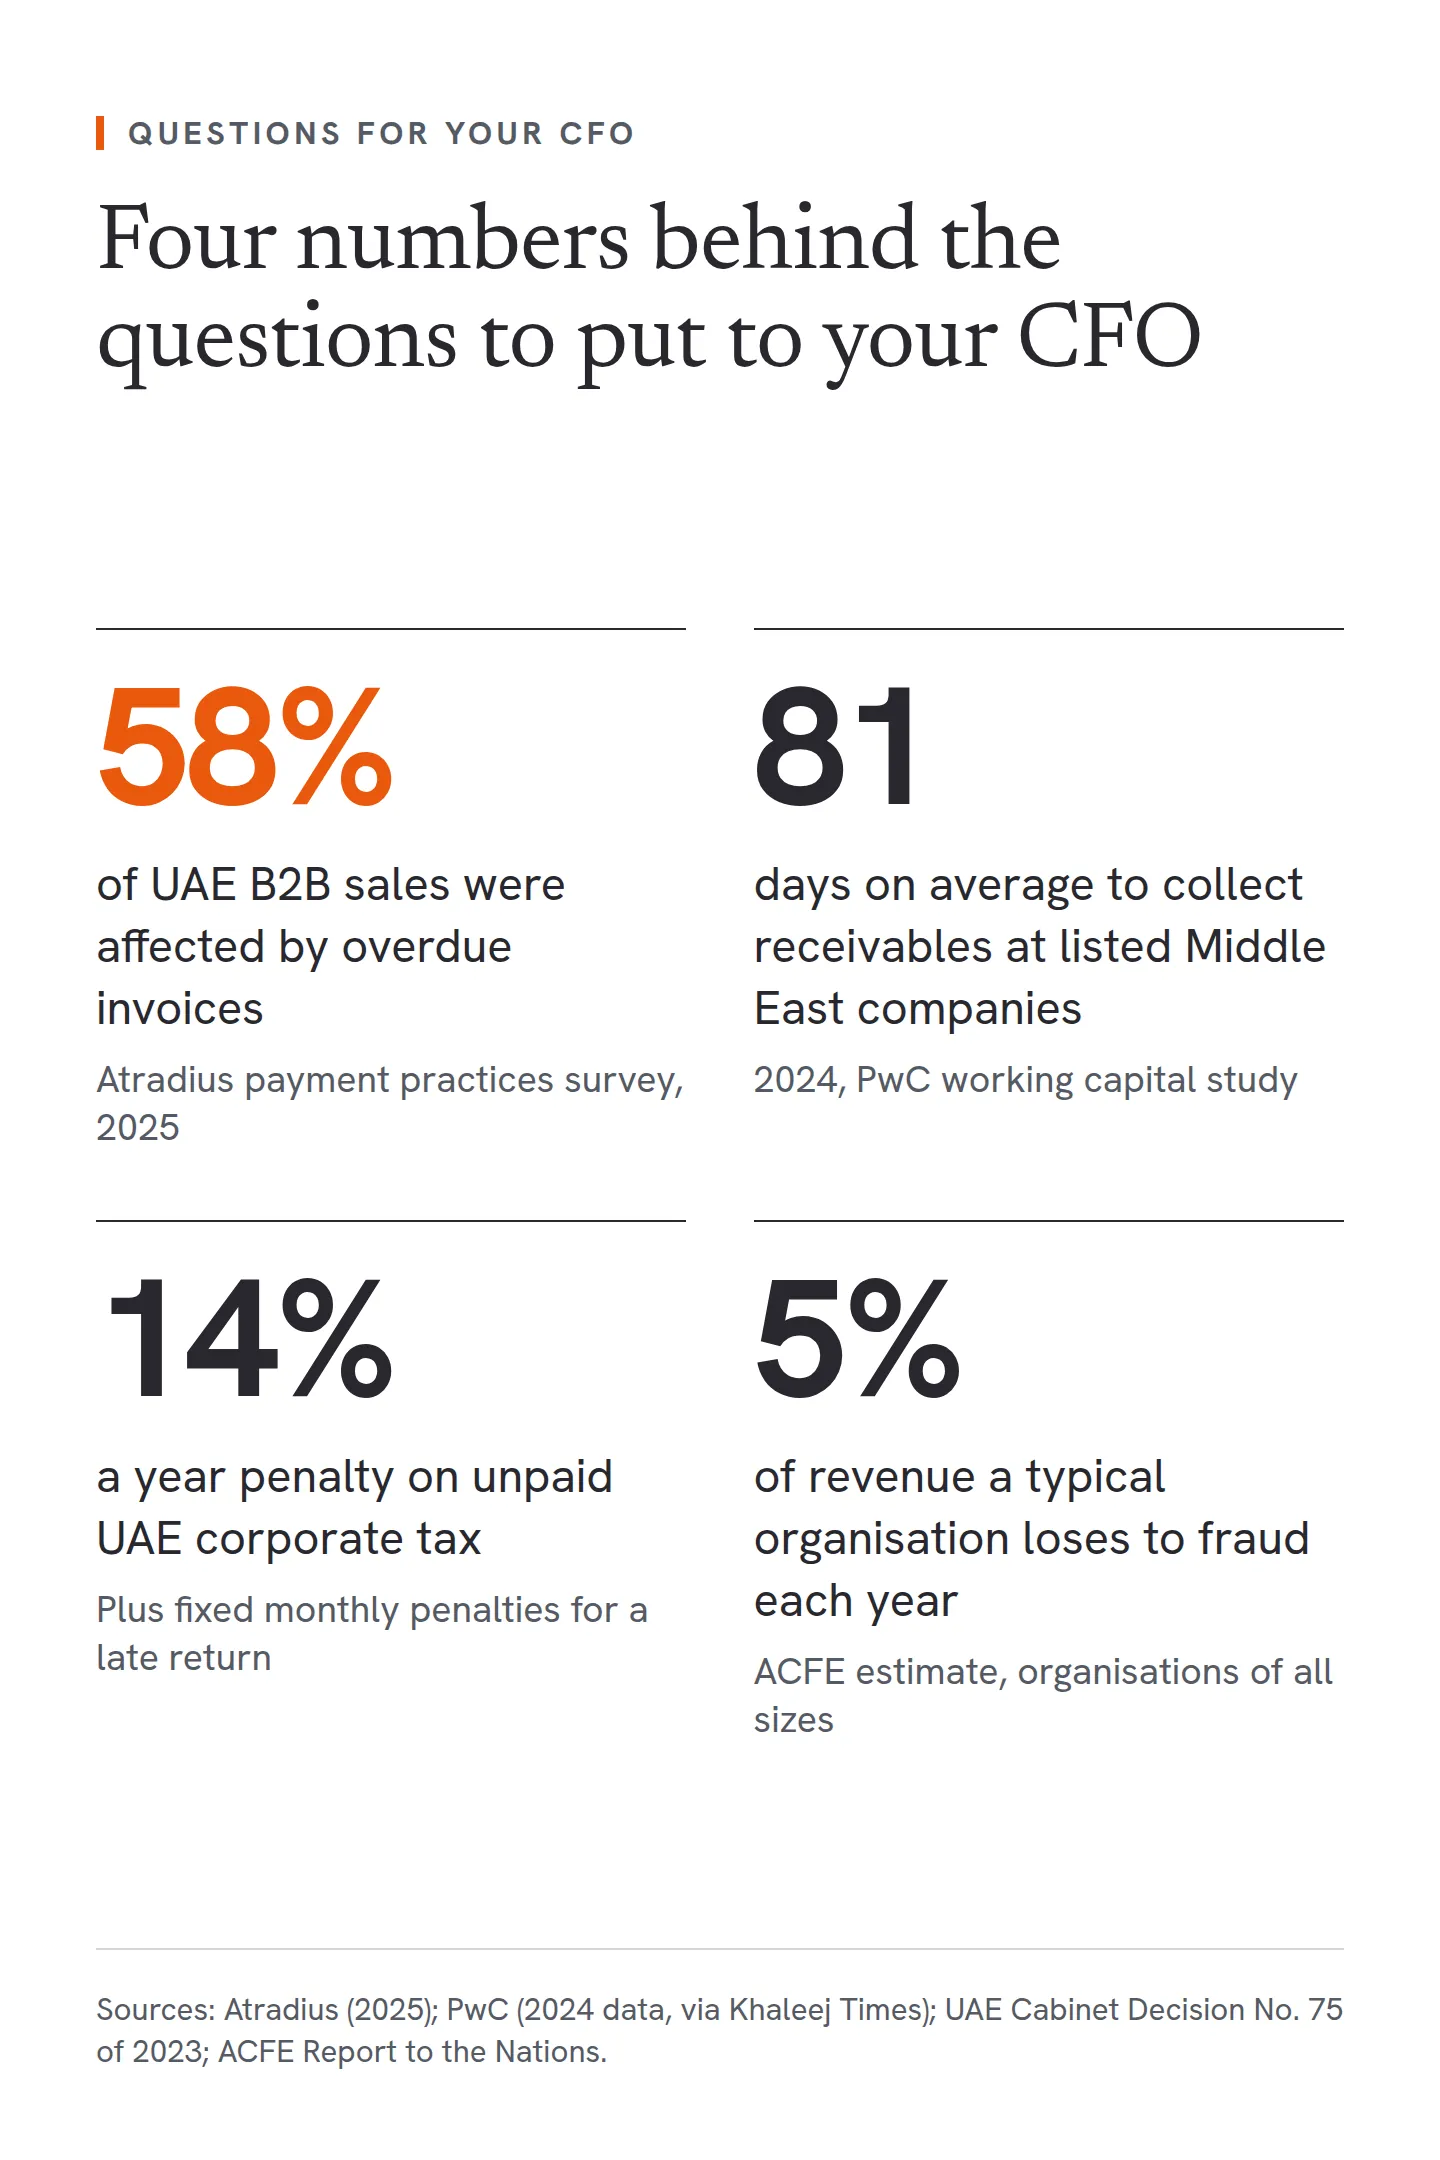
Cash flow surprises are like sandstorms: they hit fast and leave a mess. A rolling 13-week cash flow forecast shows you what is coming before it hits, which matters in a market where late payment is common. Overdue invoices affected 58% of UAE B2B sales in Atradius's 2025 payment practices survey. Not sure if you need CFO support? Take our CFO readiness assessment. Picture a business about to sign a lease on two new work trucks, where the forecast shows the cash running out six weeks later. Pausing the lease, or staging it, avoids a painful mistake.
2. “How much do we need to sell this quarter to break even?”
If you do not know your break-even point, you are flying blind. Separating fixed from variable costs tells you exactly how much revenue covers your overhead. A Dubai catering business, for example, could use that figure to set realistic sales targets and stop underpricing corporate packages just to win deals.
3. “How do I know if we’re pricing our jobs, products, or services correctly?”
Gut feeling is not a pricing model. With proper cost breakdowns, overhead allocation and margin analysis, you can adjust prices with confidence. A contractor who wins plenty of jobs but still loses money each quarter is the classic case: rebuilding the price list from actual costs and overheads usually restores margin within a few months.
4. “Can we model how a 5% cost increase will impact our gross margin?”
Even small cost increases can have a big impact. Building what-if scenarios quantifies that risk before it eats into profit. Take a manufacturer whose raw materials are 60% of revenue and whose gross margin is 10%: a 5% rise in material costs removes 3 points of margin, nearly a third of it. That insight is what prompts a renegotiation with suppliers and a plan to pass costs on to customers if needed.
5. “Which customers or product lines are least profitable, and why?”
Not all revenue is created equal. A profitability analysis shows which clients, products or locations drag down the bottom line. Imagine a Dubai printing company with six product lines. The overall P&L is profitable, but split by product line, one line produces 70% of the profit and two are losing money. Now you can grow the profitable lines and make data-based decisions about the losers.
6. “Are we setting aside enough to cover upcoming tax payments?”
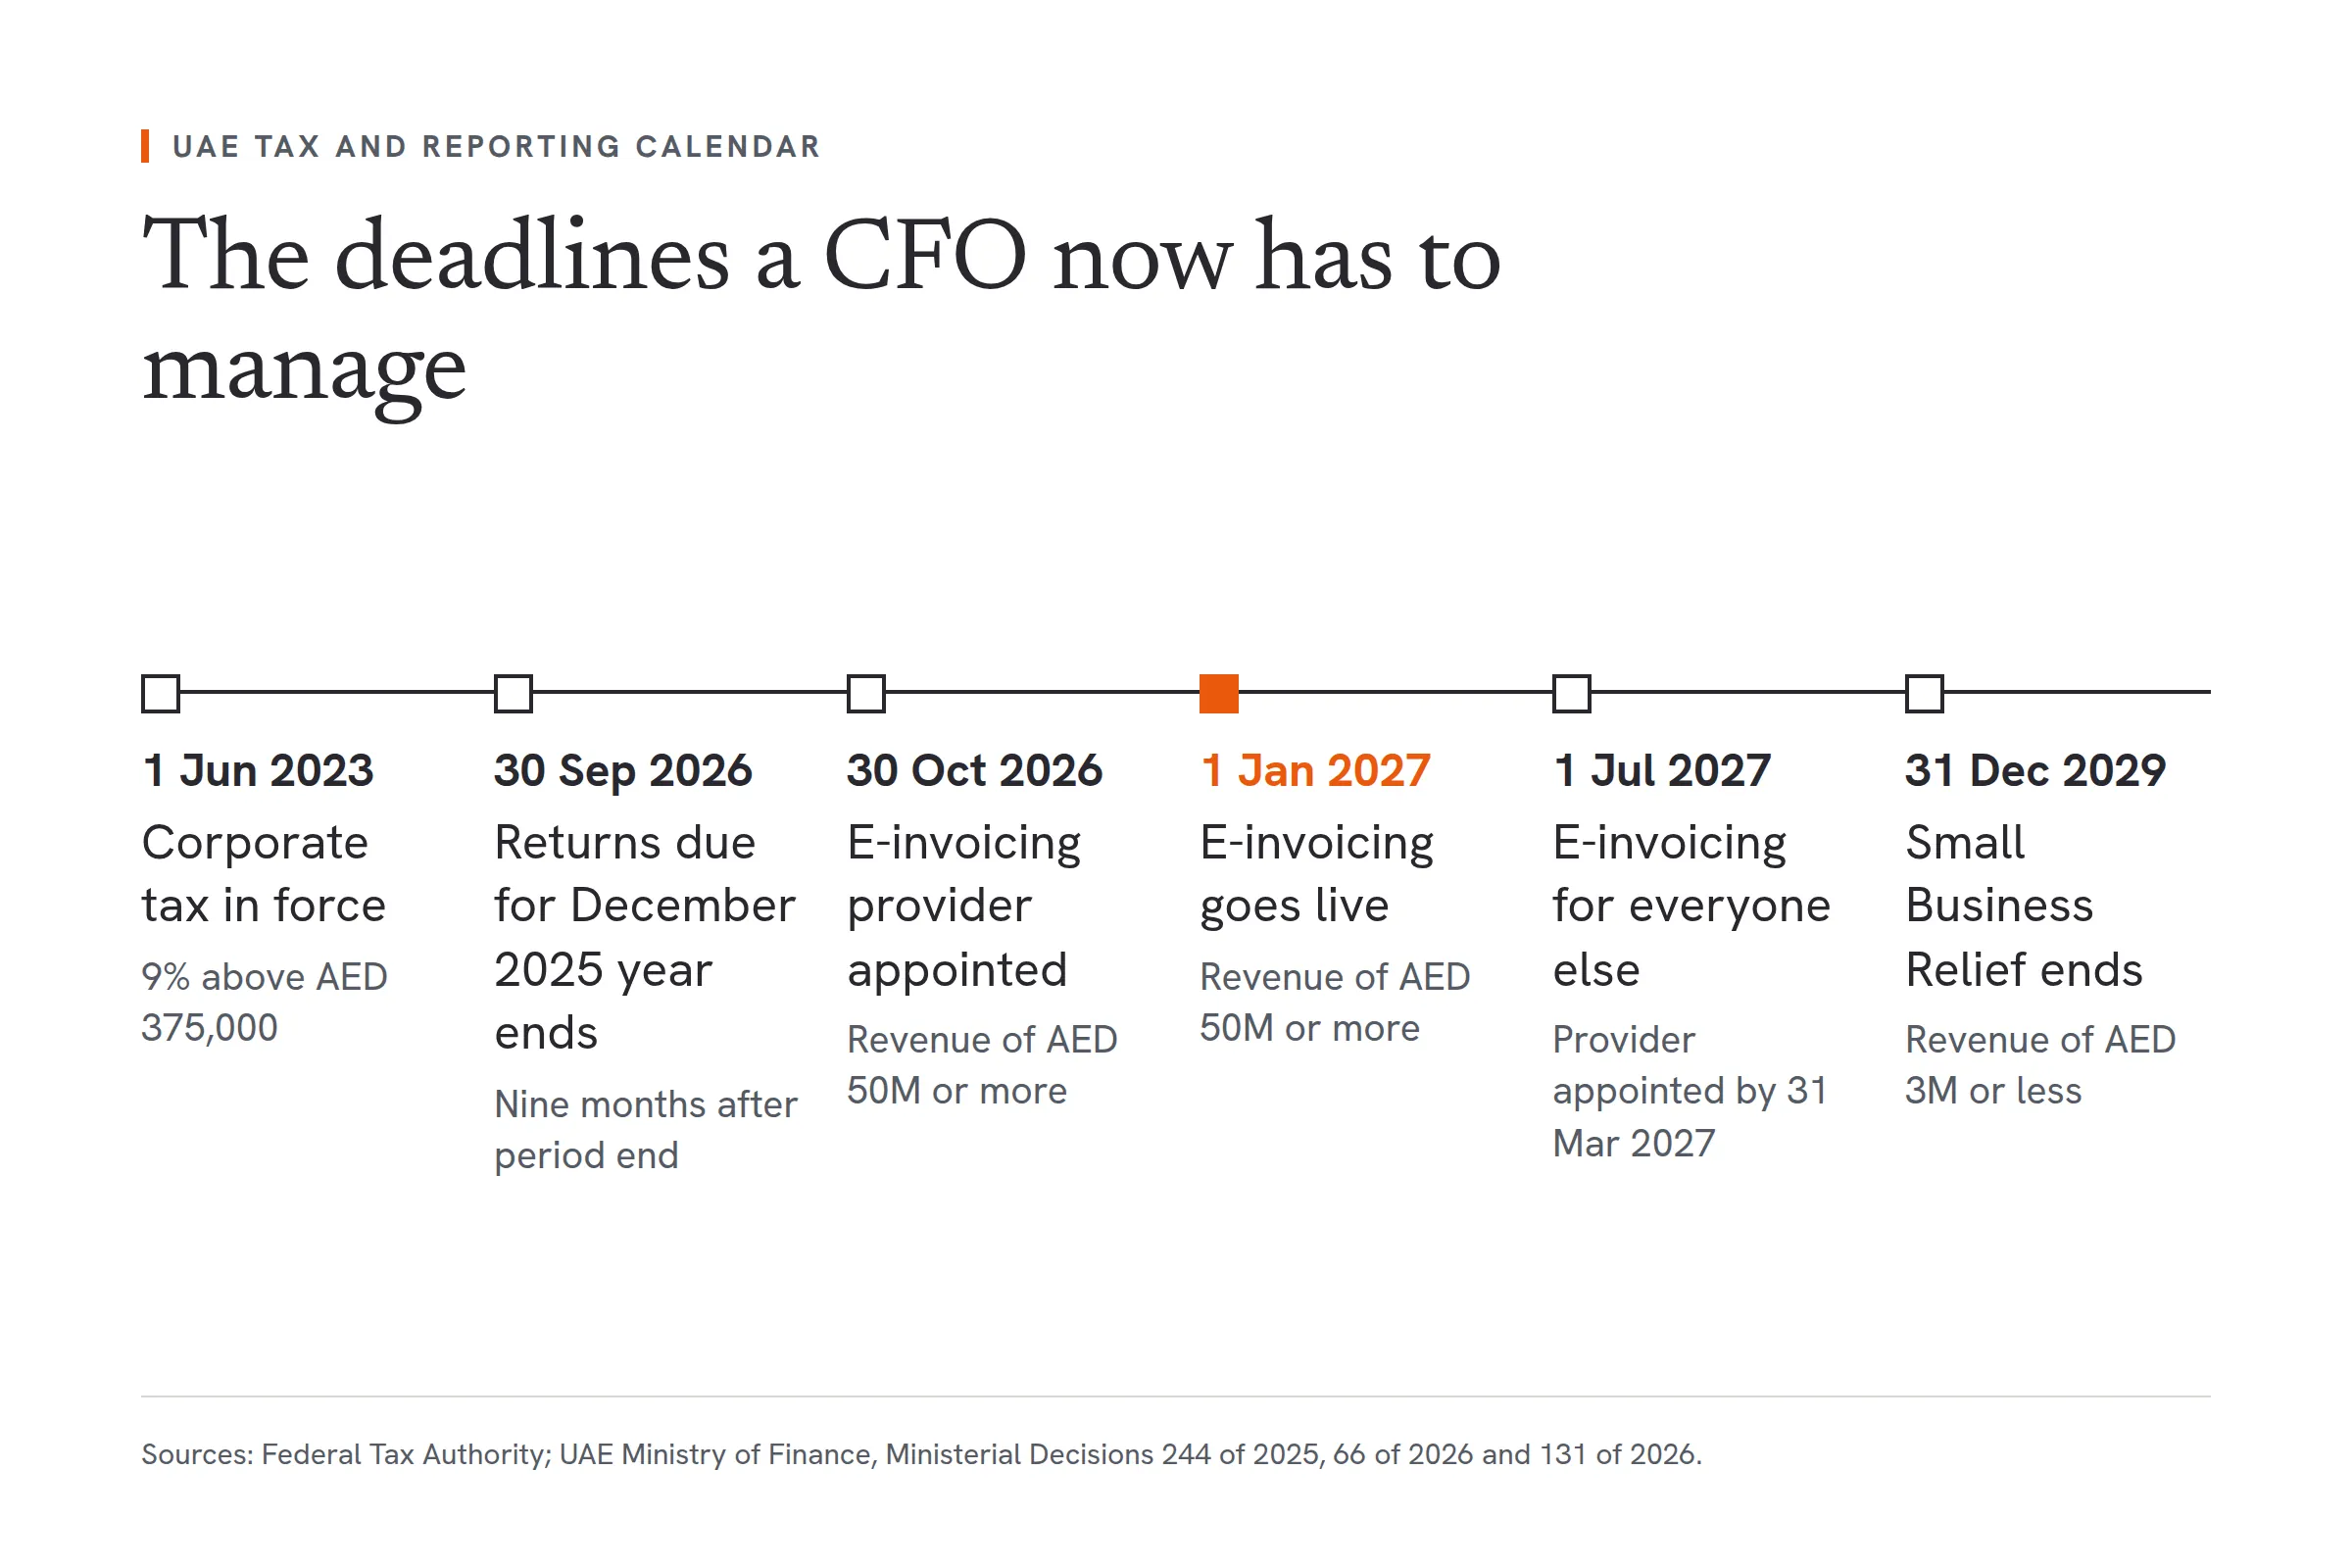
UAE corporate tax is 9% on taxable income above AED 375,000, according to the Federal Tax Authority, and many Dubai SMEs are still learning to plan for it. The return and the payment fall due together, within nine months of the end of the tax period: 30 September for a business with a December year end, which has just passed for the 2025 financial year. Late payment carries a penalty of 14% a year on the unpaid tax, plus fixed monthly penalties for a late return. Set up monthly accruals so the bill never arrives as a surprise.
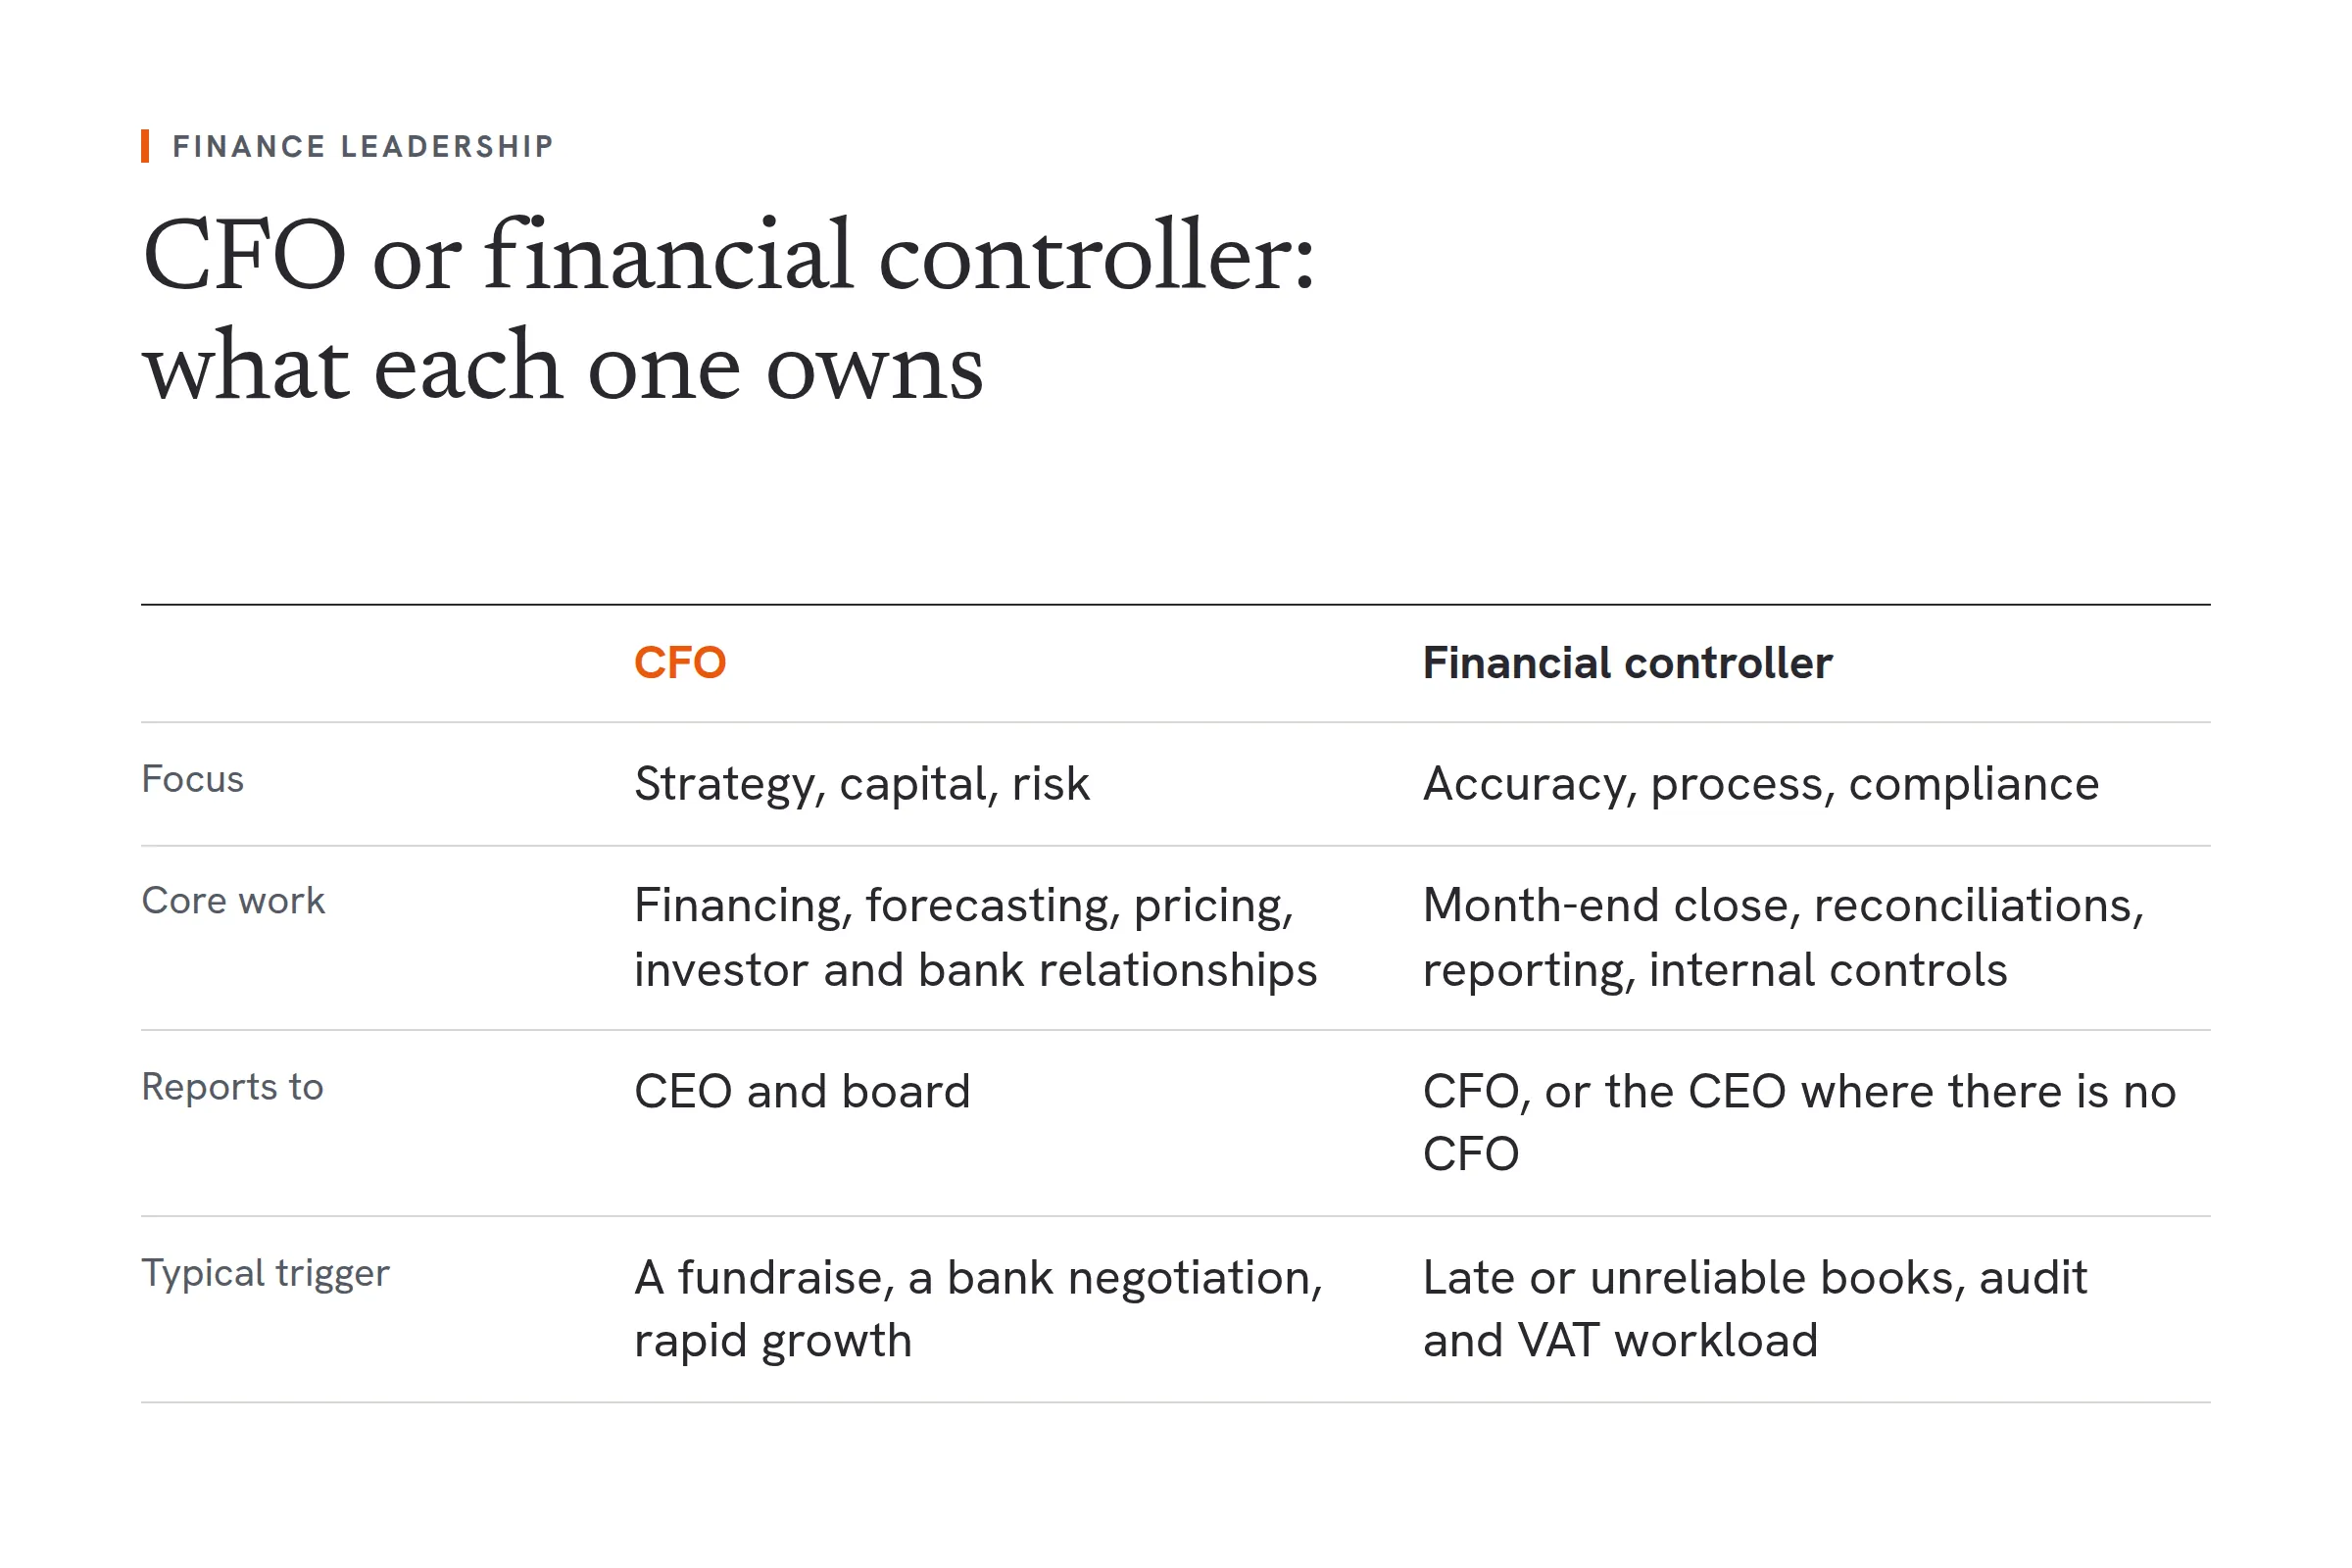
Small Business Relief is also worth asking about. The Ministry of Finance has extended it to tax periods ending on or before 31 December 2029, with the AED 3 million revenue threshold unchanged. If your books are still run at controller level, our CFO vs controller guide explains when strategic leadership should sit above that function. Learn more about comprehensive CFO services that include tax planning.
E-invoicing is the next compliance project on the same desk. Businesses with annual revenue of AED 50 million or more must start e-invoicing on 1 January 2027, and all others on 1 July 2027, exchanging structured invoices through an Accredited Service Provider. For the larger group, the deadline to appoint that provider moved to 30 October 2026. Ask your CFO who owns it, which provider you will use and whether your accounting system can connect.
7. “Are we on track to hit our financial targets this year?”
Having annual goals is one thing; tracking them is another. Performance dashboards tied to monthly or quarterly milestones make progress visible in real time. Our CFO ROI calculator shows how Dubai SMEs can quantify the financial upside once those dashboards are in place. A retailer that reviews targets monthly on a simple dashboard can make smarter inventory and staffing decisions, and, combined with operational excellence, stay on track to beat its annual target.
8. “Will we need financing, or can we self-fund growth over the next 6-12 months?”
Growth eats cash, and planning for it is key. Often this requires strategic leadership across multiple functions. Scenario modelling reveals whether internal cash flow is enough or outside financing is needed, the same discipline investors expect once you enter a formal fundraising process. Say you are a GCC logistics company preparing to expand your fleet, and scenario modelling shows you would be cash-negative by month four. You can then stagger equipment purchases and tighten receivables, or approach the bank for financing early, while you still have options.
9. “Where can we find the working capital needed to fulfil this new contract we just signed?”
New contracts often require upfront costs for staff, materials or inventory before the first dirham is received. Reviewing working capital levers such as payment terms, receivables and inventory timing can free up hidden liquidity. Publicly listed companies in the Middle East averaged 81 days to collect receivables in 2024, according to PwC's working capital study, so collection discipline is rarely wasted effort. If short-term cash is still needed, there are options other than the bank, depending on the situation.
10. “Which variables have the biggest impact on our bottom line?”
Sometimes it is not the biggest line item that makes the biggest difference. A sensitivity analysis pinpoints where small changes have outsized effects. If your net margin is 10%, every 1% discount you give customers removes 10% of your net income. That is the kind of insight that shapes better decisions across the board.
Bonus round
11. “What’s the biggest financial risk we’re not paying attention to?”
That is the million-dirham question. A good CFO reviews your balance sheet, cash flows and contracts to uncover hidden risks such as underinsured assets, customer concentration or weak internal controls. The Association of Certified Fraud Examiners estimates that a typical organisation loses 5% of revenue to fraud each year. Another common blind spot is concentration: a business whose top two customers make up 70% of revenue is happy with the business until one of them leaves.
12. “How can we get our customers to pay us sooner while keeping them happy?”
Cash flow does not just depend on what is sold; it depends on when it is collected. Simple changes to invoicing practices, payment terms or incentive structures can make a big difference. Clear call scripts for receivables follow-up, for instance, can shorten the collection period and leave customers happier, because the conversation is polite, specific and predictable.
13. “When is the right time to take on debt in order to grow the business? How much can I take on safely?”
Debt can be a growth tool, but only when the timing, terms and repayment capacity align. Cash flow forecasting and return-on-investment modelling help answer that. Consider a cleaning services firm that wants more vans and staff but is wary of borrowing. The expansion also needs operational planning for the larger fleet. Modelling the return shows how much debt the business can carry comfortably and when the investment breaks even.
14. “I want to get rid of these loan payments. Should I use working capital to pay them off early?”
It depends. Paying off debt can free up future cash flow, but it can also leave the business exposed in the short term. Say you have spare cash and want to clear a loan before year end to save interest. Plugging that into your cash flow forecast shows very tight cash for the next 60 days because of seasonality, with no room for surprises. You then decide on the numbers instead of guessing.
Have questions like these come up in your business? Take our executive readiness assessment to identify your specific needs.
Heidrick & Struggles reports that C-suite interim engagements have risen 151% since 2021, so senior finance support on a flexible basis is now a mainstream choice. These questions are common across companies in every industry in Dubai, and they are exactly what a good fractional CFO helps to solve. Ready to discuss your specific situation? Apply for a consultation to get started.
With the right financial visibility and guidance, decisions become clearer, risks become manageable and the business becomes a whole lot less stressful. Explore our complete guide to fractional CFO services to learn more.