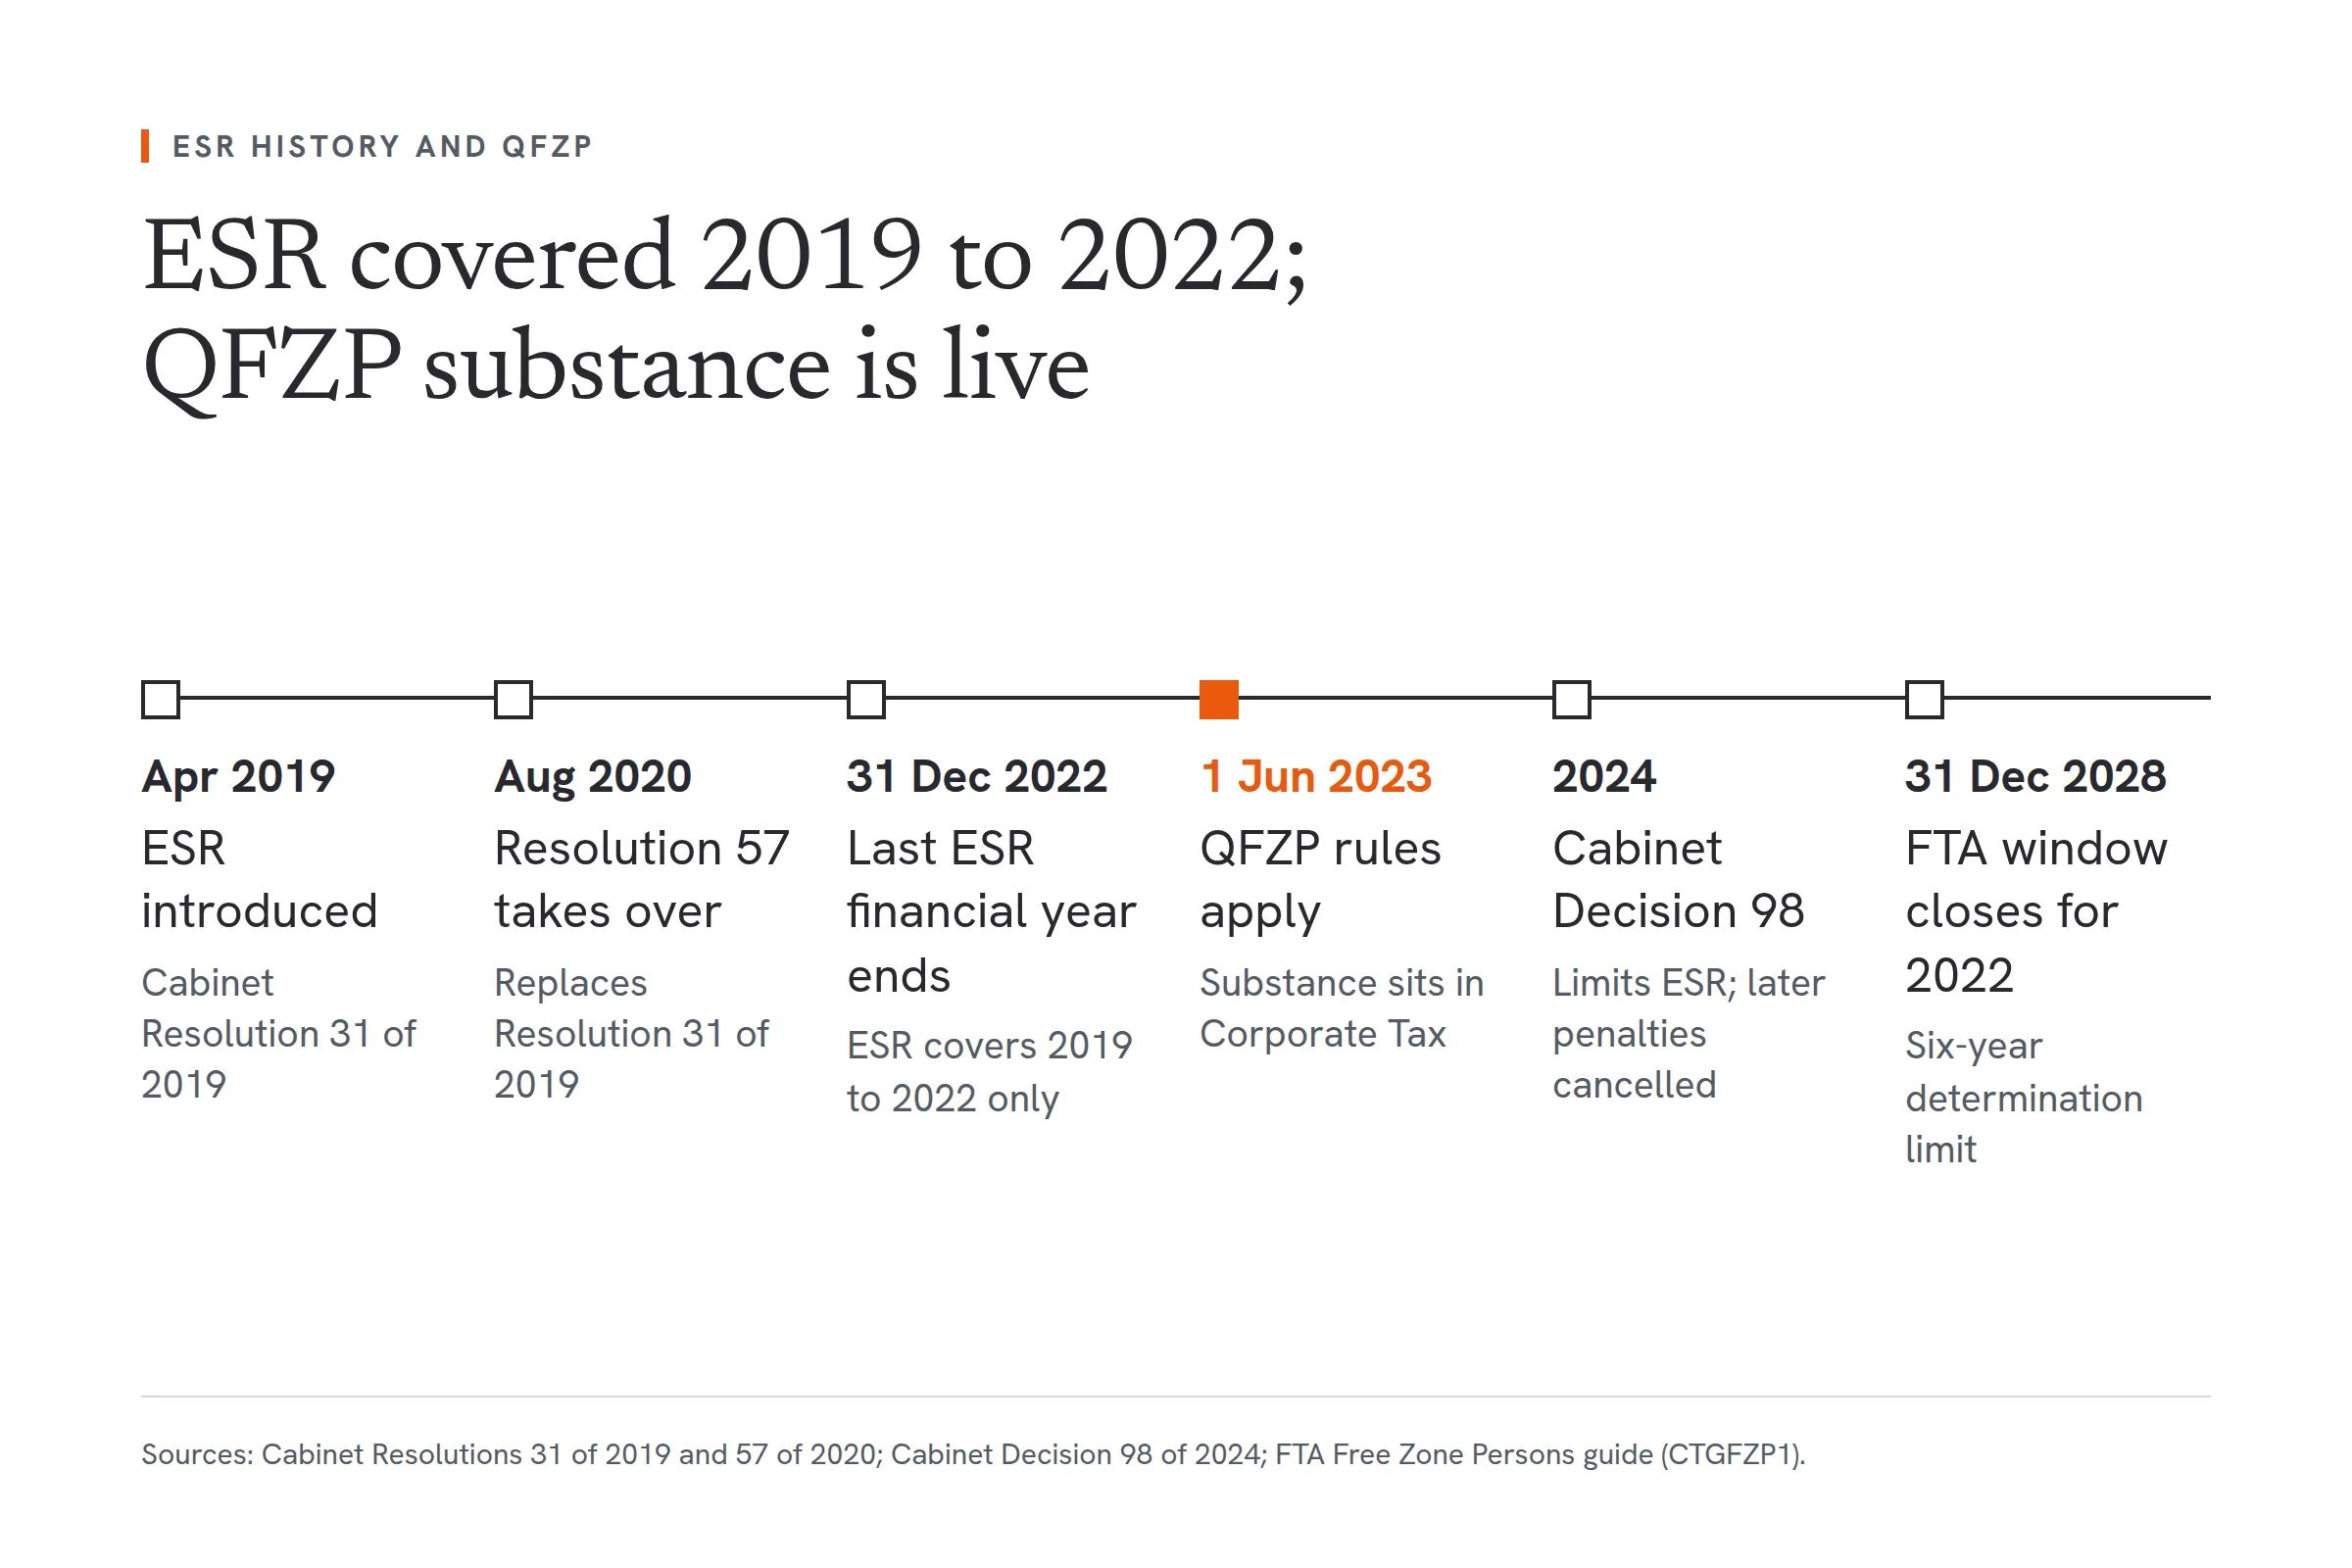
Update, September 2026. The penalties described here apply only to the historic ESR period, financial years from 1 January 2019 to 31 December 2022. Cabinet Decision 98 of 2024 amended Cabinet Decision 57 of 2020 so that ESR no longer applies to any financial year ending after 31 December 2022: for those later periods there is no notification, no report and no penalty exposure. Penalties already levied for them were cancelled, and amounts already paid are refunded by the Federal Tax Authority. This article is kept as a historical record of how the regime was enforced. If you run a free zone business today, the live question is the adequate-substance condition attached to Qualifying Free Zone Person status under UAE Corporate Tax.
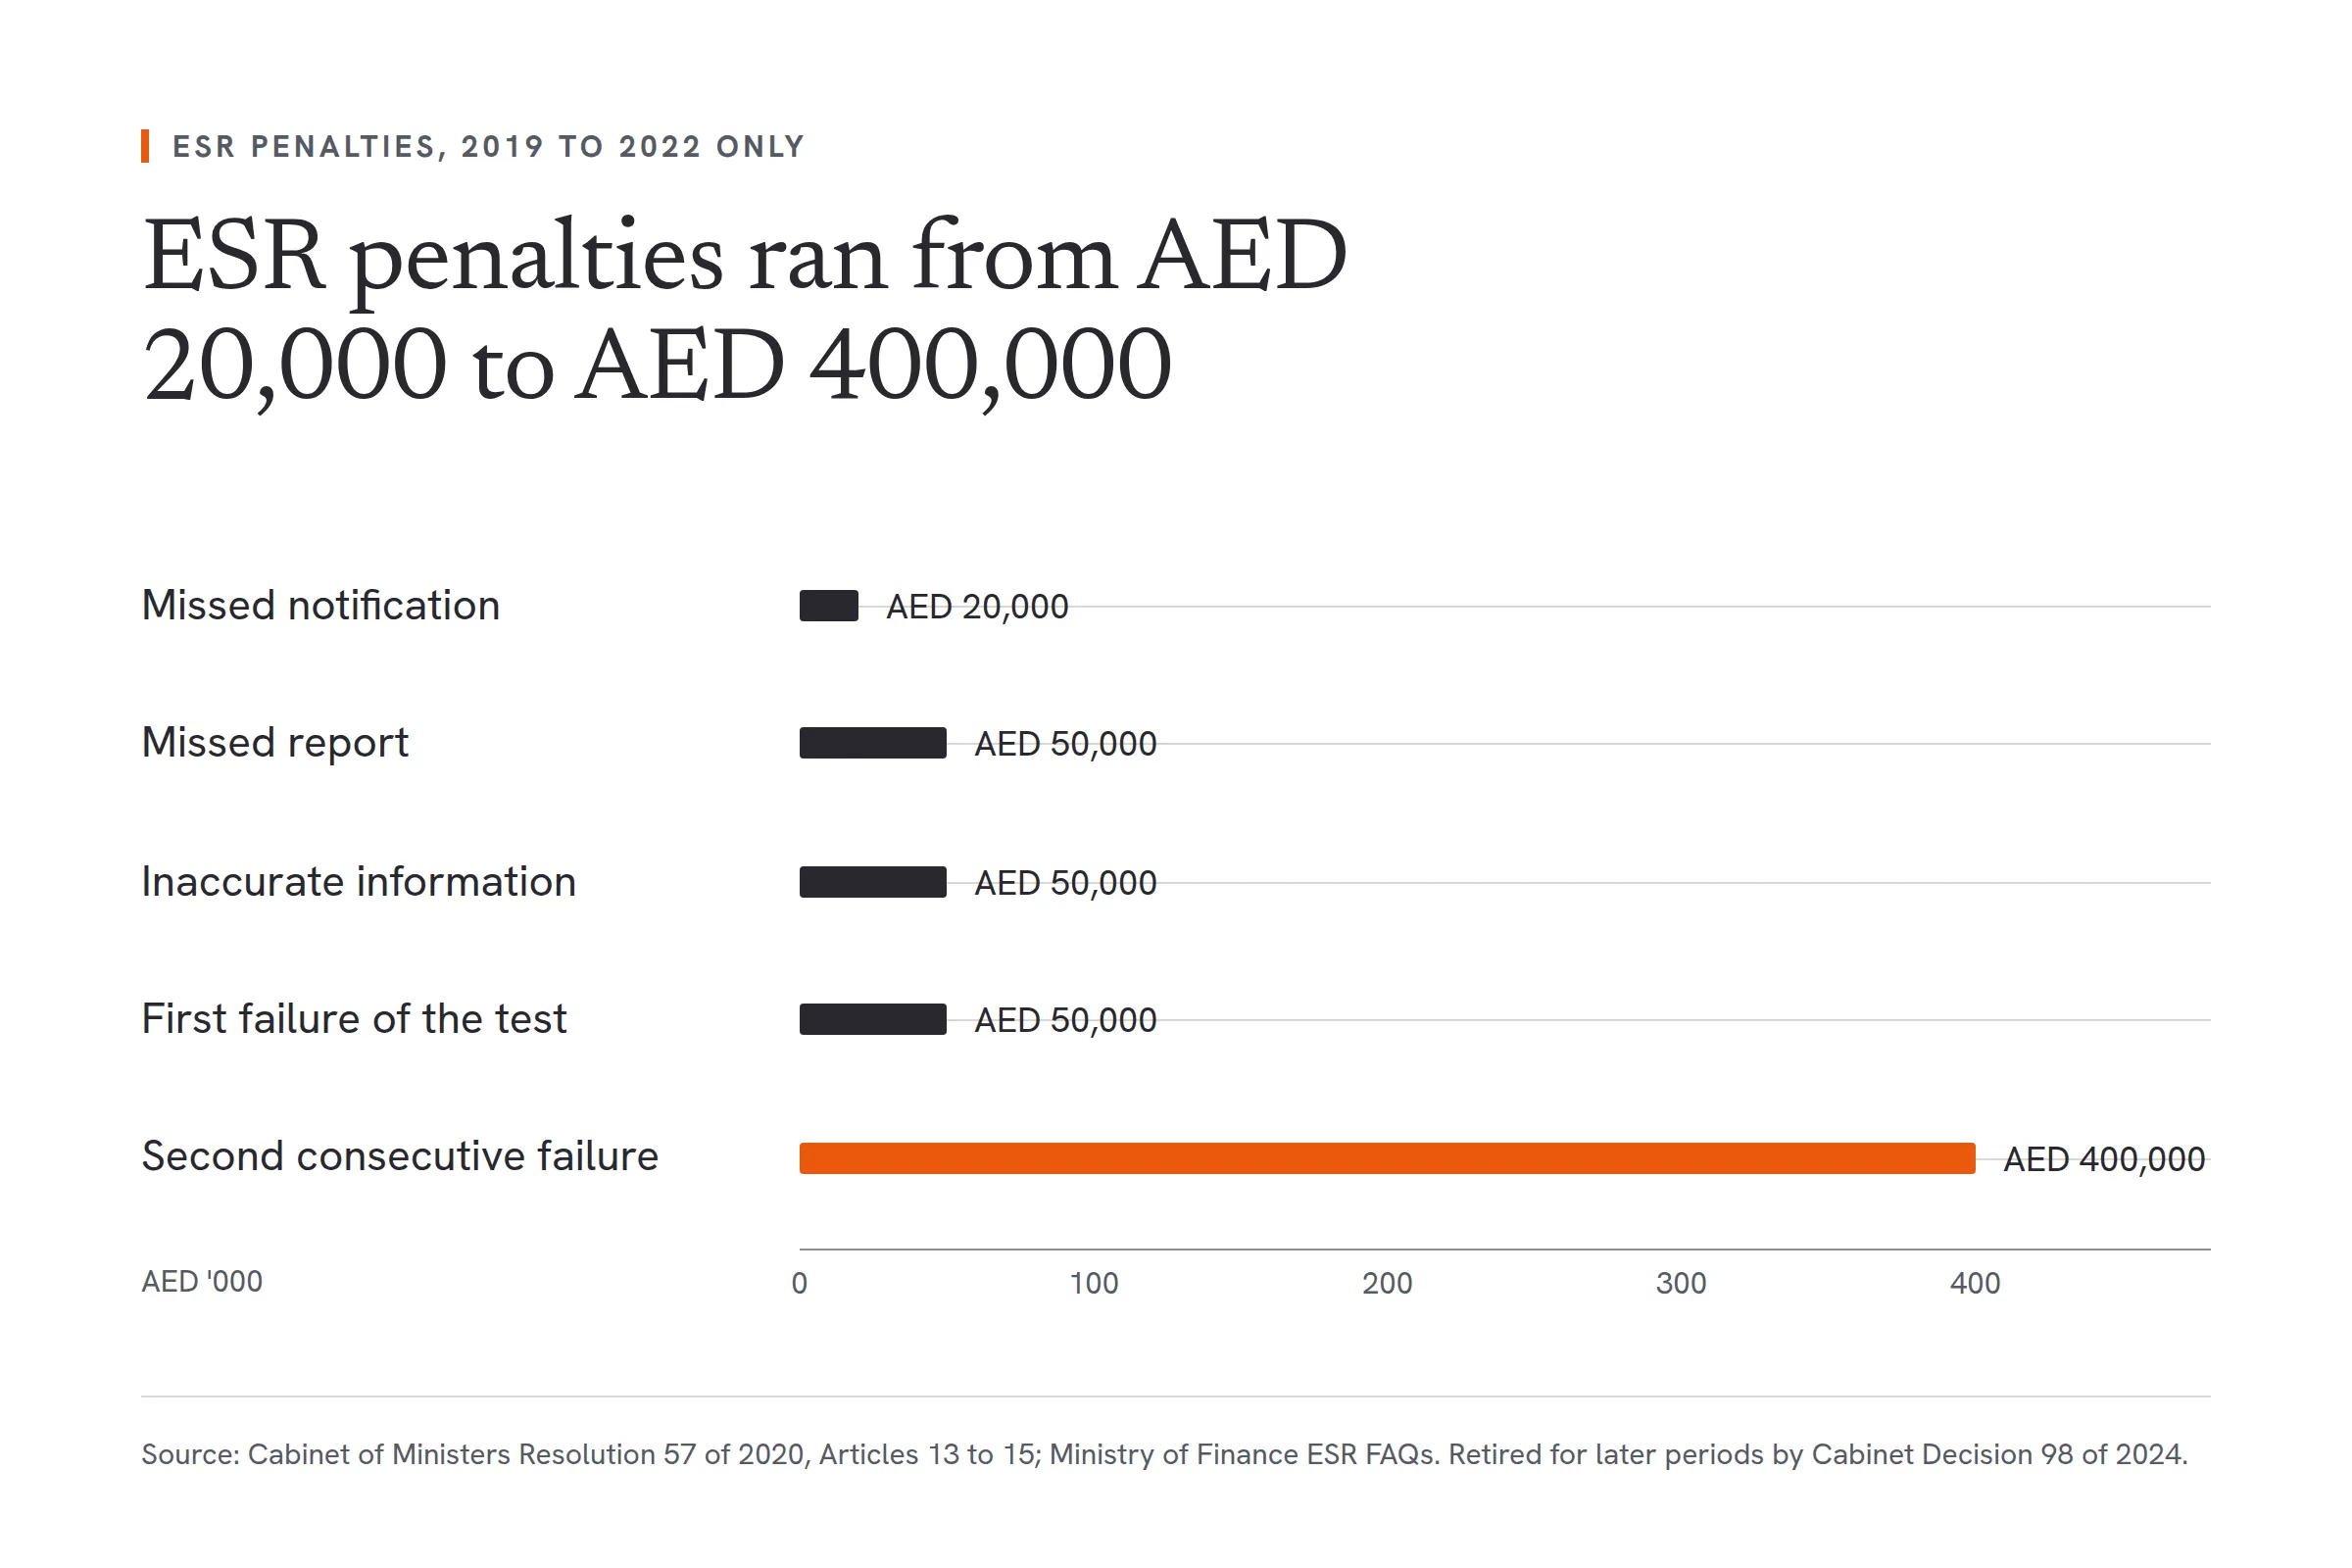
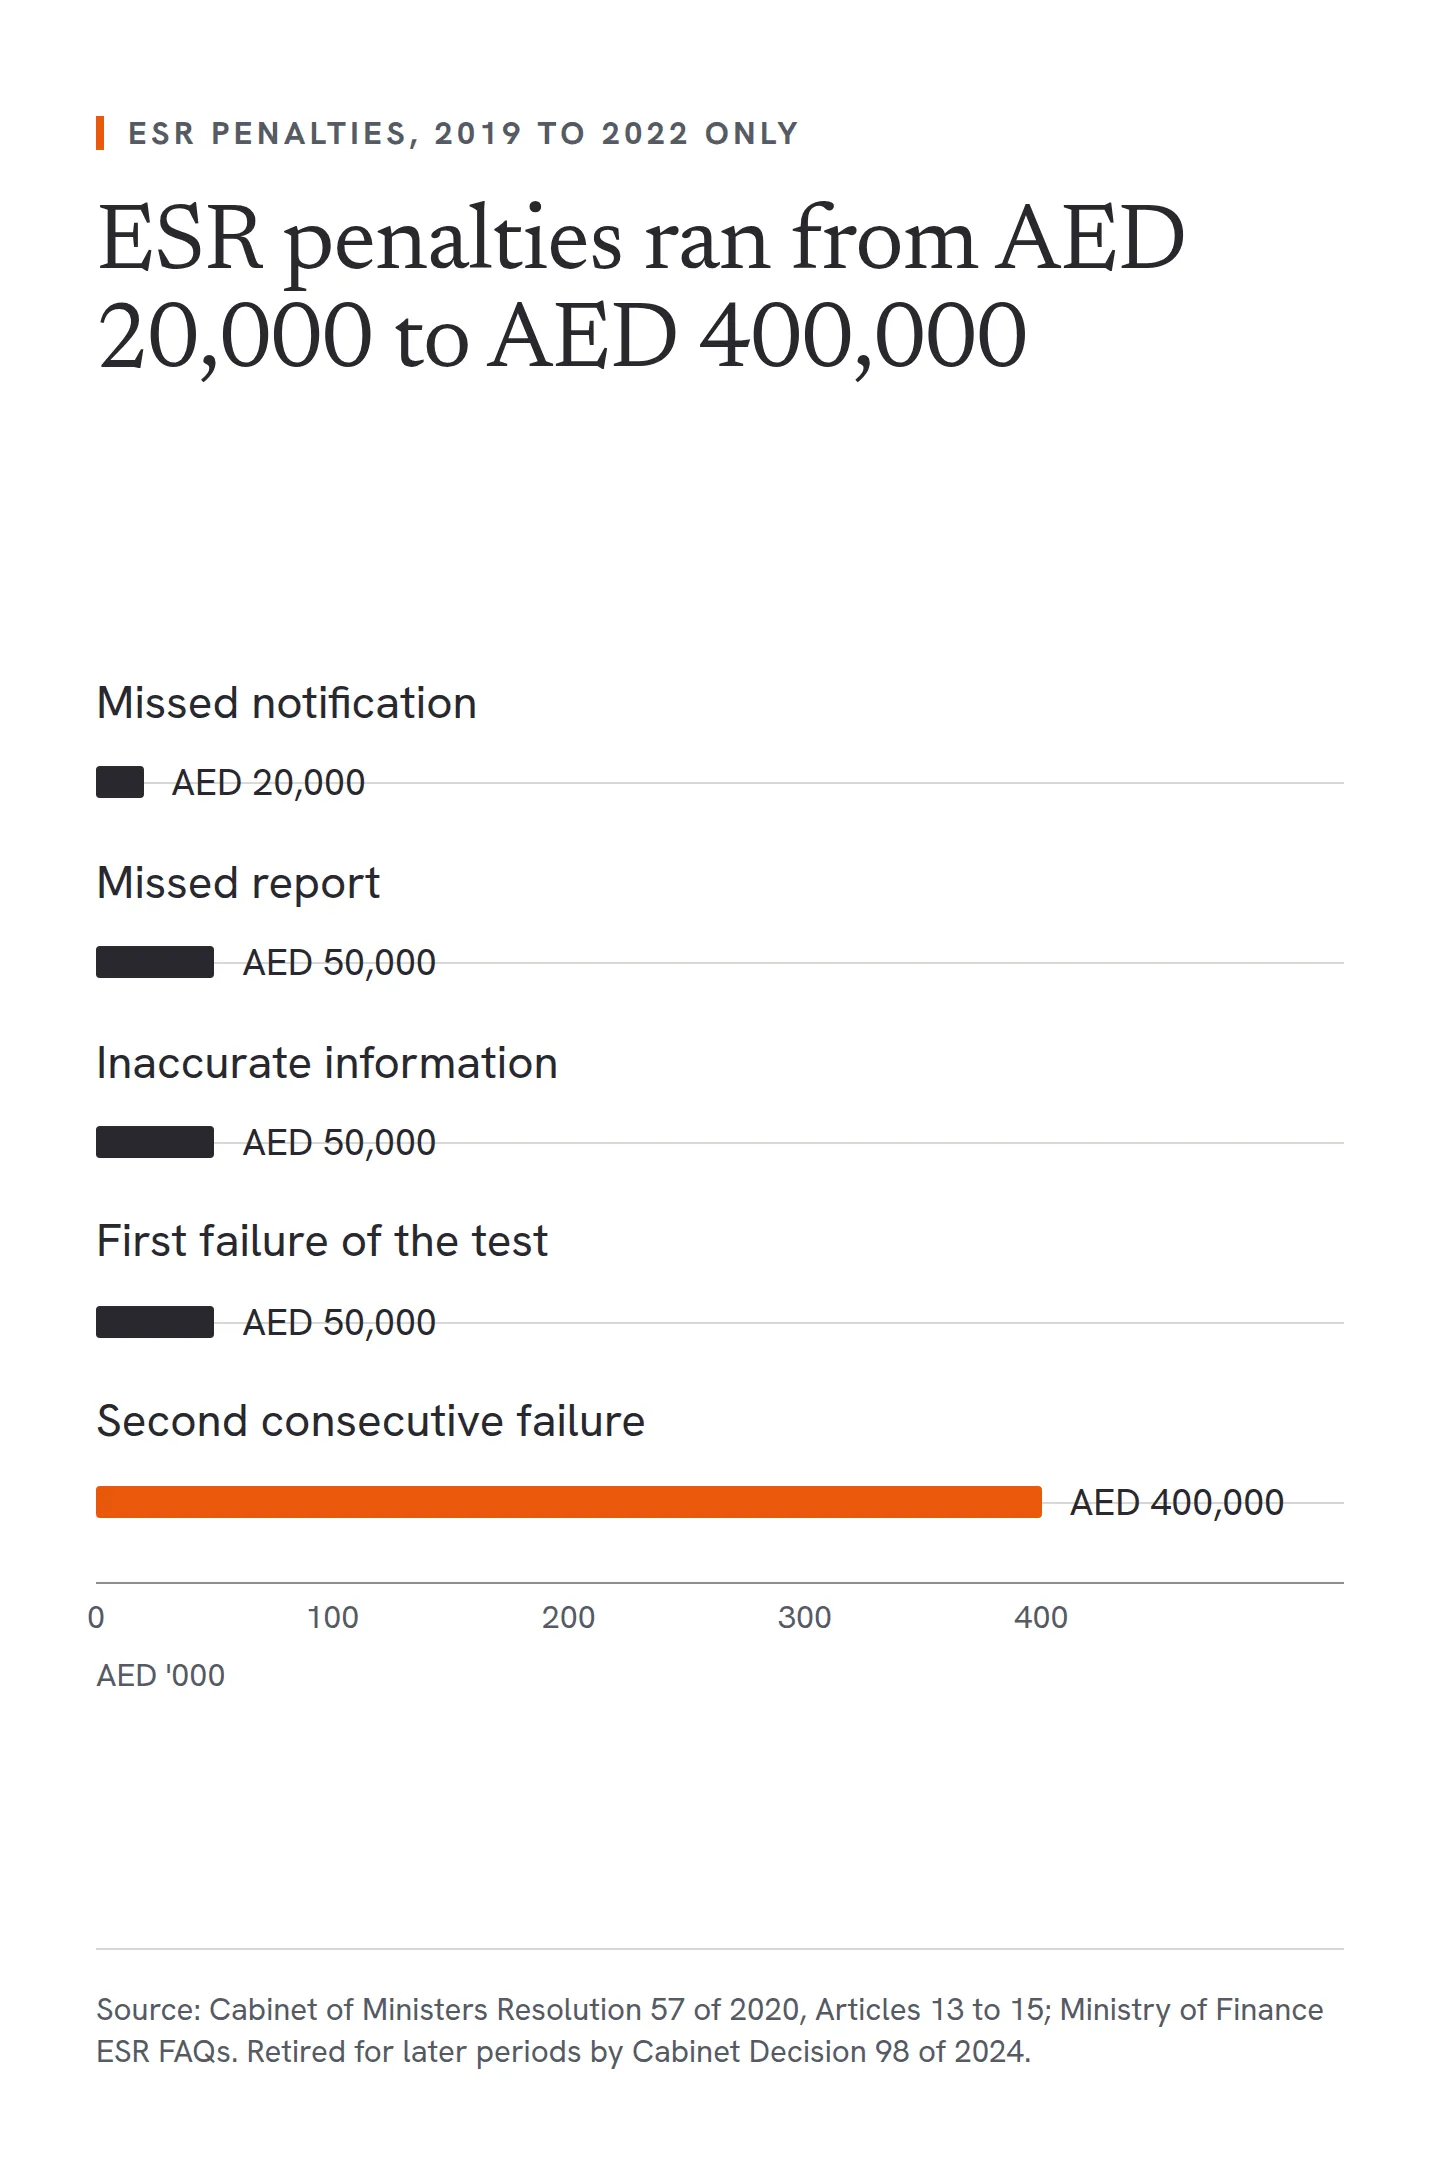
In short: The Economic Substance Regulations (ESR) penalty schedule ran from AED 20,000 to AED 400,000 and applies only to financial years 2019 to 2022. A missed notification cost AED 20,000, a missed report or a first failure of the substance test AED 50,000, and a second consecutive failure AED 400,000. The live substance exposure now sits with Qualifying Free Zone Person status.
ESR penalties in the UAE: what businesses needed to know
The Economic Substance Regulations carried a fixed penalty schedule: AED 20,000 for a missed notification, AED 50,000 for a missed report or a first failure of the substance test, and AED 400,000 for a second consecutive failure. Those penalties apply only to the historic 2019-2022 period. Cabinet Decision 98 of 2024 ended ESR for financial years ending after 31 December 2022 and cancelled the penalties for later periods. The 2019-2022 obligations remain enforceable until their time bars expire.
Most violations came from misunderstanding or neglect, not bad faith. Most were preventable with proper structure and documentation. The lessons still matter, because the same evidence now underpins the free zone substance condition under Corporate Tax.
What were ESR penalties, and how much did they cost?
The penalty amounts were fixed in Articles 13 to 15 of Cabinet of Ministers Resolution 57 of 2020. The Ministry of Finance's ESR FAQs set out the consequences in full:
Violation | Consequence |
|---|---|
Failure to submit the notification | AED 20,000 |
Failure to submit the economic substance report | AED 50,000, and deemed failure to demonstrate substance |
Providing inaccurate information knowingly and not correcting it | AED 50,000 |
First failure of the substance test | AED 50,000, plus information exchange with the foreign tax authorities of the parent, ultimate parent and ultimate beneficial owner |
Second consecutive failure | AED 400,000, information exchange, and possible suspension, withdrawal or non-renewal of the trade licence |
These were fixed amounts, not a sliding scale. Three things drove the outcome: whether the notification and report were filed, whether the test was met, and whether the failure repeated in the following financial year. A penalty notice had to state the reasons. The amount fell due no earlier than 30 business days after the notice.
How FTA enforcement worked in practice
The Resolution set out the enforcement chain.
1. Collection by regulatory authorities
Free zone authorities, the Ministry of Economy, the Central Bank and the other designated regulators collected the notifications and reports. They had to tell the FTA about any failure to file within 30 business days of becoming aware of it.
2. Assessment by the FTA
The Federal Tax Authority acted as the National Assessing Authority. It assessed whether a licensee had met the test, imposed the penalties and heard appeals. It could make a determination up to six years after the end of the financial year. That time limit did not apply where fraud, misrepresentation or gross negligence prevented a determination.
3. Documentation audits
Authorised personnel of the regulator and the FTA could enter business premises and examine and copy business documents. In practice that meant board minutes and decision-making records, employee and payroll records, evidence of premises and expenditure, and correspondence with related parties.
4. Information exchange
Where a licensee failed the test, the Ministry of Finance passed the information to the foreign tax authorities of the country where its parent, ultimate parent and ultimate beneficial owner reside. For a business with overseas owners, that was often the more serious consequence.
Common compliance failures that triggered penalties
Knowing these mistakes helps you avoid their QFZP equivalents.
Insufficient documentation
Many business owners assumed that doing the work was enough and documentation did not matter. It does. Without board minutes, decision-making records, management reports and contemporaneous evidence of activity, it is very hard to show that the work took place where you say it did.
Weak governance structure
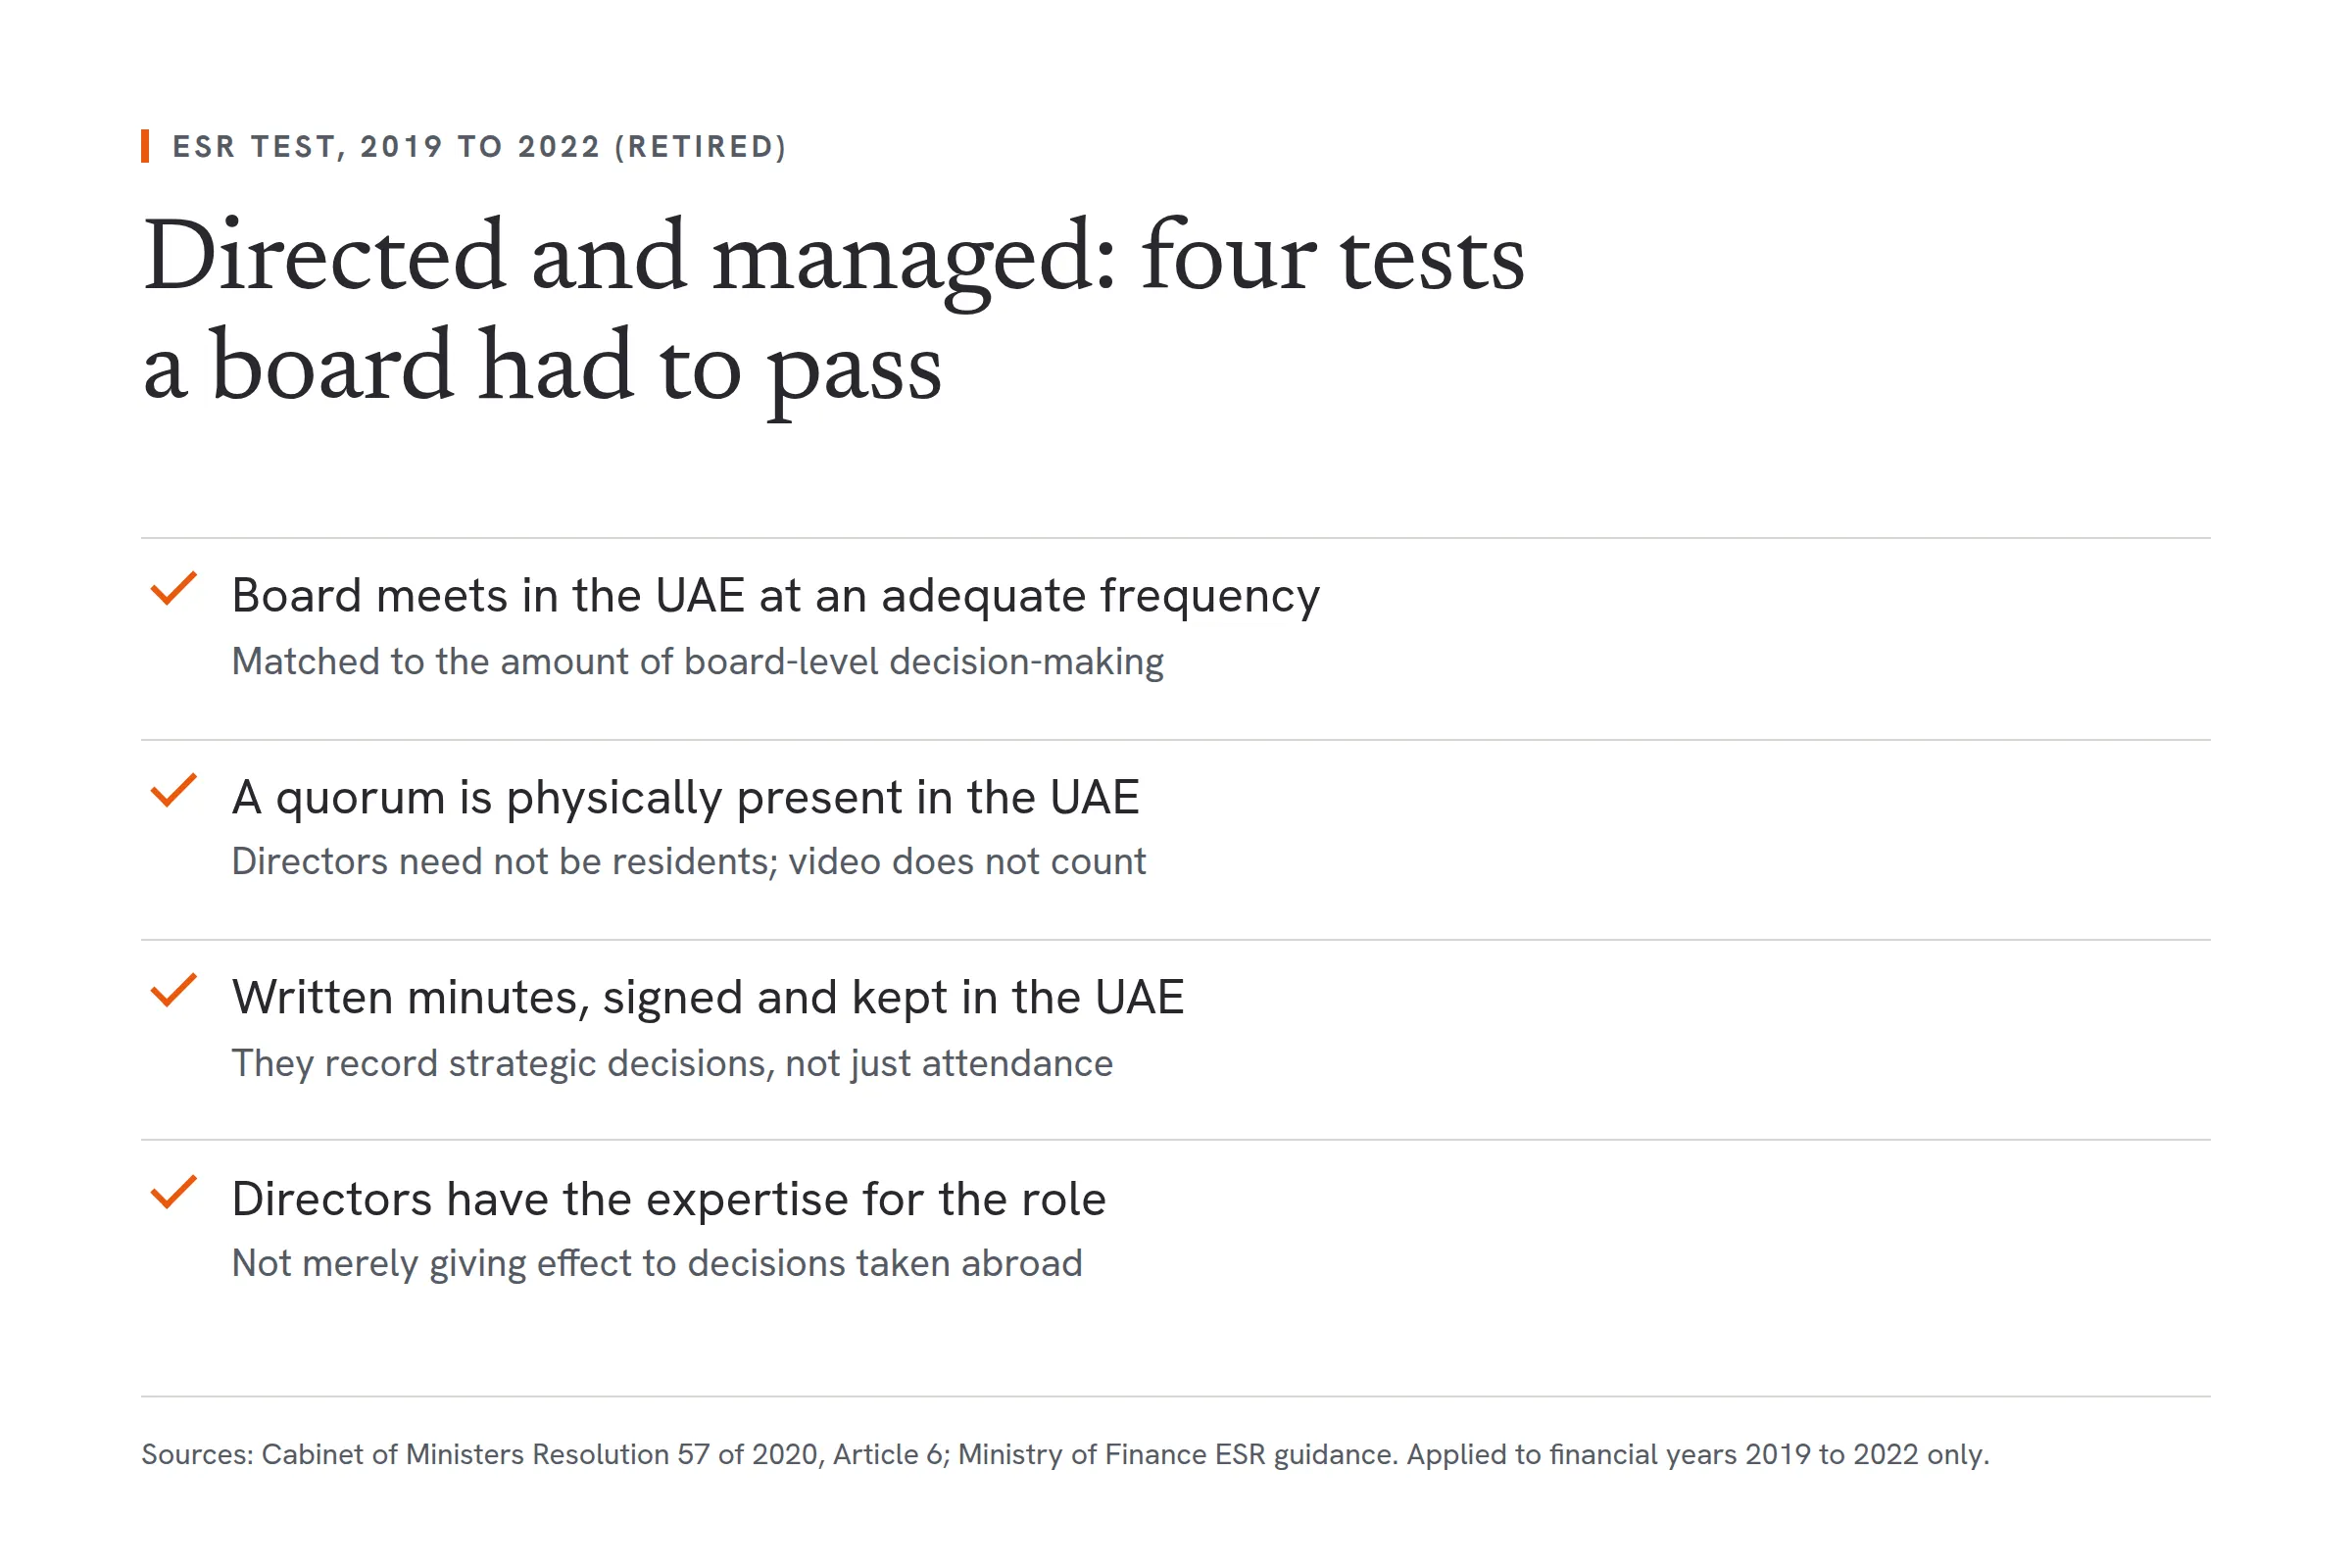
If your board is nominally present but decisions are actually made by foreign parents or shareholders, you lack economic substance. The test required that directors have the knowledge and expertise to discharge the board's duties, and directors not merely giving effect to decisions taken outside the UAE.
No meaningful employees
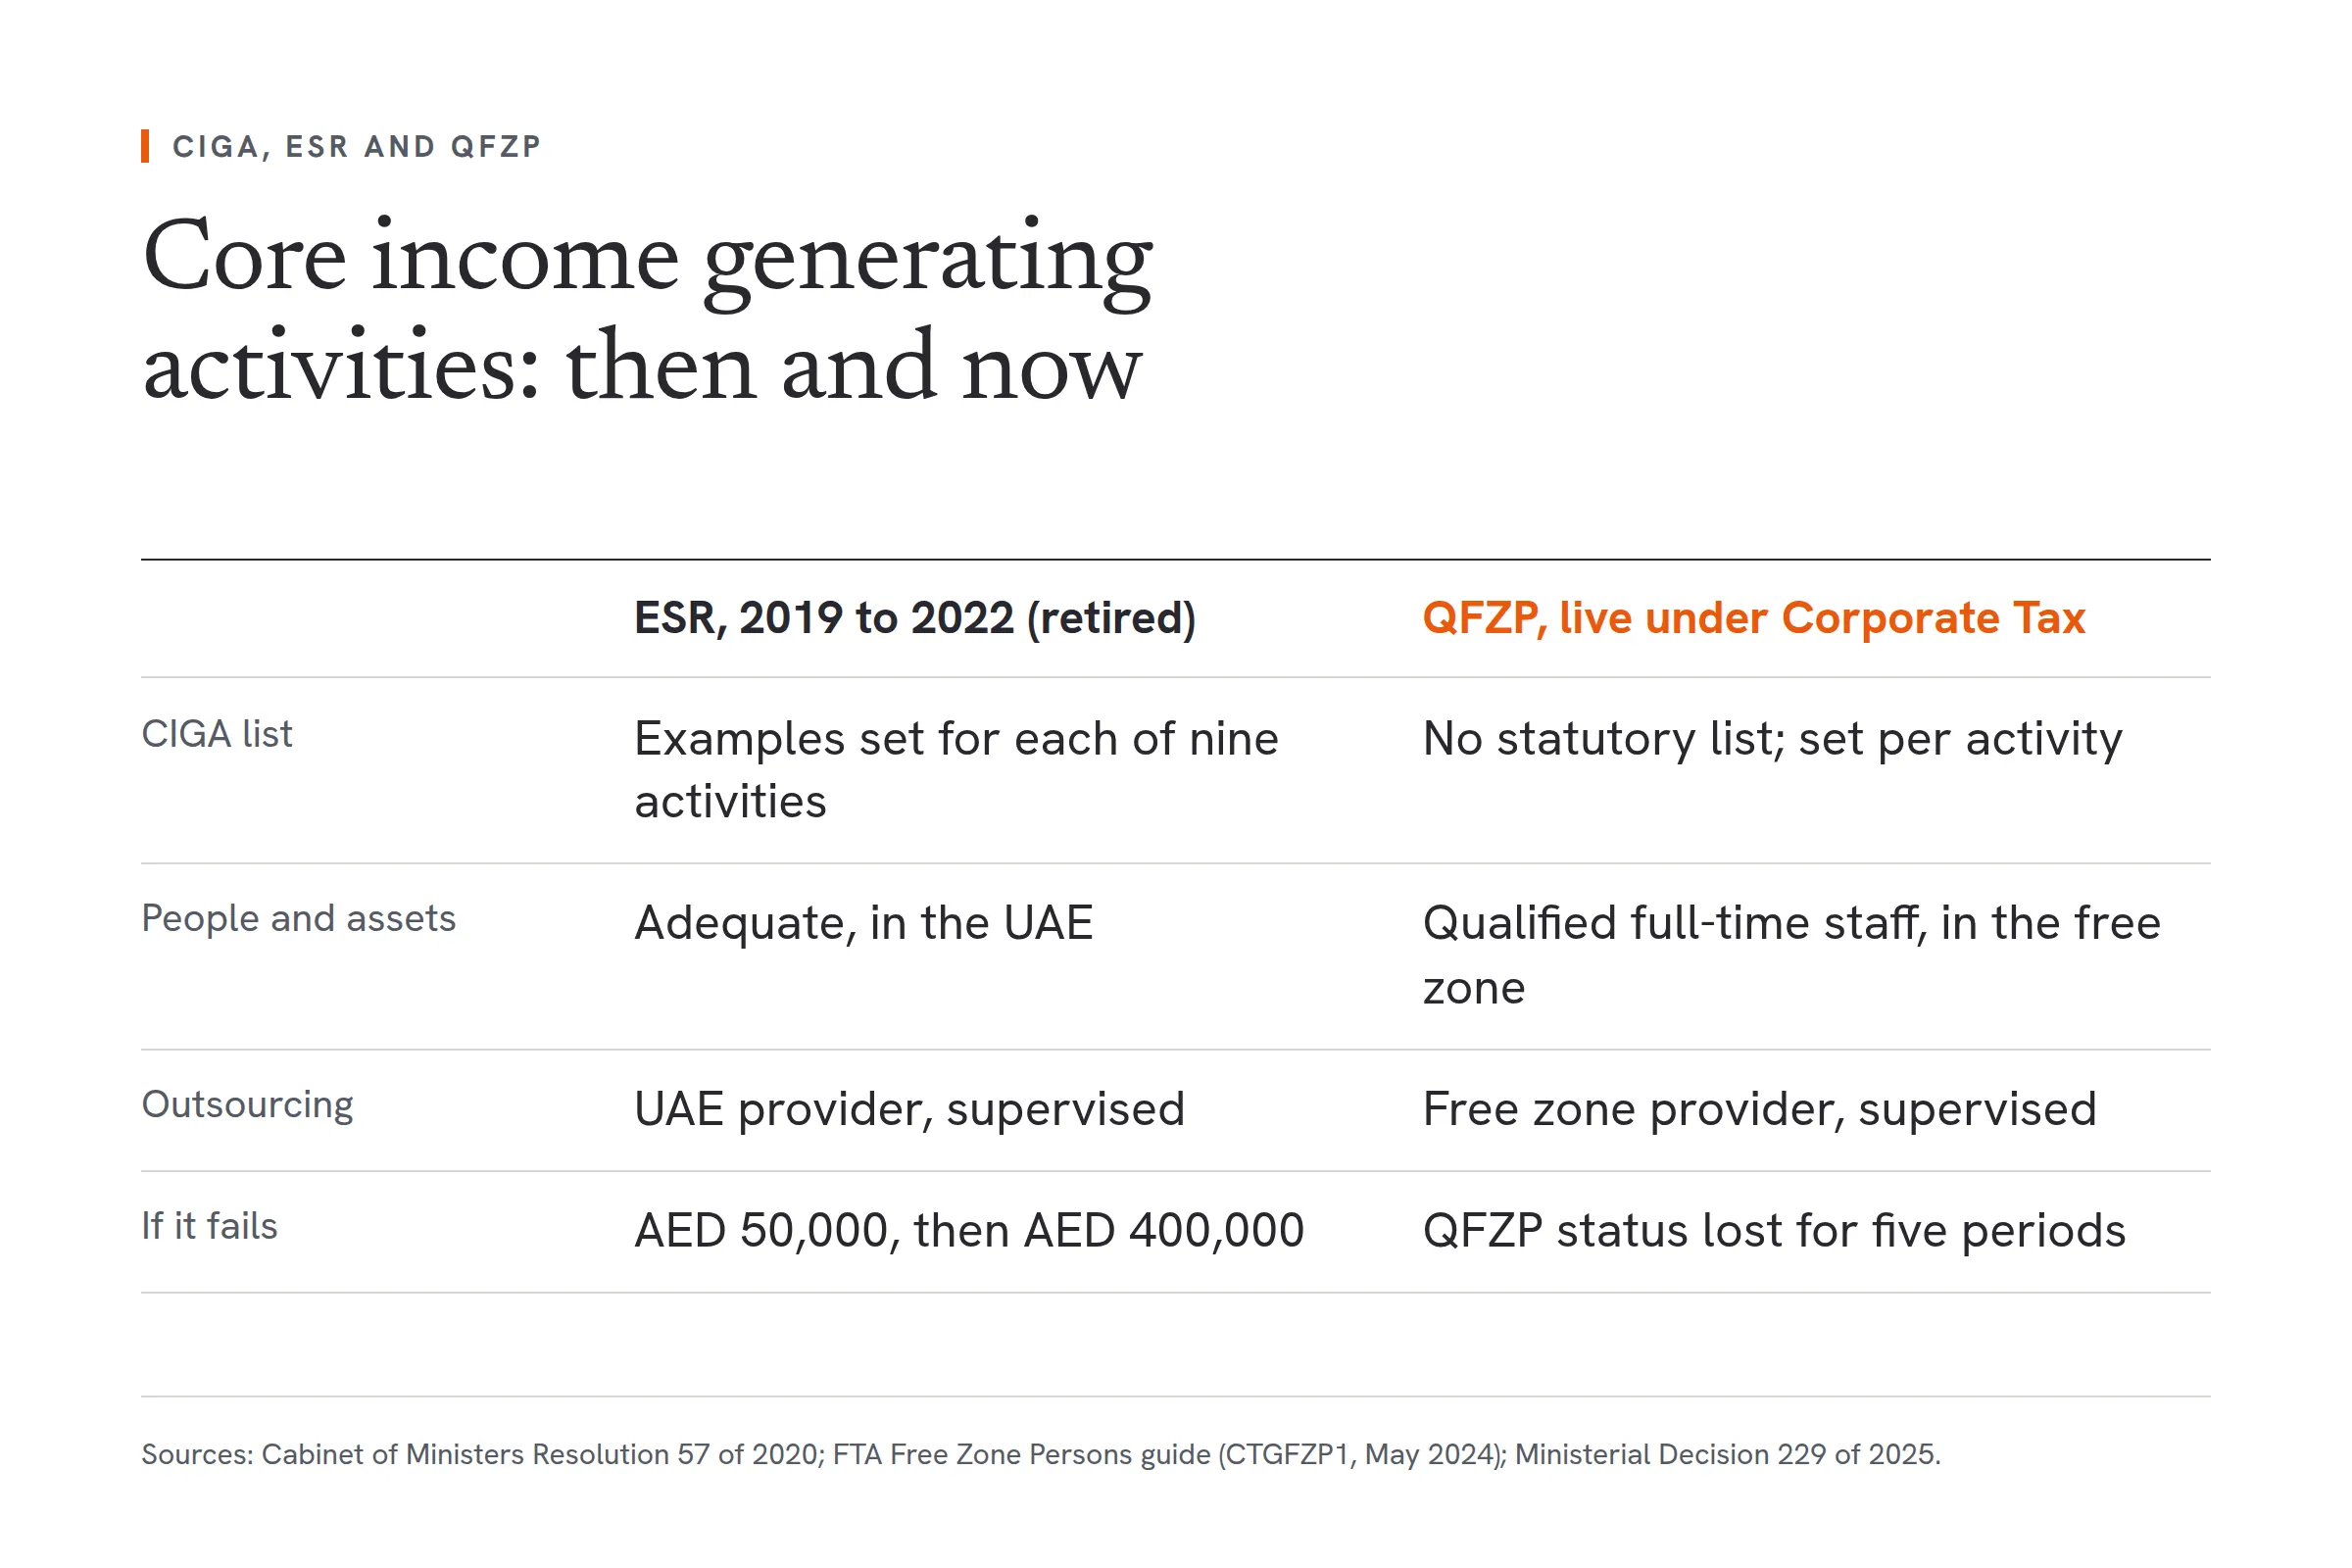
A business cannot have economic substance if all staff are purely administrative, or outsourced without supervision. The test looked for an adequate number of qualified full-time employees in the UAE, and for core income-generating activities carried out here.
Inconsistent activity
Say your business claims to be an import trader but has no invoices, no supplier relationships, no inventory management and no matching payment records. That is a red flag. Activity should be consistent with your stated business purpose.
Mismatched substance and structure
A holding company that does more than hold shares and receive dividends, but has no investment committee or portfolio monitoring, does not satisfy the full test. It does not matter where it is incorporated.
How to build and defend substance compliance
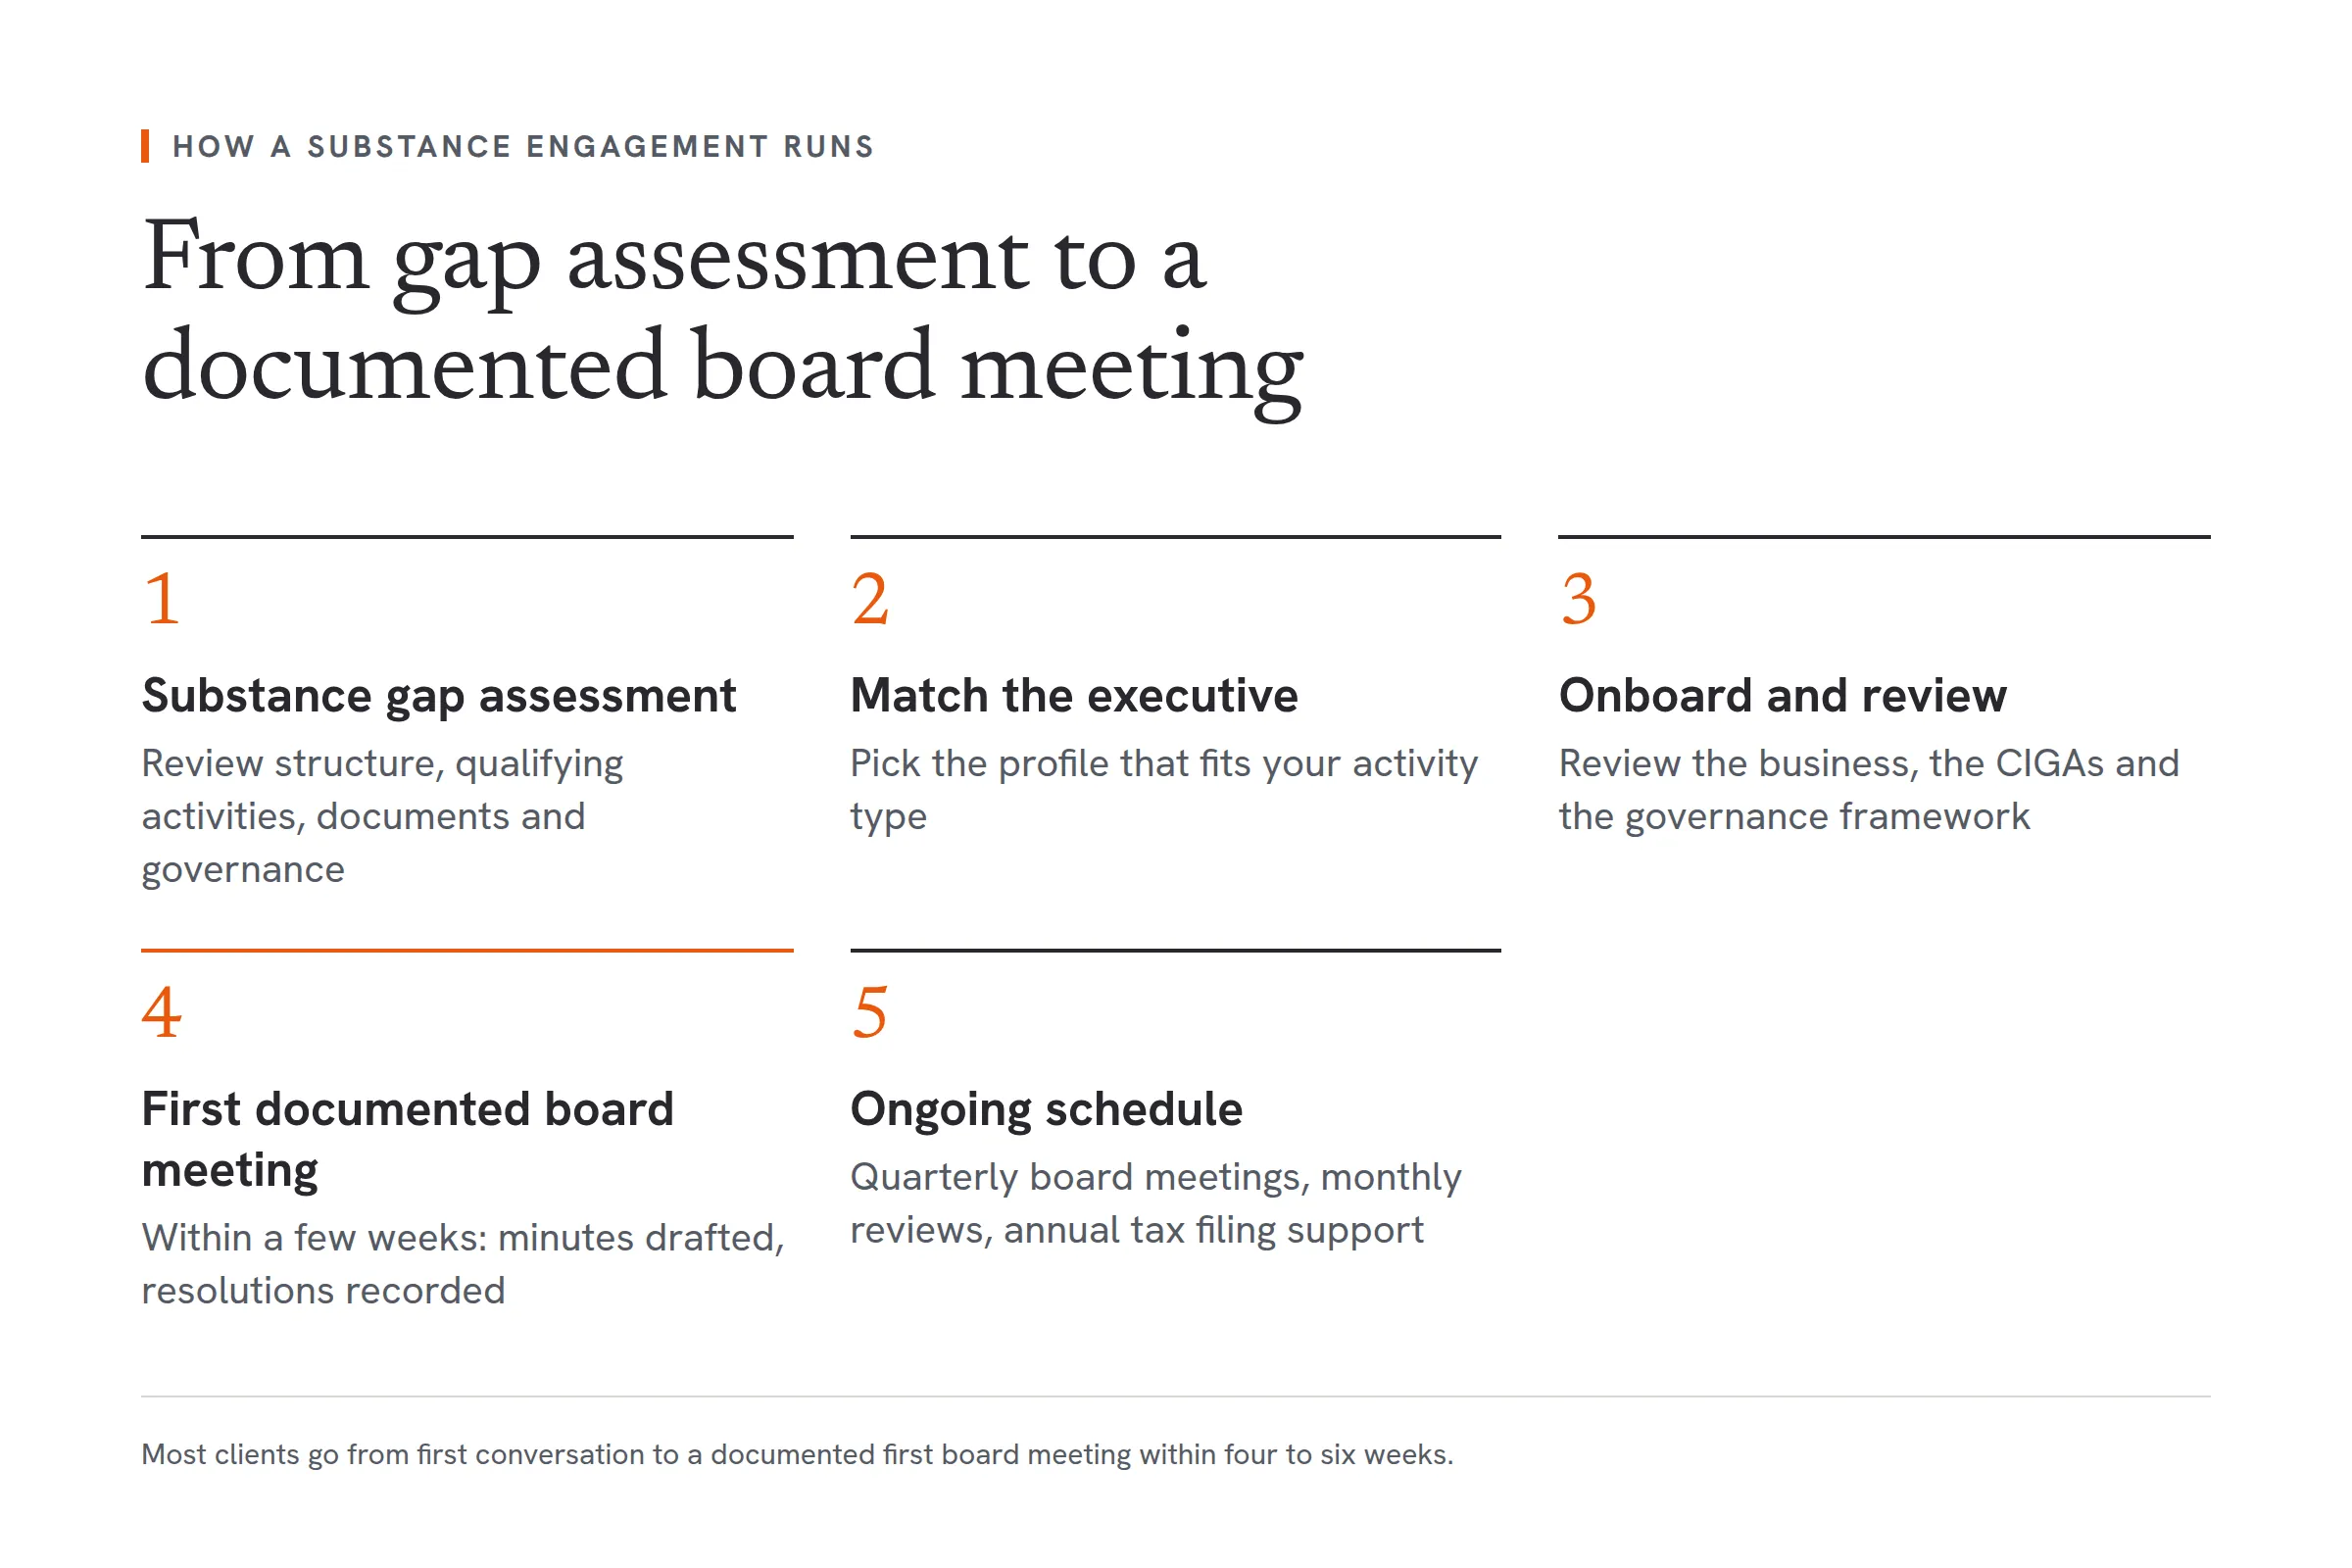
We recommend a three-step framework. It works equally for the QFZP substance condition today.
Step 1: Audit your current state
Review what documentation you actually have. Can you show that your business made autonomous decisions? Do you have contemporaneous meeting minutes? Employee records that match your claimed activities? Bank records that align with your business narrative? A review from an external perspective often reveals gaps before a regulator does.
Step 2: Close documentation gaps
This is proactive work, not reactive. Put systems in place to create and retain evidence of:
- Regular board or management meetings with documented decisions
- Formal policies for finance, compliance and operations
- Clear delegation of authority and decision-making processes
- Records of substantive activities tied to your business purpose
- Evidence of key employee involvement in meaningful decisions
Step 3: Align substance with structure
If you claim to be a regional service provider but lack regional staff, that is misaligned. If you are a holding company but have no investment committee or portfolio monitoring, that is misaligned. Structure and substance must match.
For some businesses, this means engaging a fractional Chief Financial Officer (CFO) or Chief Operating Officer (COO) to provide the strategic oversight and governance that smaller teams struggle to maintain. Others use our free zone substance and tax service to anchor substance and board governance. The right approach depends on your situation.
The role of fractional executives in substance compliance
Businesses caught by ESR failures often had gaps in financial and operational oversight. How a fractional executive supports genuine substance covers the documentation and governance model in detail. A fractional CFO can:
- Assess compliance risk specific to your business model
- Design and implement governance structures that satisfy FTA expectations
- Establish documentation protocols and reporting processes
- Review related-party transactions and ensure they are properly substantiated
- Prepare for and support FTA reviews
- Monitor regulatory changes and advise on implications for your business
A fractional CFO or COO is not a cost centre in this context. They are insurance against an exposure that could run to hundreds of thousands of dirhams, or to the loss of a 0% rate. For SMEs without in-house tax or governance expertise, that model often closes the gap faster than recruiting a full-time executive. It does not remove the need for the full-time employees that the QFZP test looks for in the free zone.
What happened if you received an ESR notice
If a penalty notice was issued, the licensee had options:
- Gather your documentation: Collect everything that demonstrates economic substance for the year in question.
- Be honest about gaps: If records are missing, acknowledge it. Fabricating evidence is far worse than having incomplete documentation.
- Provide context: Explain your business model, decision-making process and substantive activities in writing.
- Consider professional support: A tax adviser or specialist can help you present your case effectively.
A licensee could appeal on three grounds: that it did not commit the violation, that the penalty was disproportionate, or that it exceeded the prescribed limits. If an appeal was lodged, payment fell due when the appeal was finally determined or withdrawn. A penalty could not be imposed more than six years after the violation, unless fraud prevented the FTA from acting sooner.
Key takeaways
ESR penalties were real. They were applied to businesses that failed to maintain adequate economic substance and documentation. They no longer accrue for new periods: Cabinet Decision 98 of 2024 ended ESR for financial years ending after 31 December 2022 and cancelled the penalties levied for those periods. What carried forward is the substance question itself, now attached to Qualifying Free Zone Person status under Corporate Tax.
The exposure has changed shape rather than disappeared. Under Ministerial Decision 229 of 2025, a free zone person that fails any QFZP condition ceases to be a QFZP from the beginning of the tax period and for the following four tax periods. That is a loss of the 0% rate on qualifying income, not a fixed fine. For a business with meaningful revenue, it can cost far more than AED 400,000.
The practical path is straightforward. Understand what economic substance means for your business. Put in the governance and documentation that proves you have it. Keep that evidence up, consistently. For many businesses this takes no significant operational change, only a deliberate approach to documentation and decision-making.
For more on how economic substance was evaluated in the UAE, read our detailed guide to the economic substance test, see how substance applies to your specific business activity, or review what directed and managed actually requires.
If you are unsure about your current position, take our economic substance readiness assessment, or get in touch with us to assess risk, close gaps and build governance that withstands FTA scrutiny.