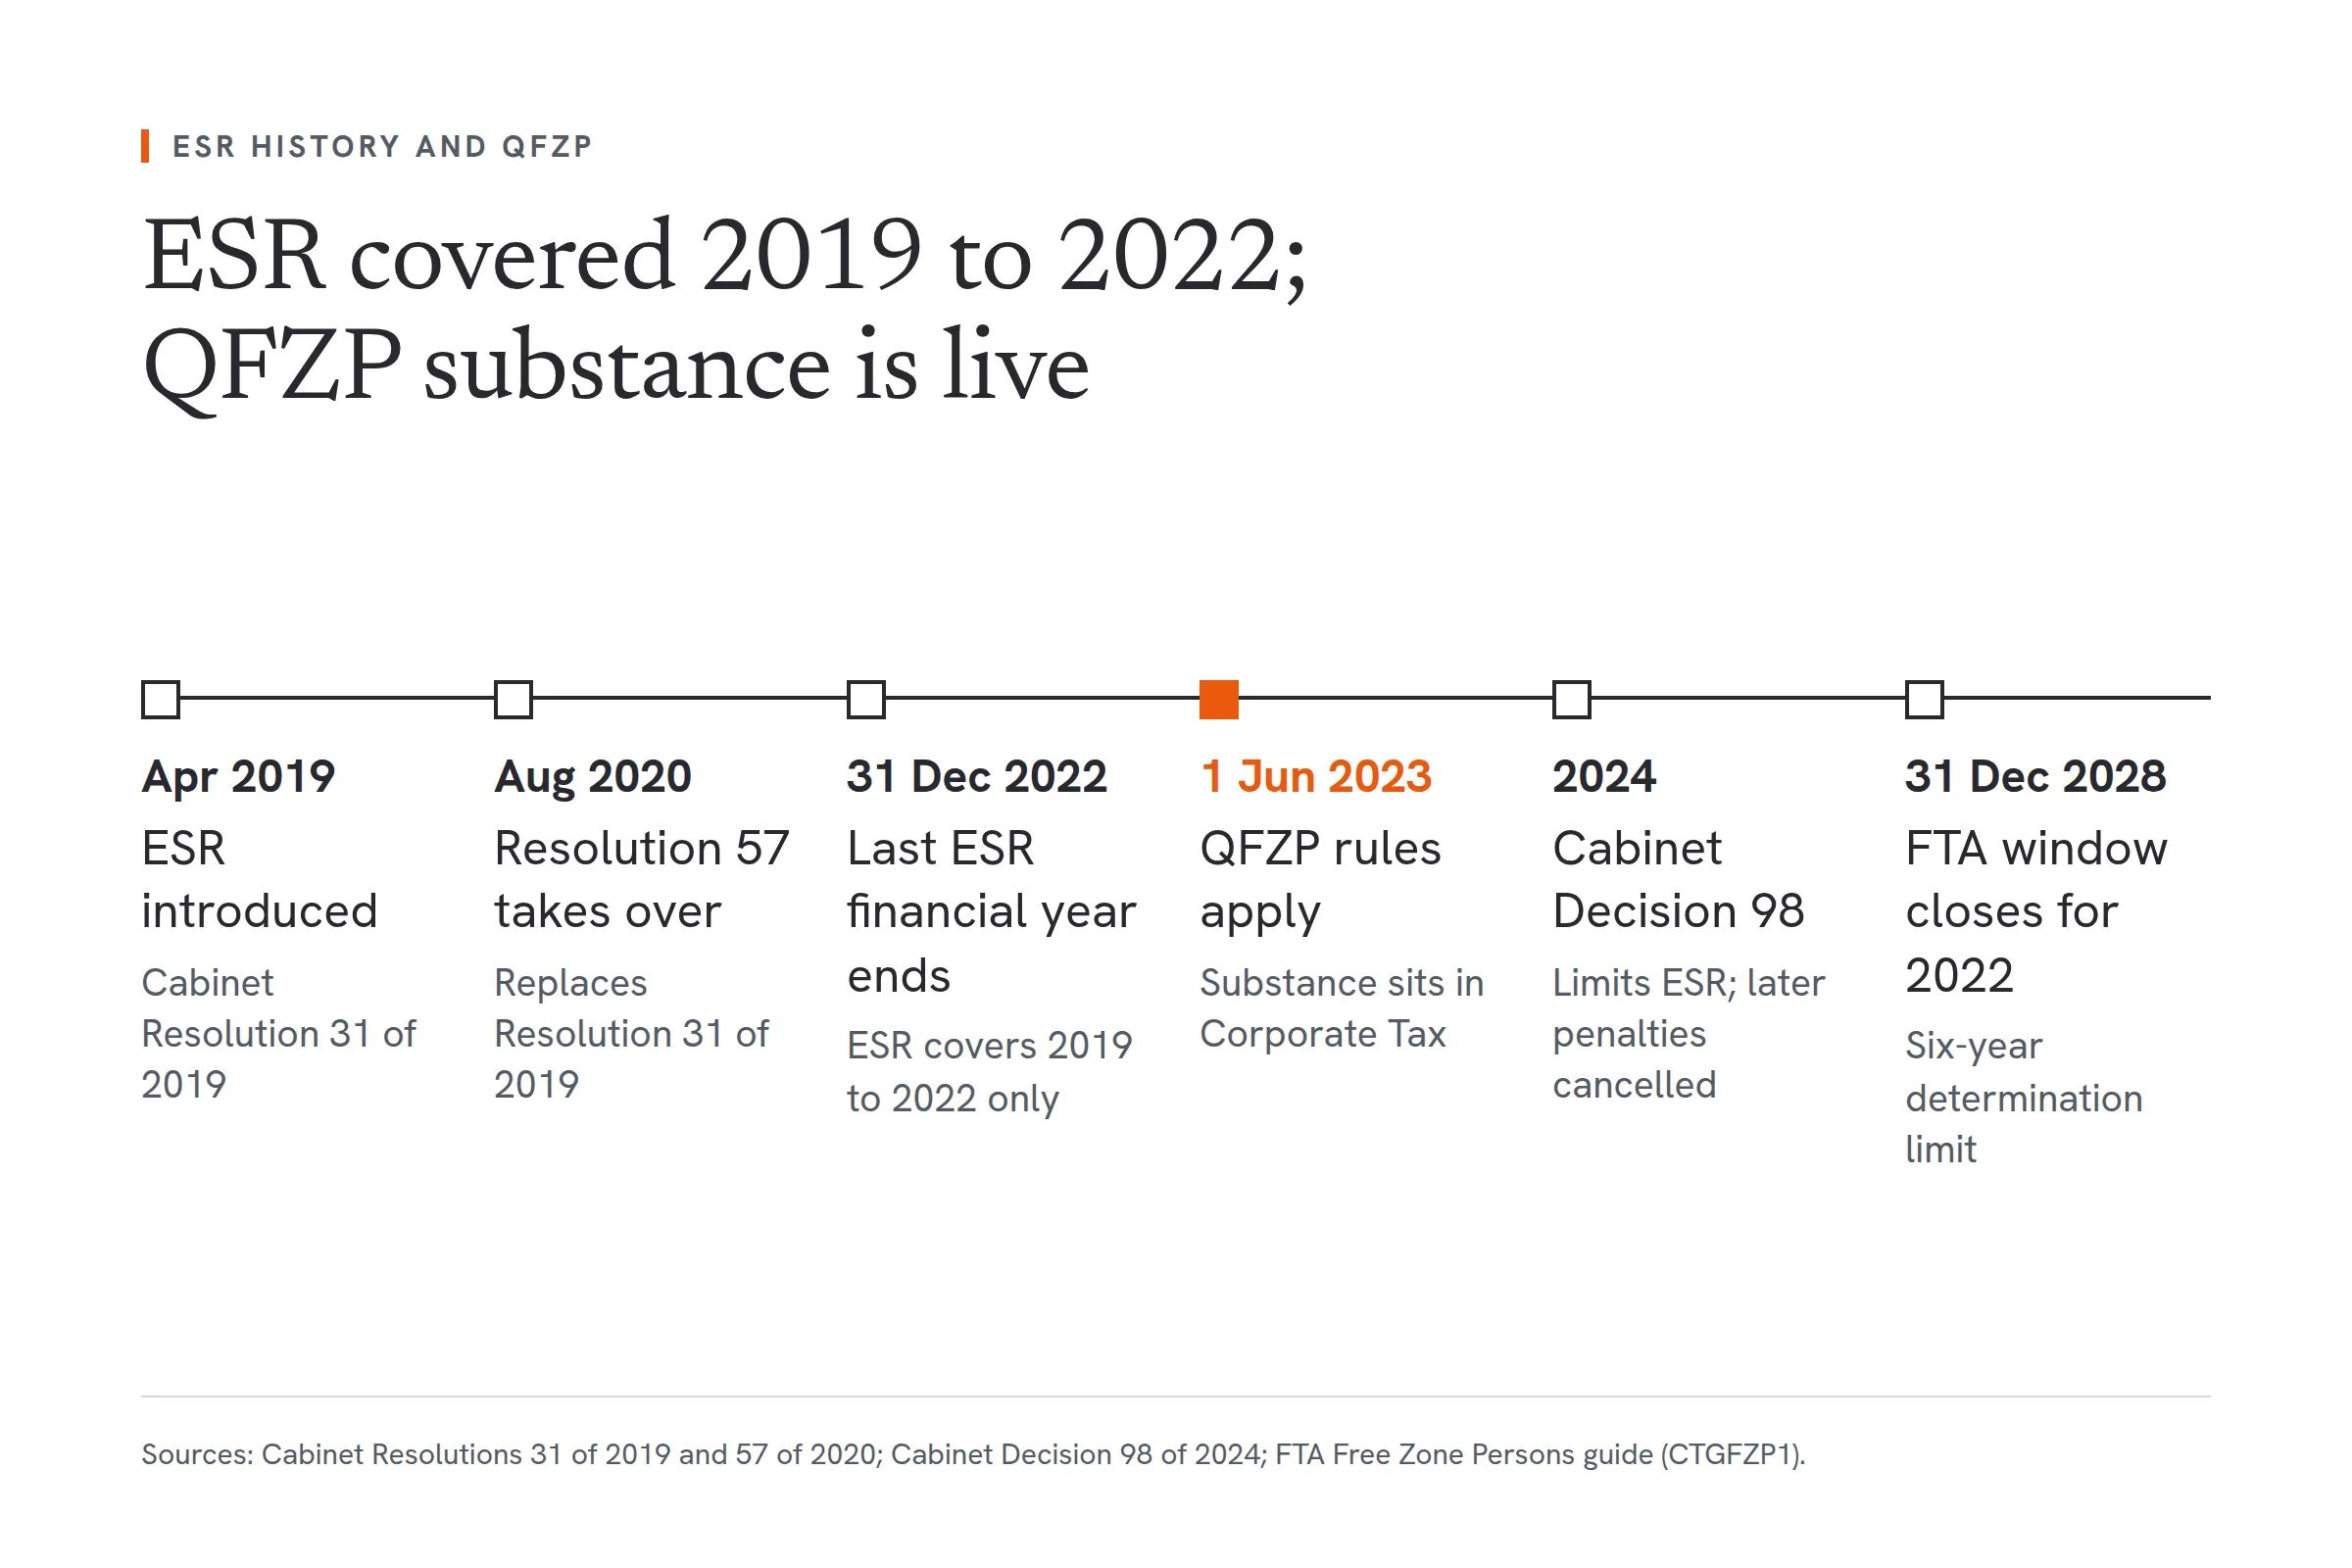
Update, September 2026. The UAE Economic Substance Regulations have been retired. Cabinet Decision 98 of 2024 amended Cabinet Decision 57 of 2020 so that ESR applies only to financial years from 1 January 2019 to 31 December 2022. For any financial year ending after 31 December 2022 there is no ESR notification, no ESR report and no penalty exposure. Penalties already levied for those later periods were cancelled, and amounts already paid are refunded by the Federal Tax Authority. This article is kept as a historical explainer of the regime as it applied to 2019 to 2022. If you run a free zone business today, the live question is the adequate-substance condition attached to Qualifying Free Zone Person status under UAE Corporate Tax.
In short: A core income generating activity (CIGA) is an activity of central importance to how a business earns its income. Under the Economic Substance Regulations (ESR), CIGAs listed for each of the nine relevant activities had to be carried on in the UAE, and the same idea now sits at the heart of the free zone substance condition under Corporate Tax.
A core income generating activity (CIGA) is an activity of central importance to how a business earns its income. Under the ESR, Article 3 of Cabinet of Ministers Resolution 57 of 2020 listed example CIGAs for each of the nine relevant activities. They had to be carried on in the UAE. The same idea now sits at the heart of the free zone substance condition under corporate tax.
Most businesses knew economic substance mattered. Far fewer knew which activities had to physically happen here. CIGAs were those activities. They had to be performed in the UAE for a business to pass the full economic substance test. Get them wrong and no amount of office space or UAE-resident directors would save you.
Here is a plain account of what CIGA meant across the nine relevant activity categories for 2019 to 2022, and why the concept still matters under corporate tax.
What CIGAs are and why they are the core of the test
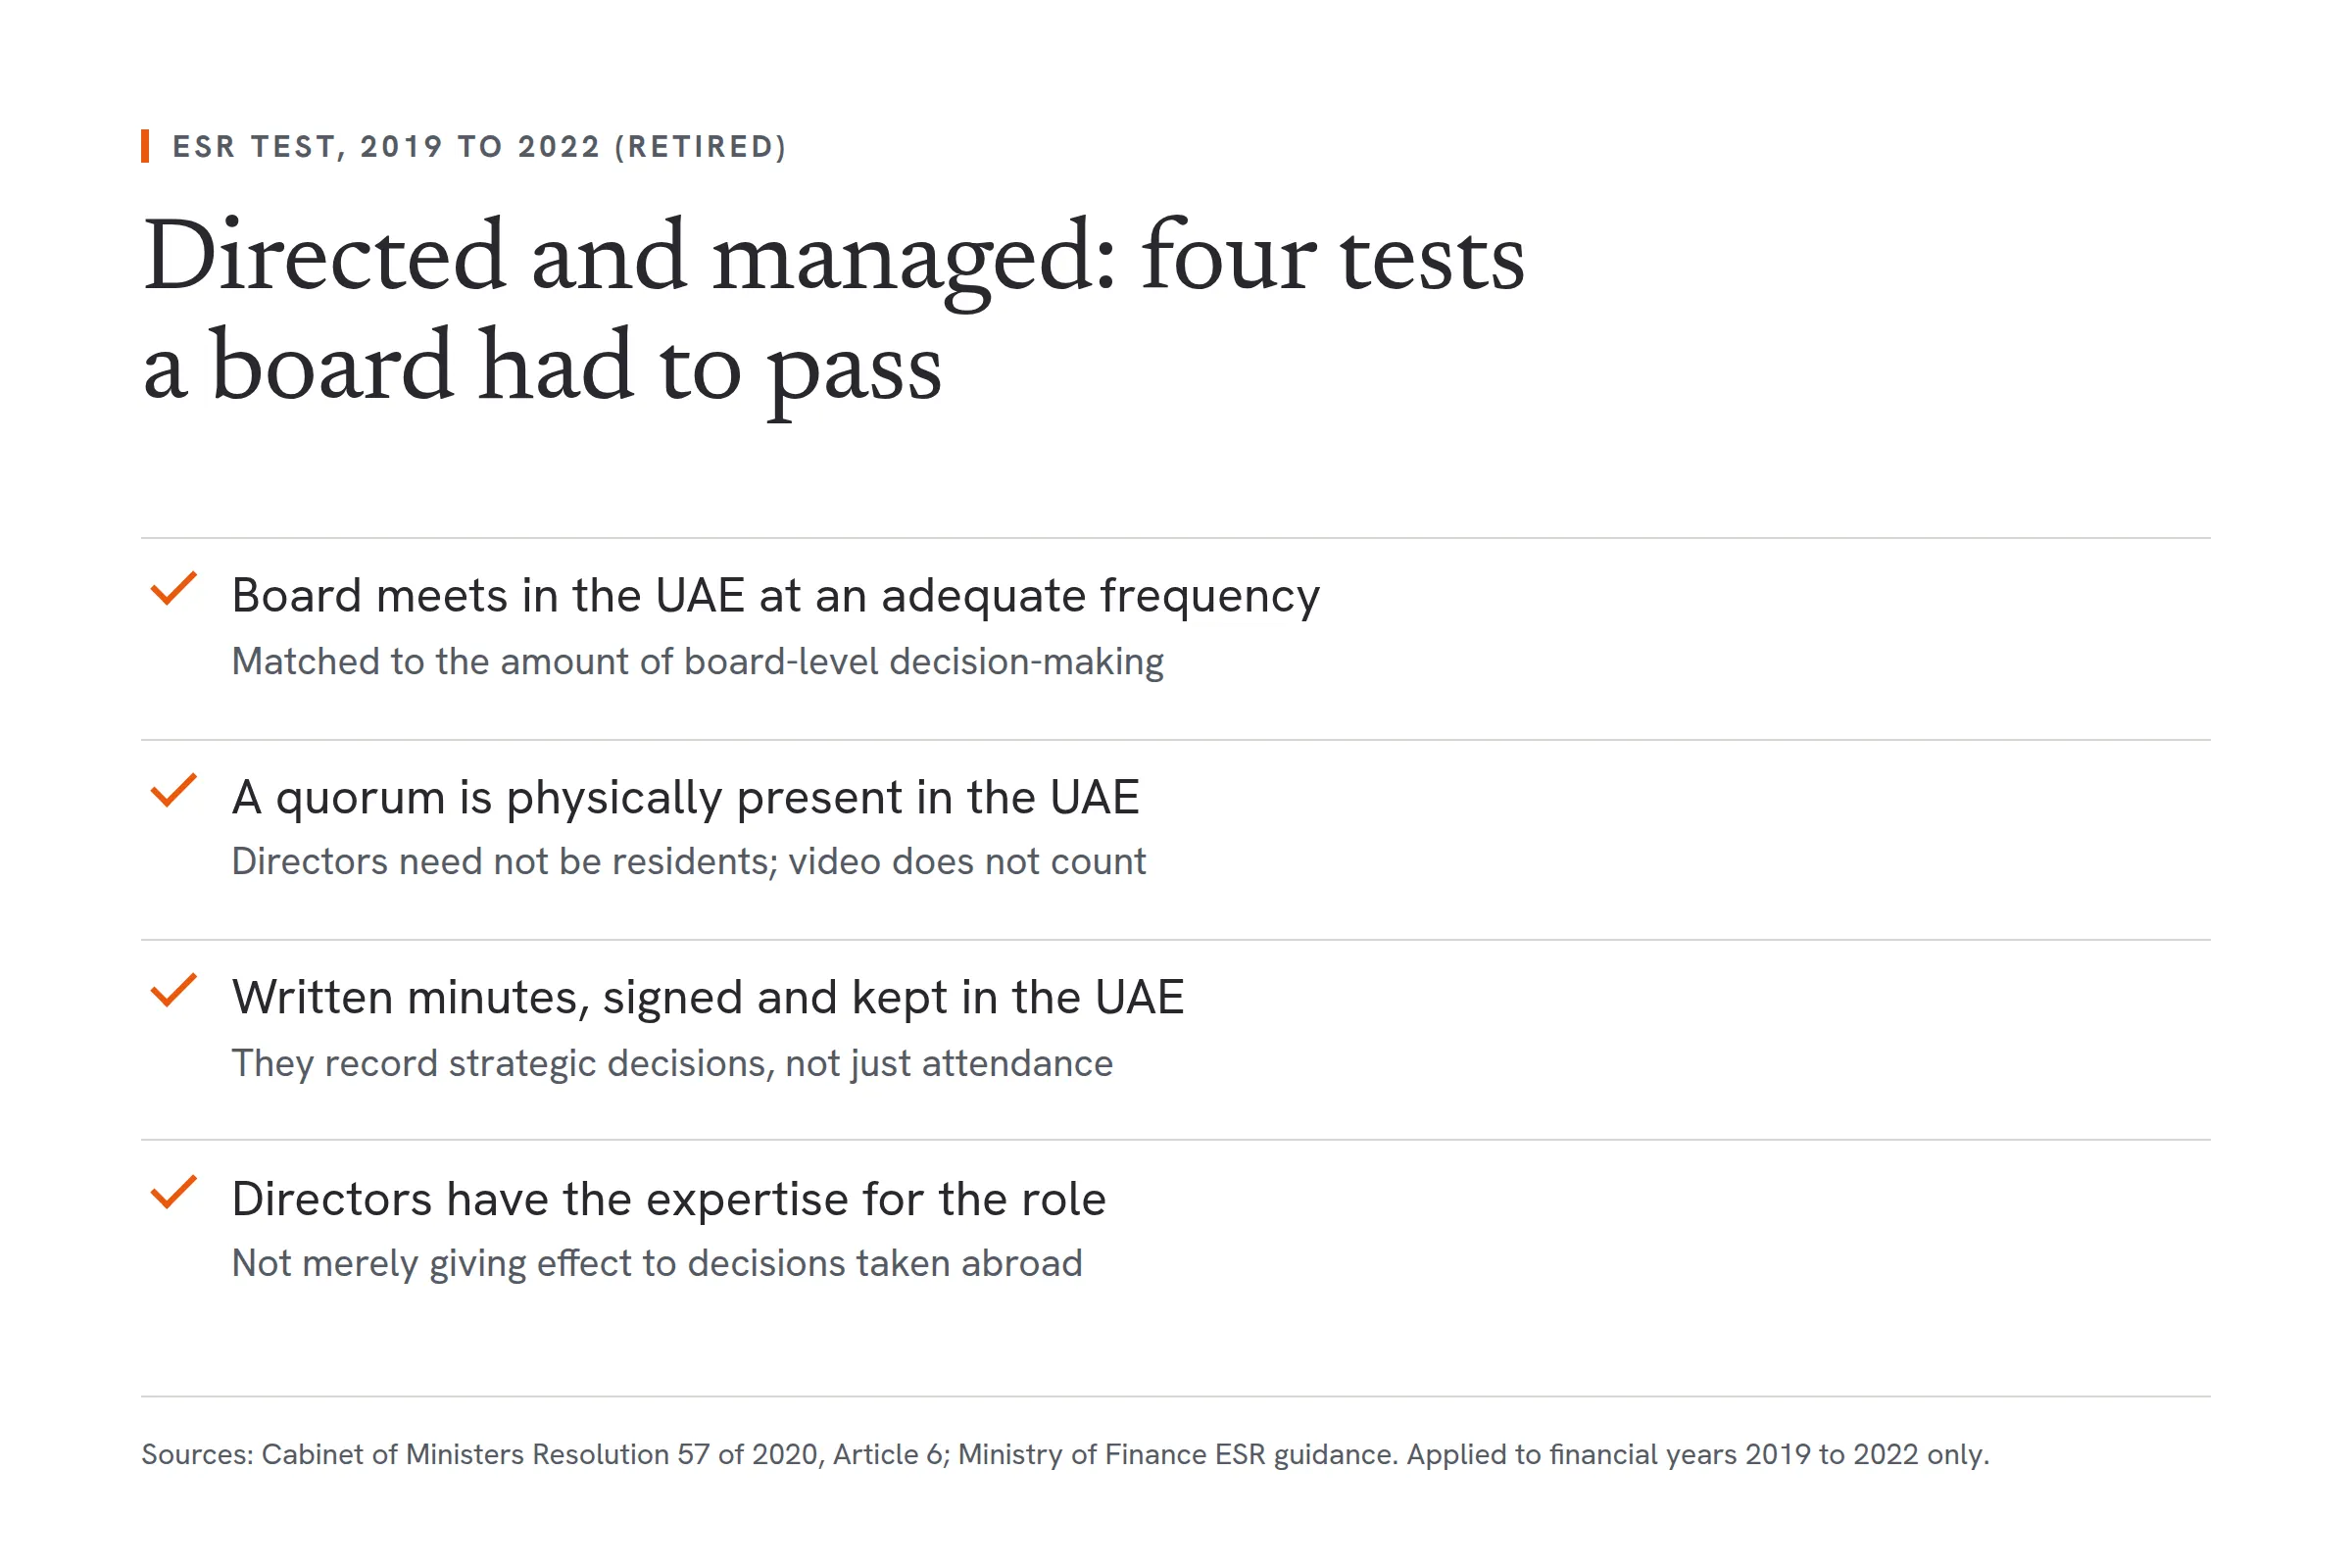
The ESR test had three parts: the relevant activity had to be directed and managed in the UAE, the CIGAs had to be conducted in the UAE, and the licensee needed adequate employees, operating expenditure and physical assets here. In practice the CIGA limb was often the hardest to evidence.
CIGAs are the activities that actually generate your income. Not the support functions. Not the admin. The substantive, value-creating work that explains why a customer or counterparty pays you. The test asked one thing. Is that work happening in the UAE, or somewhere else while you keep a UAE address for convenience?
The Ministry of Finance's guidance was clear that the lists in the Resolution are examples, neither exhaustive nor mandatory. A licensee did not have to perform every listed activity. It did have to perform in the UAE the CIGAs that generated its relevant income. Activities that were not CIGAs could happen outside the UAE.
The principle: CIGAs must be performed in the UAE
The requirement was straightforward. CIGAs had to be conducted in the UAE by qualified personnel who were physically present here. The people doing the real work needed to operate from UAE soil, whether employed directly by the entity or through an outsourcing arrangement.
There was no shortcut. You could not direct CIGAs from abroad and claim they were performed in the UAE. The directed and managed requirement reinforced this. Strategic decisions about the relevant activity also had to be made here, typically in board meetings held in the UAE with a quorum of directors physically present.
Each relevant activity had its own CIGA list. What counted for a shipping company was completely different from what counted for an IP business. Check your actual activity, not just the category on your trade licence.
CIGA breakdown by relevant activity
The table below summarises the example CIGAs in Article 3(2) of Resolution 57 of 2020, which applied to financial years 2019 to 2022.
Relevant Activity | Example Core Income Generating Activities (CIGAs) |
|---|---|
Banking | Raising funds and managing risk (credit, currency, interest); taking hedging positions; providing loans, credit or other financial services to customers; managing capital and preparing reports to investors or regulators |
Insurance | Predicting and calculating risk; insuring or reinsuring against risk and providing insurance services to clients; underwriting insurance and reinsurance |
Investment Fund Management | Taking decisions on the holding and selling of investments; calculating risk and reserves; taking decisions on currency or interest fluctuations and hedging positions; preparing reports to investors or regulators |
Lease-Finance | Agreeing funding terms; identifying and acquiring assets to be leased; setting the terms and duration of financing or leasing; monitoring and revising agreements; managing risks |
Headquarters | Taking relevant management decisions; incurring operating expenditure on behalf of the group; coordinating group activities |
Shipping | Managing crew, including hiring, paying and overseeing them; overhauling and maintaining ships; overseeing and tracking shipping; determining what goods to order and when to deliver them, and organising and overseeing voyages |
Holding Company | All activities related to the holding business, which was subject to a reduced test (see below) |
Intellectual Property | Research and development where the asset is a patent or similar; branding, marketing and distribution where the asset is a marketing intangible; in exceptional cases, strategic decisions and management of the principal risks of developing or exploiting the asset |
Distribution and Service Centre | Transporting and storing component parts, materials or goods ready for sale; managing inventories; taking orders; providing consulting or other administrative services |
Two things stand out in this table. First, holding companies sat in a special position. A business whose sole function was holding shares, and which only earned dividends and capital gains, met the test by complying with its filing obligations and having adequate employees and premises for holding and managing the business. It was not required to be directed and managed in the UAE unless its licensing authority said so. The moment an entity earned other income, it was tested as a full-substance business.
Second, the IP category was the most prescriptive. The right CIGA depended on whether the asset was a patent-type asset or a marketing intangible. "High risk" IP licensees faced a presumption of failure unless they could prove otherwise.
The outsourcing rule
A business did not have to perform CIGAs using its own employees. Outsourcing was permitted, but the rules were strict. Misunderstanding them was one of the more common compliance failures.
To outsource CIGAs validly, Article 6(2) of Resolution 57 required four things.
- The licensee had to be able to monitor, control and demonstrate adequate supervision in the UAE of the outsourced activity.
- The provider's employees, expenditure and assets had to be adequate for the work.
- The CIGAs had to be carried out in the UAE. Routing them through an overseas provider and billing back to a UAE entity did not satisfy the test.
- The same resources could not be counted by multiple licensees. If a provider's employee spent an hour on one licensee's CIGAs, that hour could not count for another.
Documentation mattered. Board minutes, correspondence with the service provider, oversight reports and signed-off deliverables all formed part of the audit trail. Without them, an assessor could read outsourced CIGAs as never performed in the UAE at all.
How the CIGA test connects to the QFZP substance test
Cabinet Decision 98 of 2024 limited the ESR to financial years from 1 January 2019 to 31 December 2022, and penalties for later periods were cancelled and refunded. For the 2019 to 2022 window the obligations remain. Under Article 7 of Resolution 57 the FTA may determine a failure up to six years after the end of the financial year, so the window for 2019 closed on 31 December 2025, and the window for 2022 stays open until 31 December 2028 (longer where there was fraud or gross negligence).
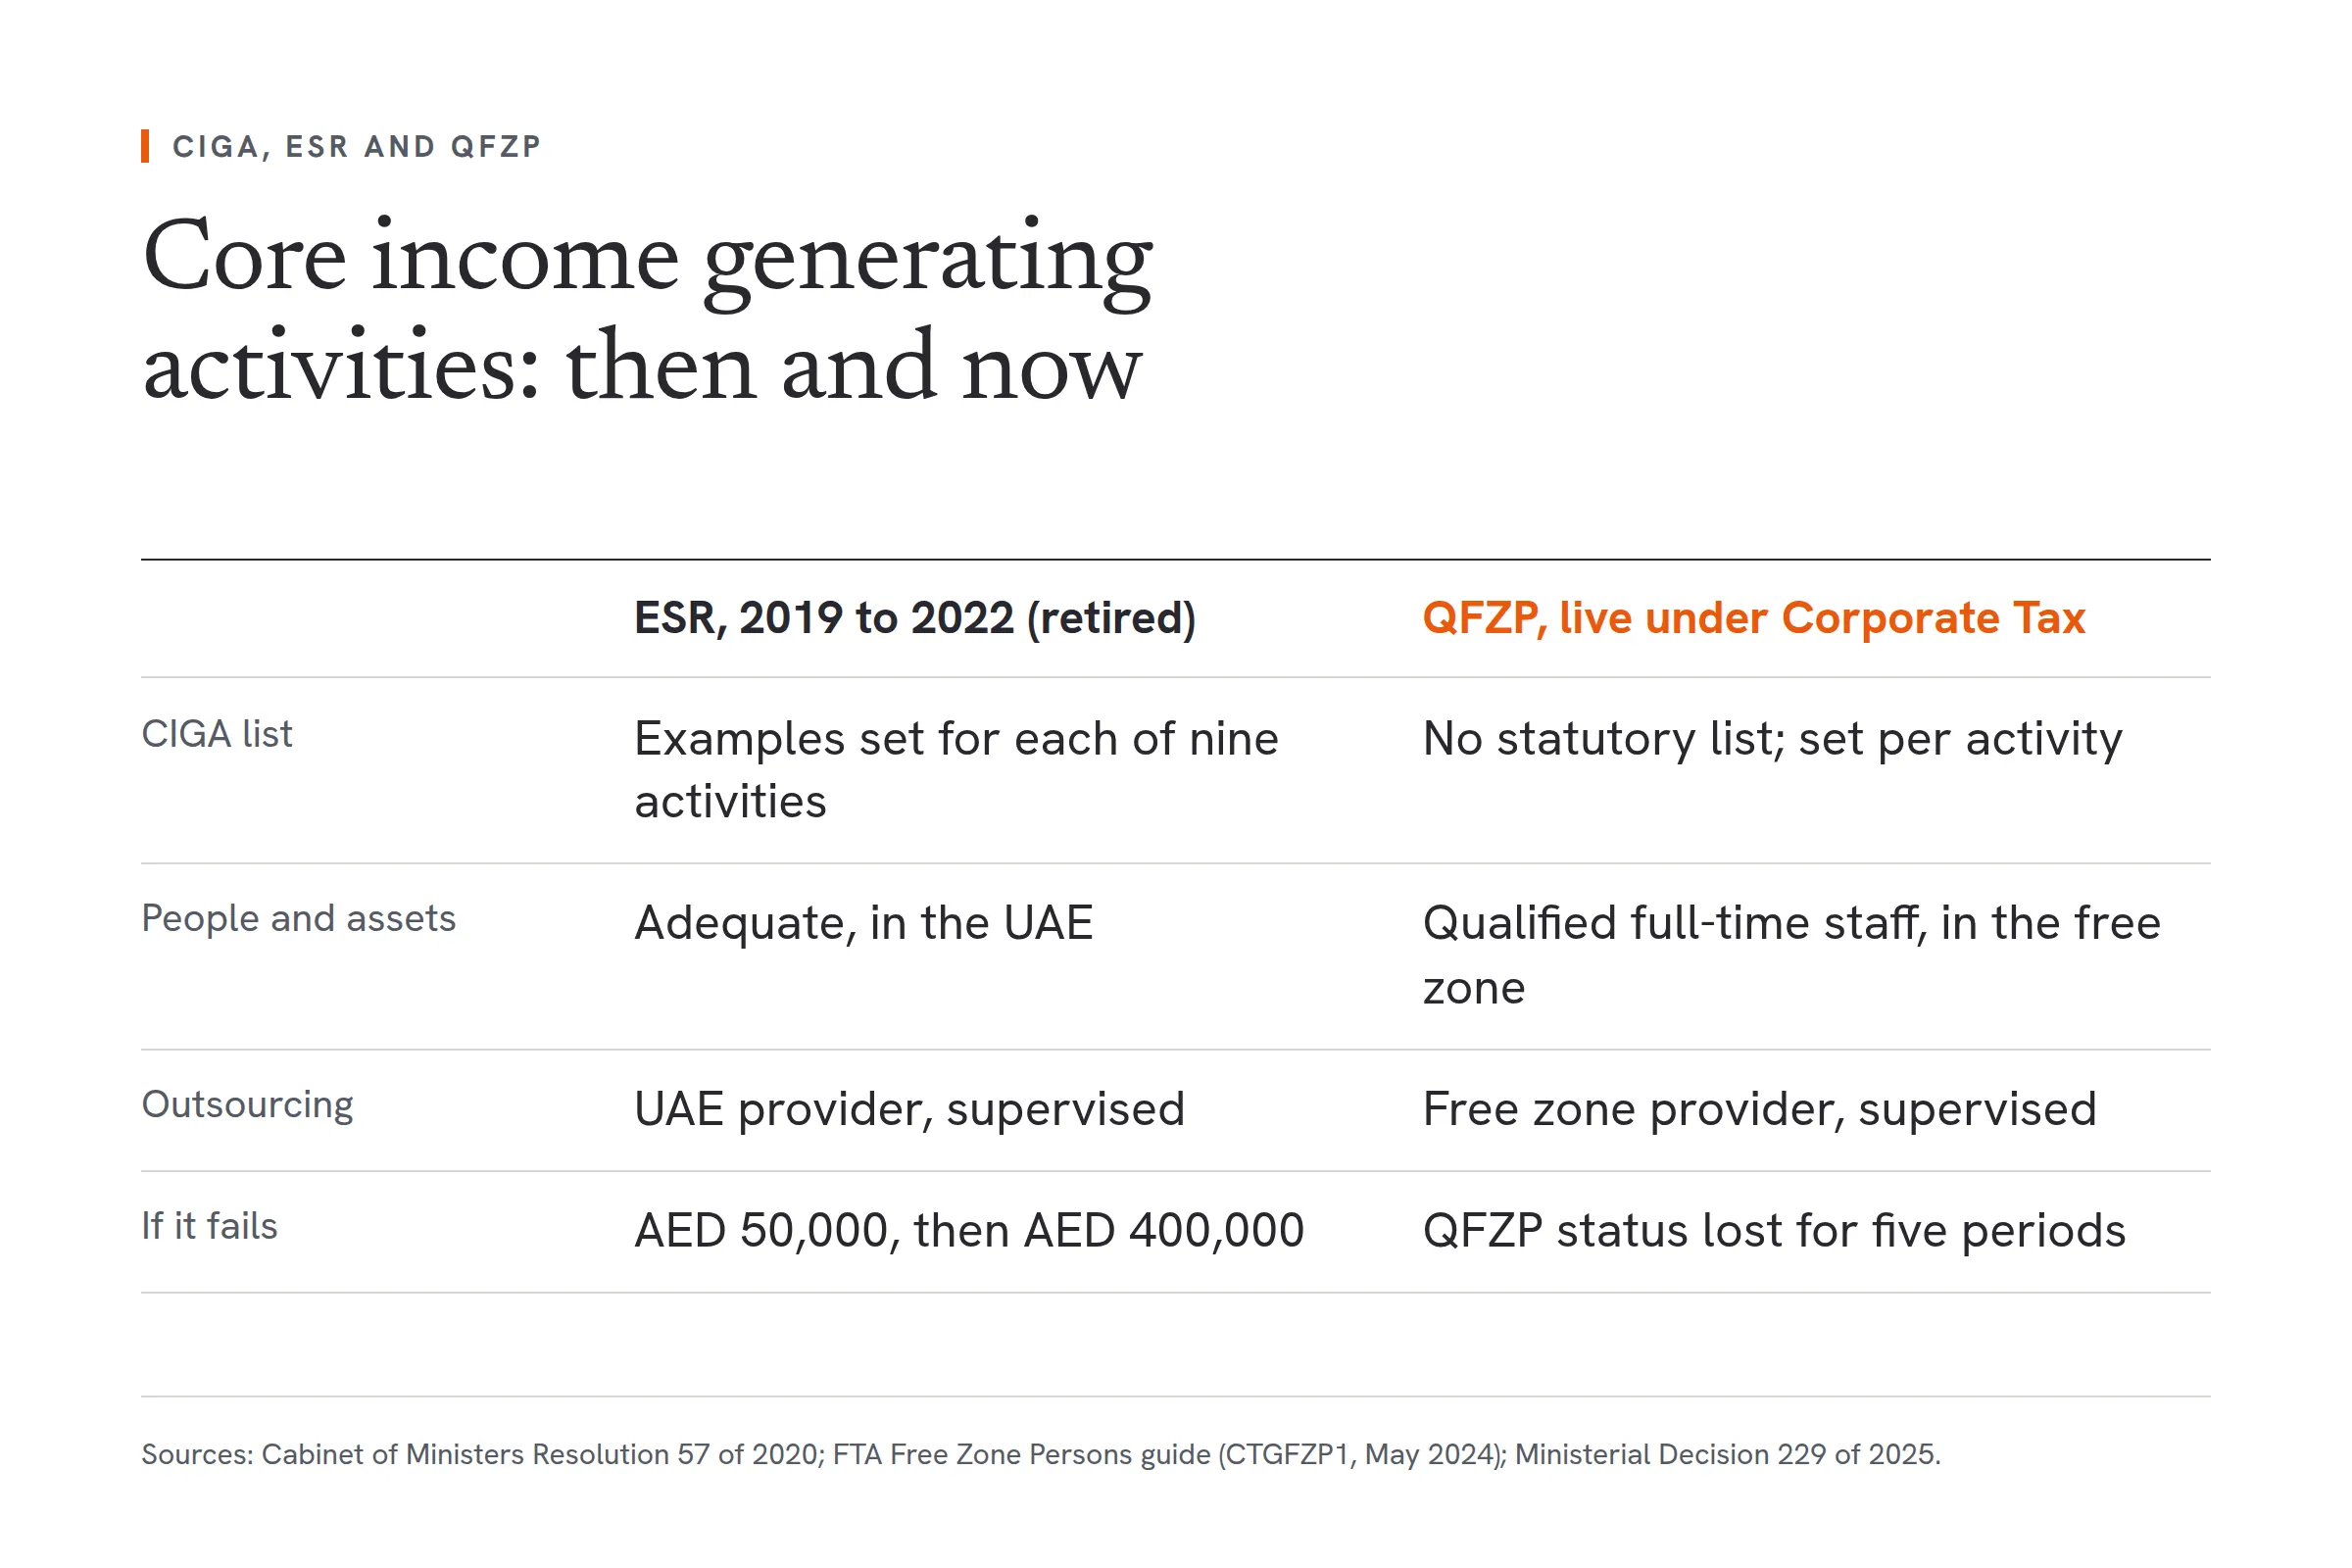
But the question of whether CIGAs are performed in the UAE did not disappear when the ESR filing requirement ended. It moved. A free zone business that wants the 0% rate as a Qualifying Free Zone Person (QFZP) must maintain adequate substance in a free zone. It must undertake its core income-generating activities there, with adequate assets, qualified full-time employees and operating expenditure. The differences from the old test matter:
- No statutory list by activity. The FTA's Free Zone Persons guide (CTGFZP1, May 2024) defines CIGAs as the essential, value-adding activities that generate revenue, and asks you to identify them for each qualifying activity.
- Full-time employees. The guide speaks of an adequate number of full-time, qualified employees in the free zone, and the same employee cannot be counted for more than one activity.
- Outsourcing stays inside the free zone. Outsourced CIGAs count only if the provider performs them in a free zone (a Designated Zone for distribution) and the free zone person supervises adequately. The exception is research and development on qualifying intellectual property.
- Decisions can be the CIGA. The guide's Example 22 treats a free zone fund manager that merely executes decisions taken by its foreign parent as not performing CIGAs in the free zone. Example 25 treats a holding company with no employees as having adequate substance where its board takes investment decisions in the free zone, evidenced by minutes at its free zone office.
- A failure is expensive. Under Article 5(2) of Ministerial Decision 229 of 2025, a person that fails any QFZP condition ceases to be a QFZP from the beginning of that tax period and for the following four tax periods.
Free zone SMEs can easily underestimate this exposure until the FTA asks questions.
What changed in 2025 and 2026
Ministerial Decision 229 of 2025, issued on 28 August 2025 and effective from 1 June 2023, replaced Ministerial Decision 265 of 2023. It sets the current list of qualifying activities: manufacturing, processing, trading of qualifying commodities, holding shares for investment, ships, reinsurance, fund management, wealth and investment management, headquarter services to related parties, treasury and financing, aircraft financing and leasing, distribution from a Designated Zone, logistics services, and activities ancillary to those. It also confirms the de minimis rule: non-qualifying revenue must not exceed the lower of 5% of total revenue or AED 5 million. The same decision requires a QFZP to prepare audited financial statements under Ministerial Decision 84 of 2025.
For free zone distributors there is a further layer. FTA Decision No. 6 of 2026 requires QFZPs distributing goods in or from a Designated Zone to obtain an independent agreed-upon procedures report for tax periods beginning on or after 1 January 2026.
How a fractional executive helps perform and document CIGAs
The CIGA test is not only a legal question. It is an operational one. Someone has to perform the relevant activities in the UAE. Someone has to make sure the documentation exists to prove it.
Most companies going through this have a capable team. They do not necessarily have anyone who can map their activities to CIGA definitions. Or tell which activities are genuinely performed here and which are merely directed from overseas. Or build the oversight and documentation the FTA expects. That is where a fractional executive with corporate tax and free zone governance experience earns their keep. It does not need to be a full-time hire. It does need someone who has done it before and can structure the internal processes so compliance is durable, not a one-off exercise ahead of a filing deadline.
One caution. The QFZP test looks for adequate full-time employees in the free zone. A fractional executive supports your substance position by mapping CIGAs, supervising outsourced work, taking part in board-level decisions and building the evidence file. They do not replace the team that performs the CIGAs. Take tax advice on how your structure is likely to be assessed.
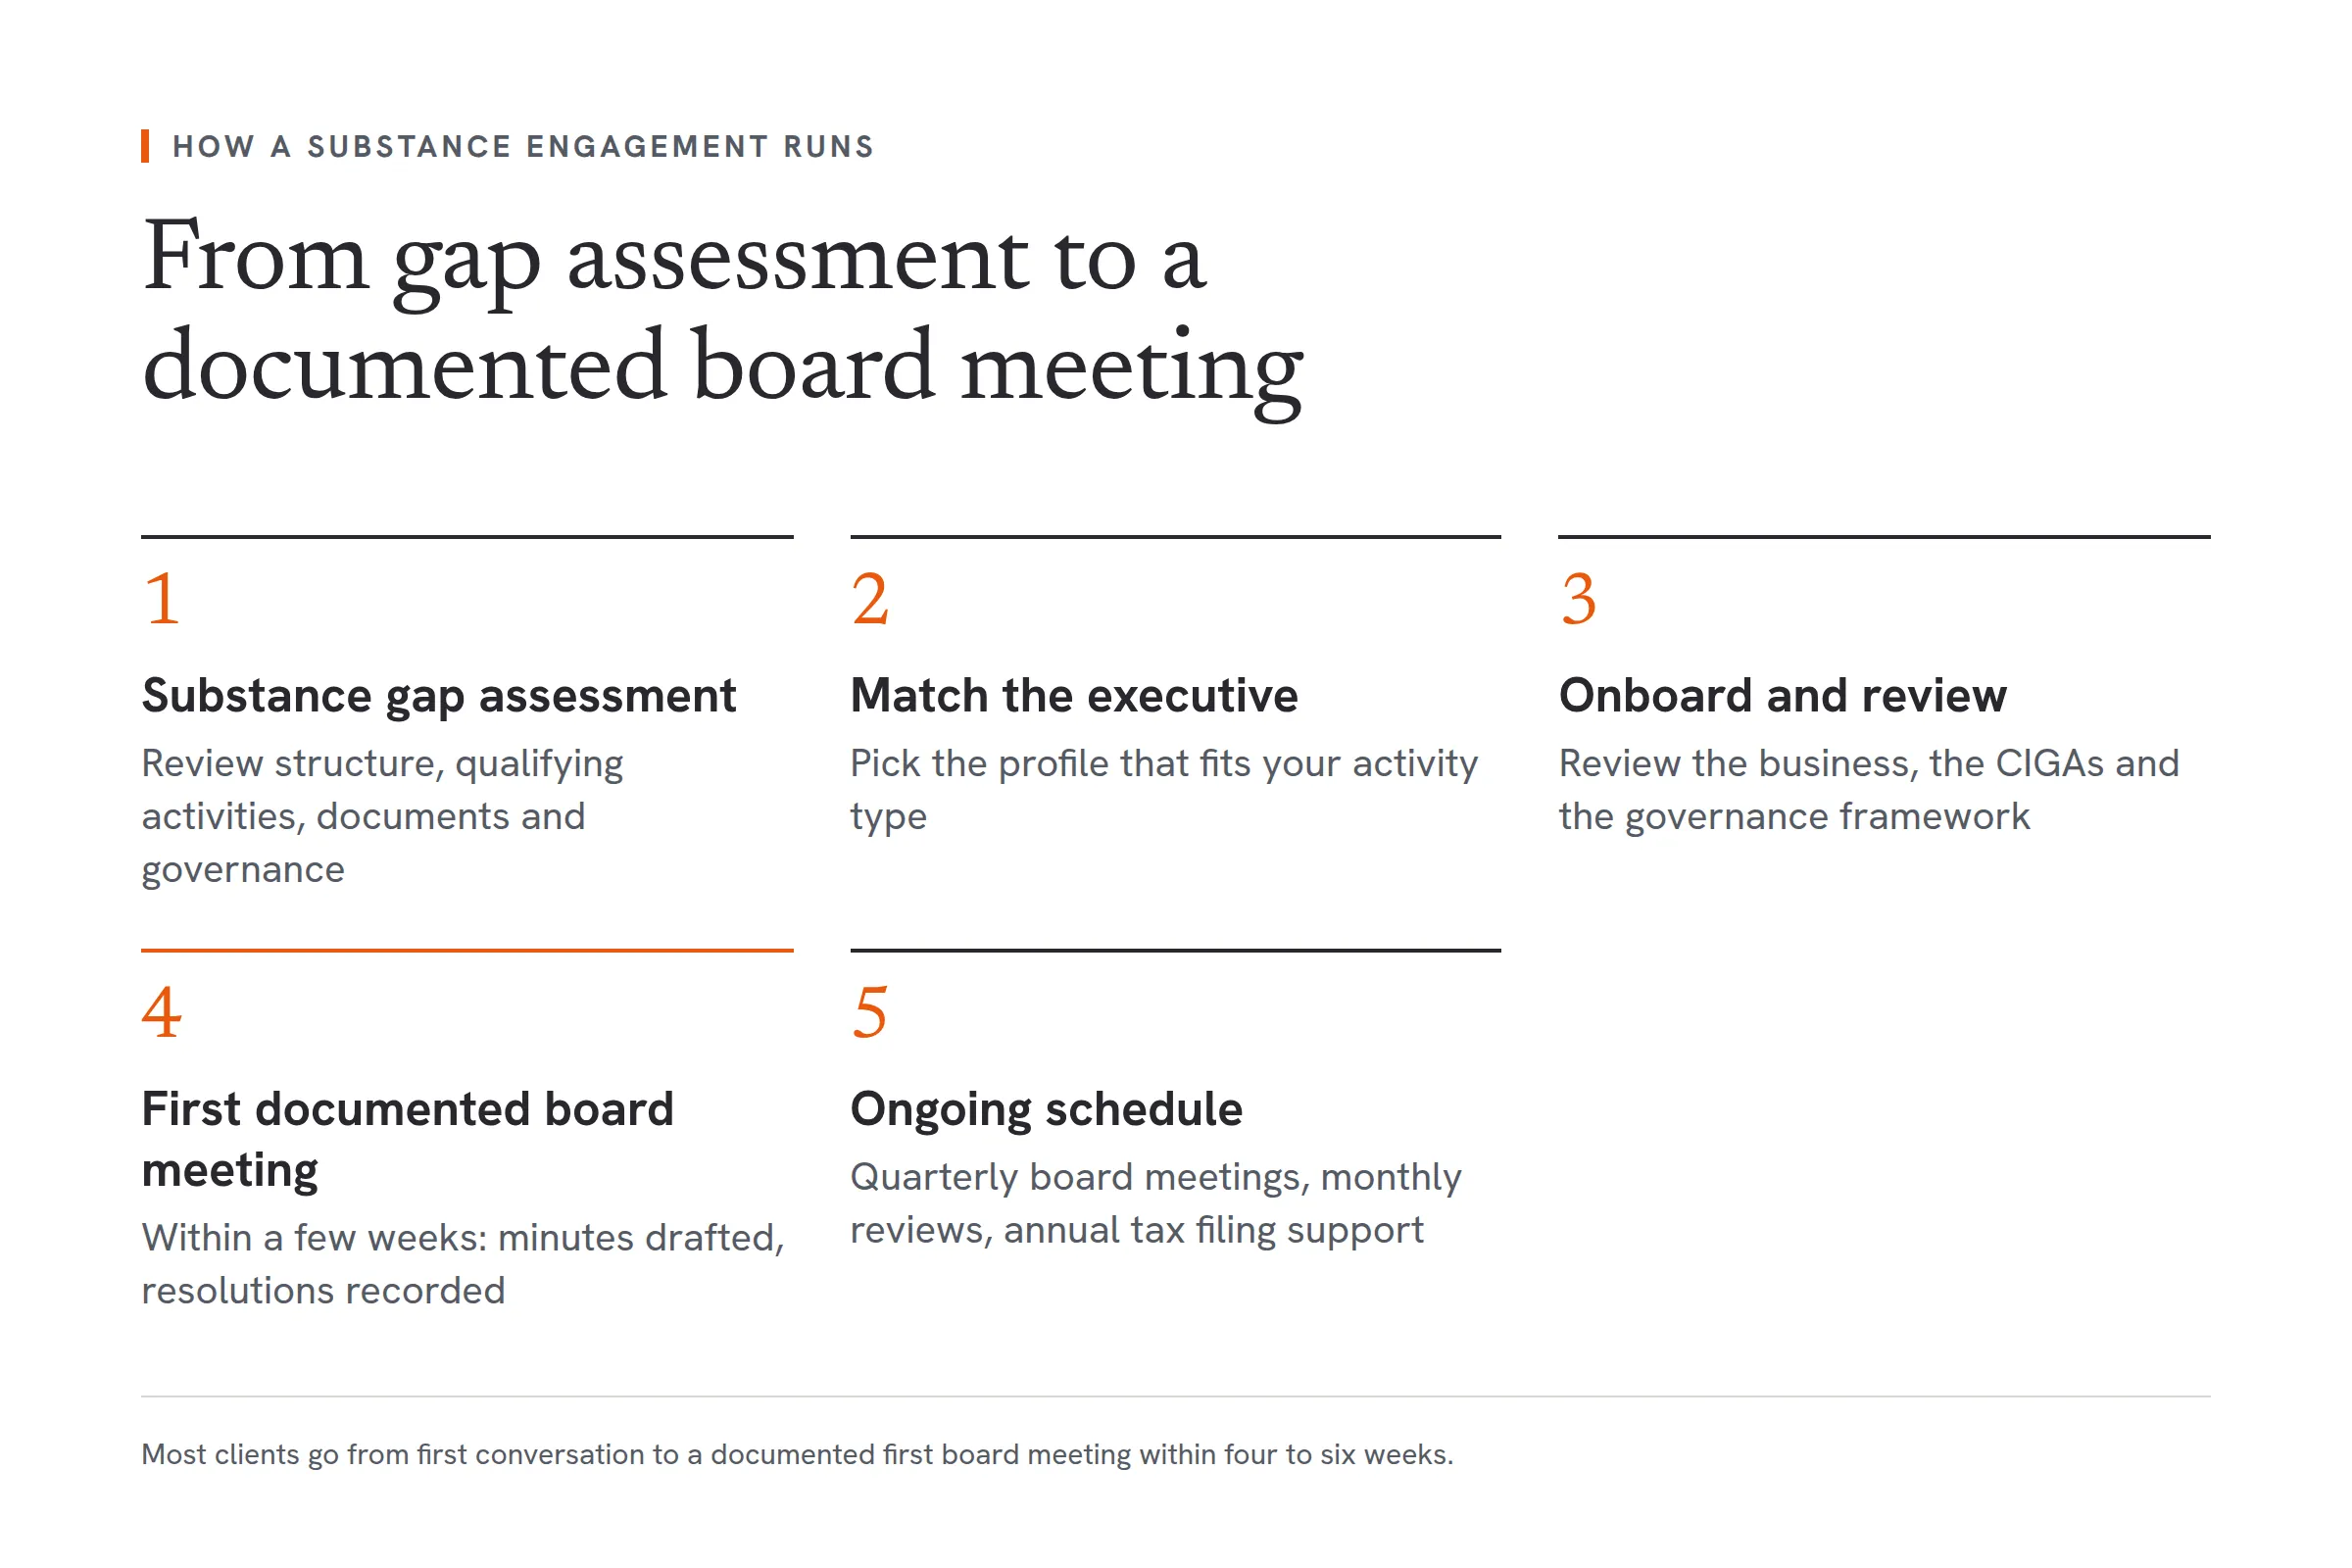
If you want to see how ensuring CIGA is performed and documented in the UAE works in practice, the starting point is always a mapping exercise. Match your actual activities to the qualifying activity and its CIGAs, then assess where gaps exist. For the consequences of getting this wrong under the old regime, see our review of ESR penalties.
A useful first step is to assess your CIGA position using our economic substance readiness tool.
Ready to clarify your CIGA position?
CIGA compliance is not complicated in principle. The hard part is translating statutory language into operational reality, then keeping the documentation up over time.
We work with UAE businesses to map the activities that earn their qualifying income, structure their outsourcing arrangements properly and build oversight processes that hold up under FTA scrutiny. Our free zone substance and tax service exists for this purpose.
A clear-headed assessment now is considerably cheaper than the alternative. If you are unsure whether your CIGAs are genuinely performed in the UAE, or whether your documentation would survive an audit, get in touch with the Fractional Dubai team.
FAQs
What happens if a company cannot demonstrate its CIGAs were performed in the UAE?
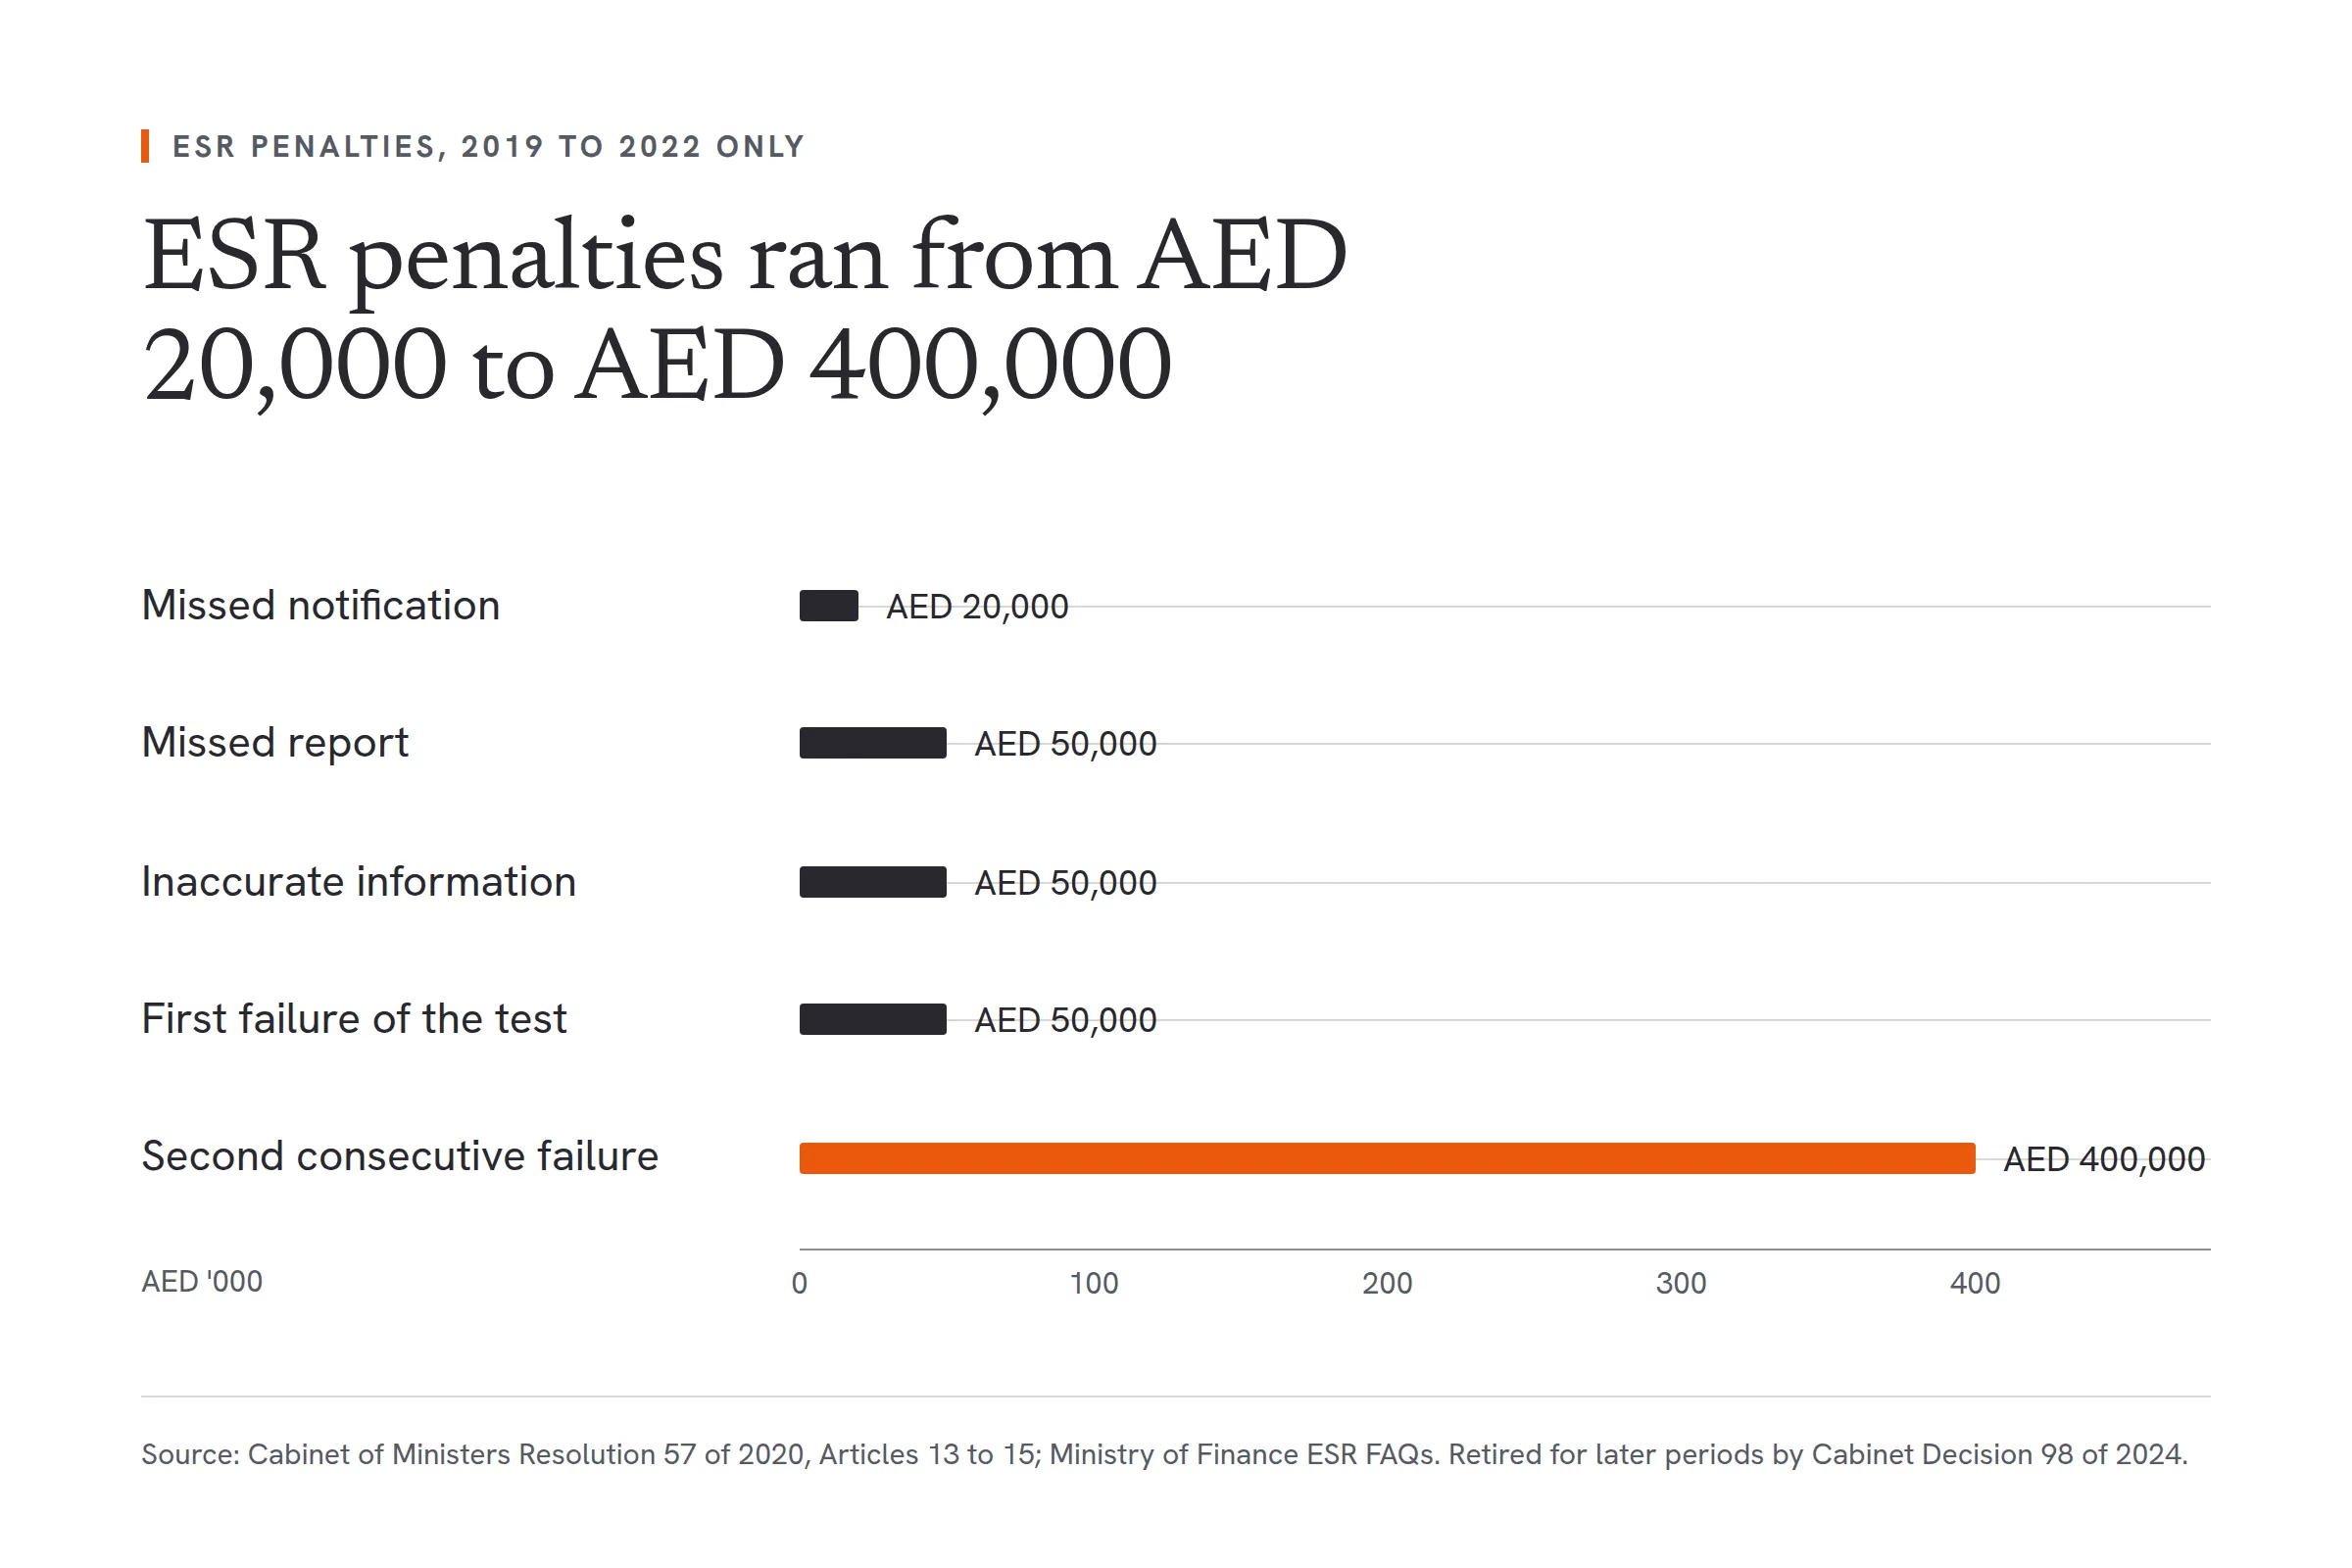
For the ESR period (2019 to 2022), failing the substance test carried a penalty of AED 50,000, rising to AED 400,000 for a second consecutive failure, plus information exchange with the foreign tax authorities of the parent, ultimate parent and beneficial owner. For free zone businesses under corporate tax, failing the CIGA substance requirement means losing QFZP status for that tax period and the following four.
Can CIGAs be performed by a related party rather than directly by the entity?
Yes. Outsourcing CIGAs to a related party or a third party was permitted under the ESR, and is permitted under the QFZP rules, provided the provider performs them in the UAE (in a free zone for QFZP purposes) and the business demonstrates genuine supervision. The same provider resource cannot be counted for more than one entity.
Is the CIGA test the same for all nine relevant activities?
No. Each relevant activity had its own list of example CIGAs. The activities that counted for a shipping company were entirely different from those for an investment fund manager or an IP business. Entities assessed their obligations against the list for their activity, not against a generic standard.
Does the end of ESR mean substance requirements no longer apply?
No. Cabinet Decision 98 of 2024 ended the ESR notification and reporting requirement for financial years ending after 31 December 2022. It did not remove the substance concept itself. Free zone companies seeking QFZP status under corporate tax must still perform their core income-generating activities in the free zone, with adequate assets, full-time employees and expenditure.
How much documentation is needed to evidence CIGA performance?
Enough to show the CIGAs were genuinely performed in the UAE: typically employment contracts, activity records, signed board minutes, oversight reports for outsourced arrangements and the related contracts. Under the ESR, records had to be kept for six years. A QFZP must keep Corporate Tax records for seven years after the end of the tax period.