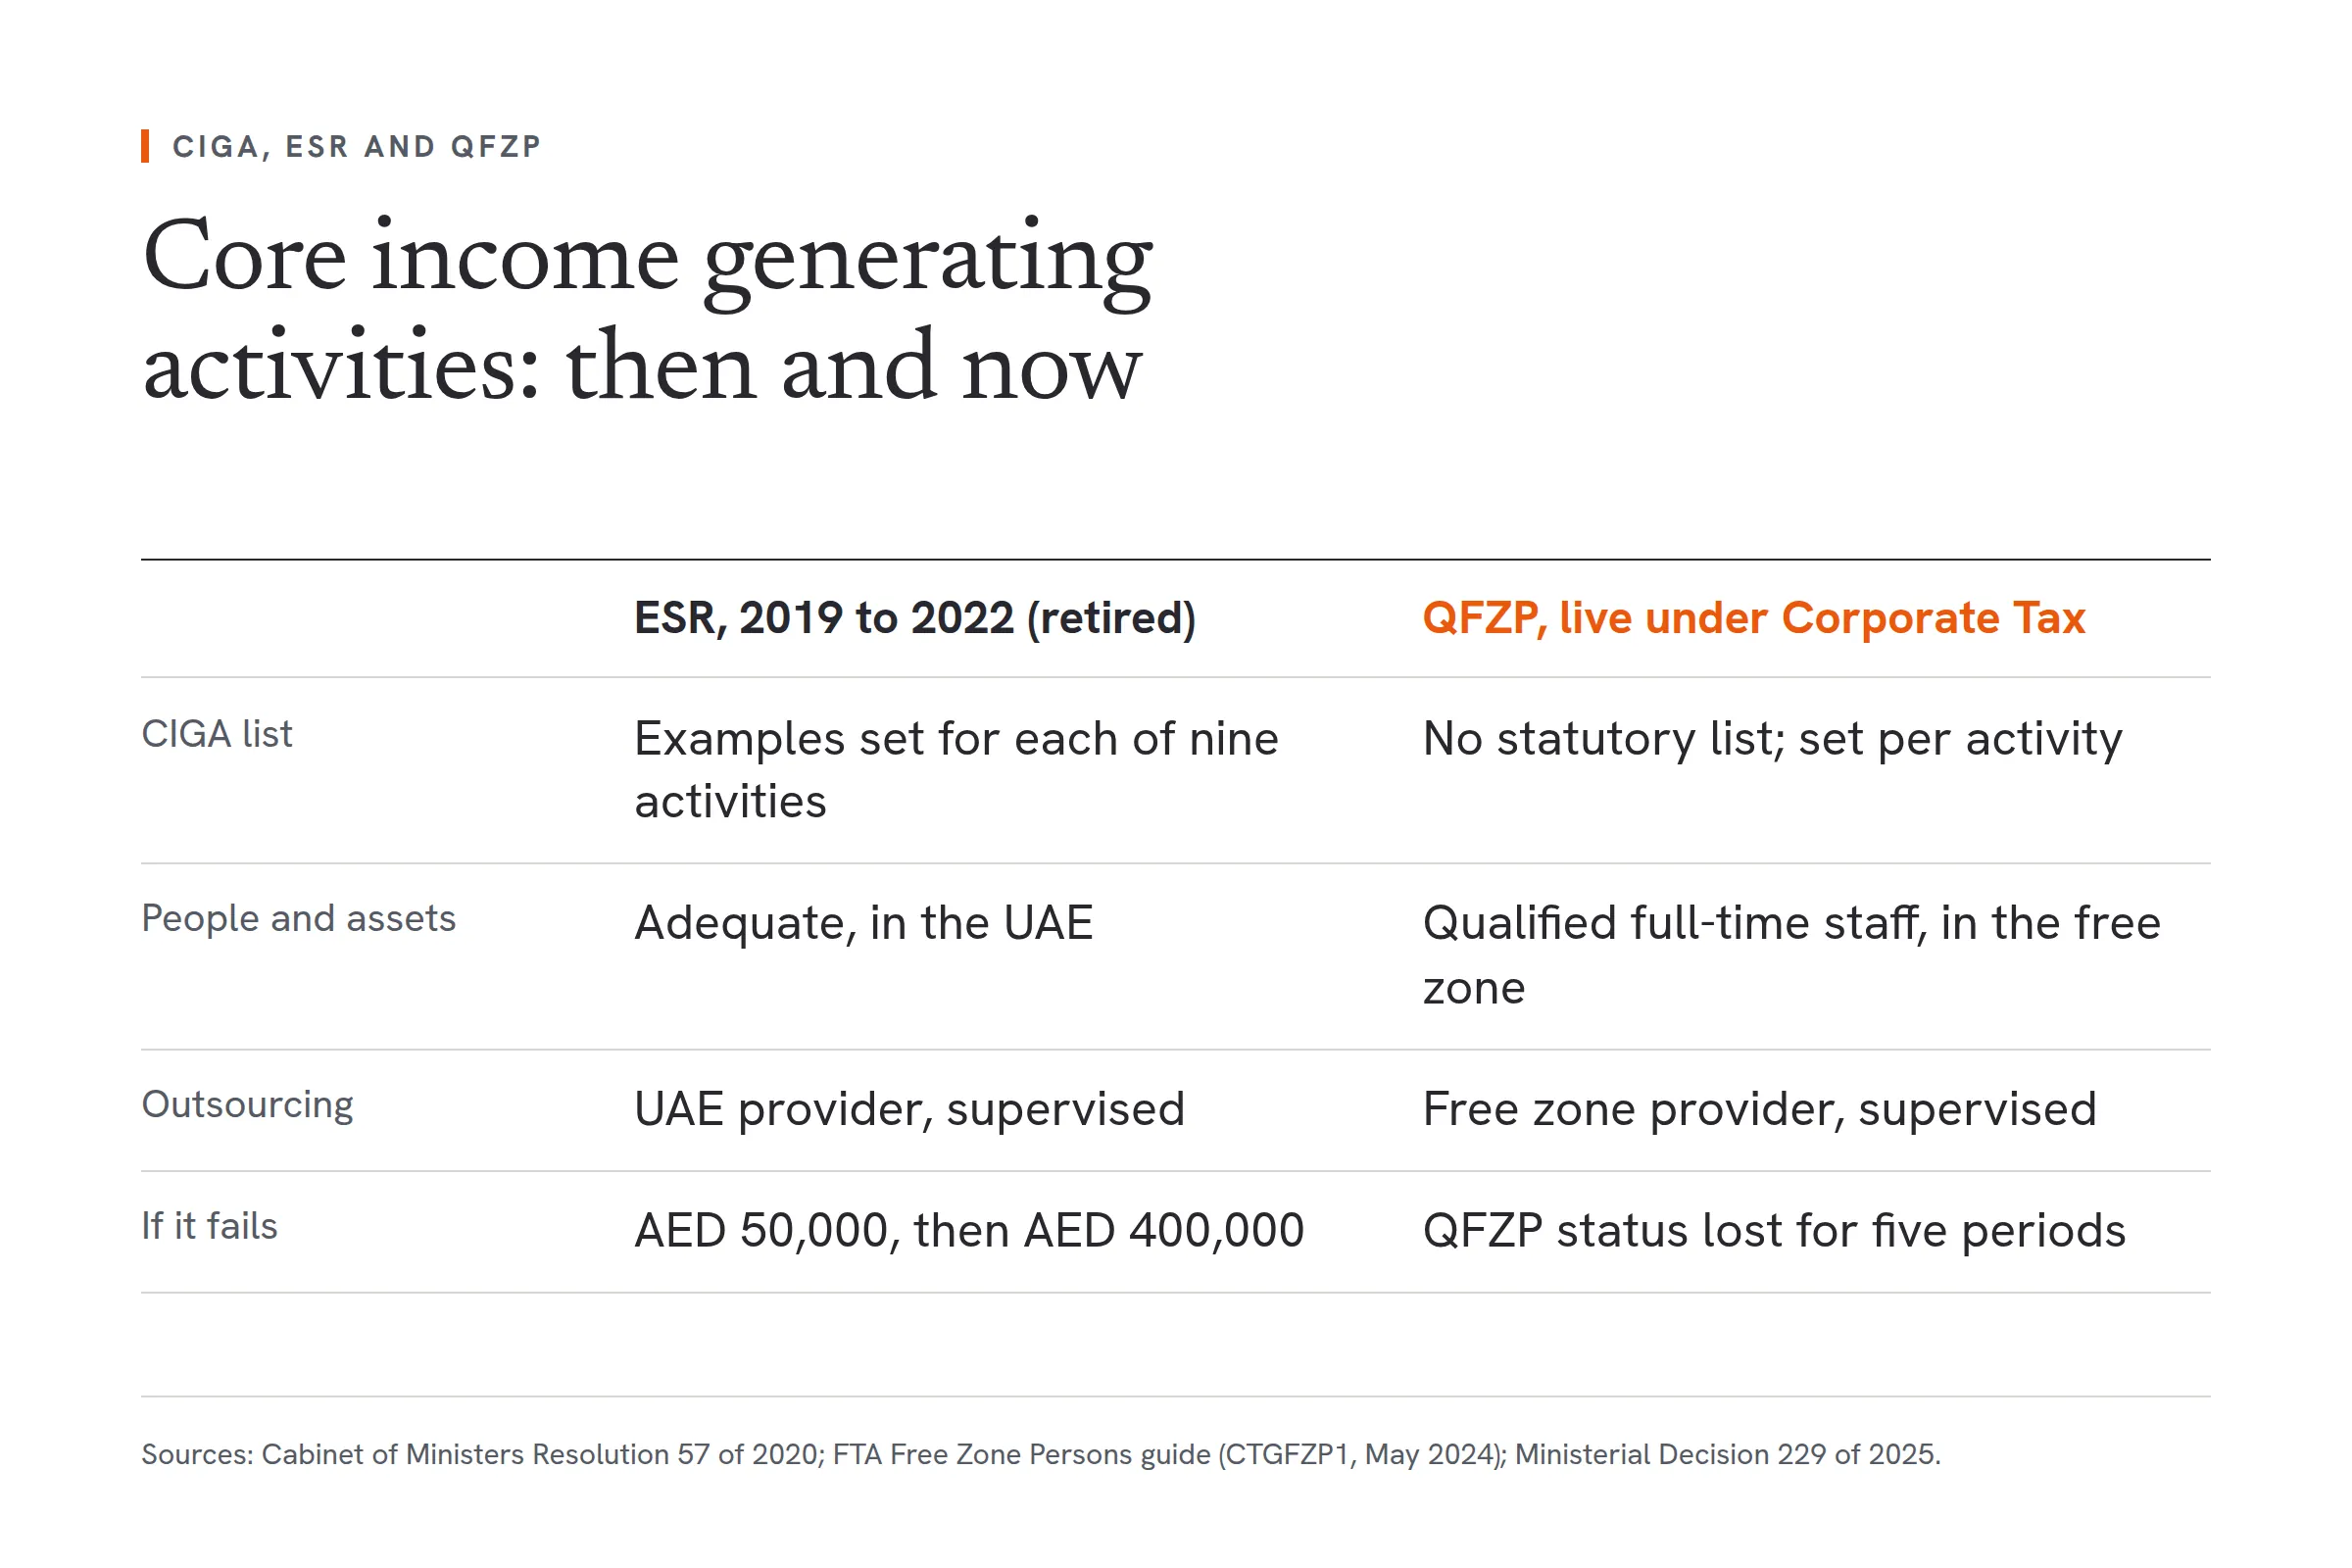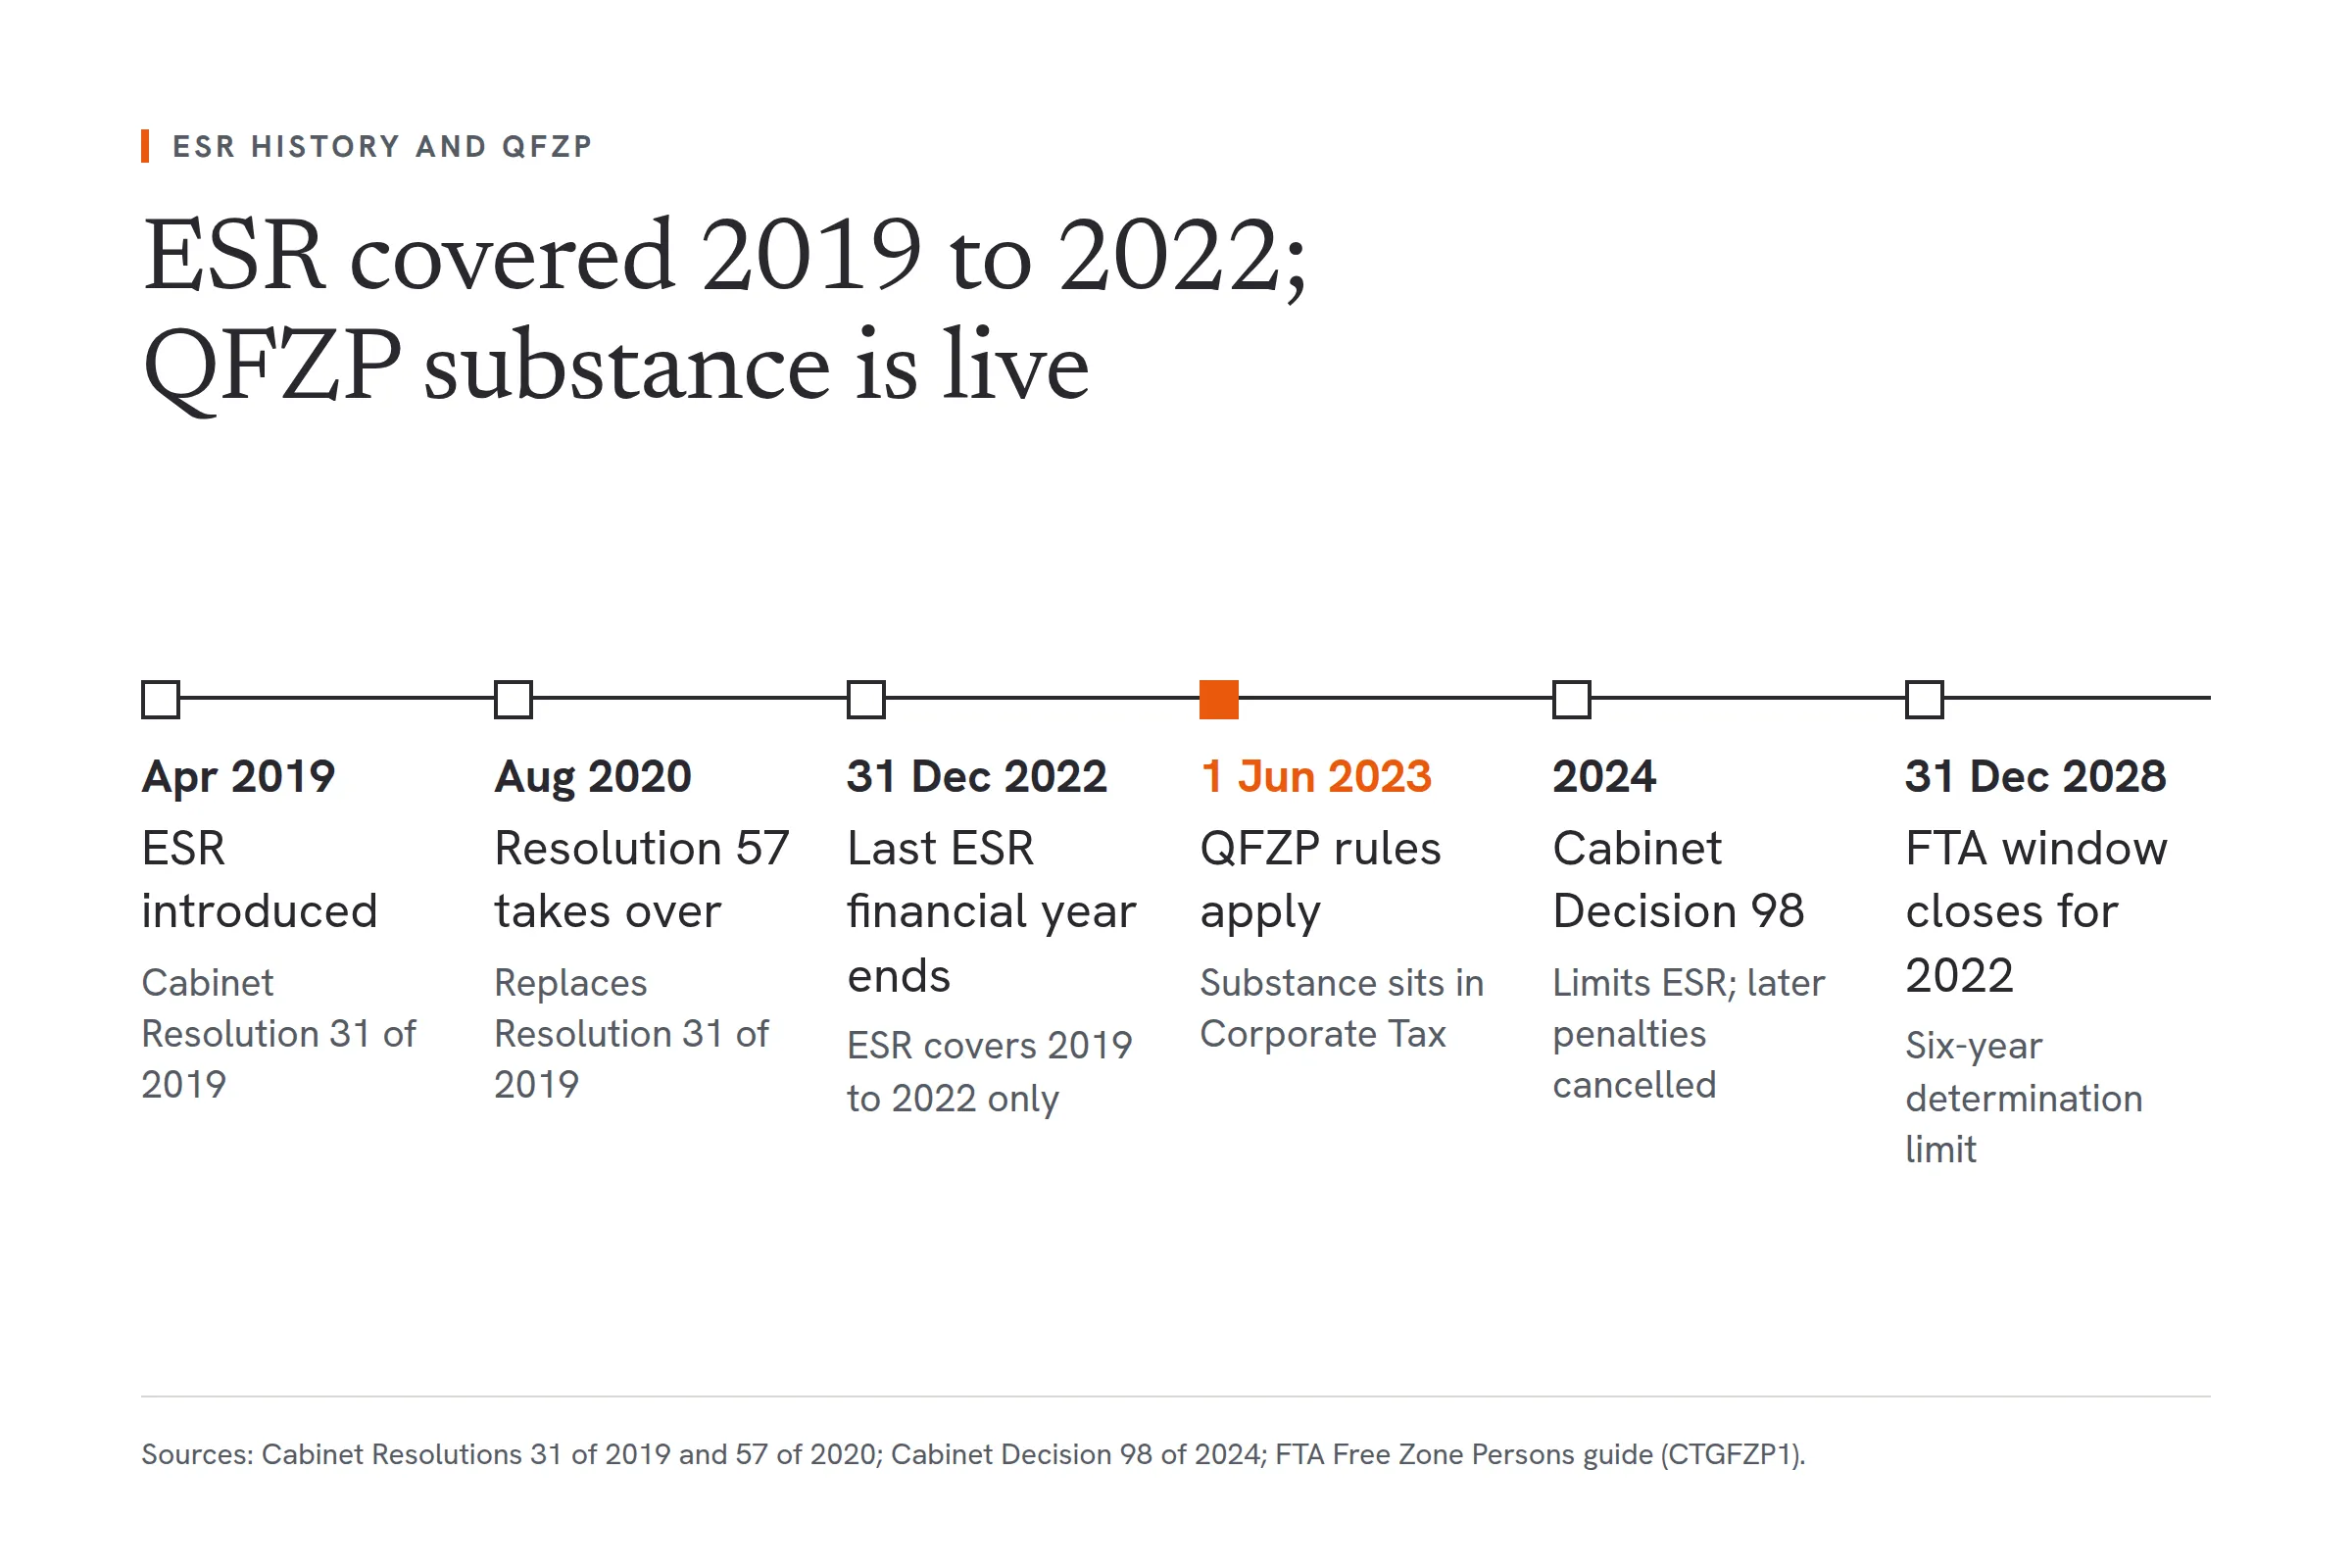
Update, September 2026. The UAE Economic Substance Regulations have been retired. Cabinet Decision 98 of 2024 amended Cabinet Decision 57 of 2020 so that ESR applies only to financial years from 1 January 2019 to 31 December 2022. For any financial year ending after 31 December 2022 there is no ESR notification, no ESR report and no penalty exposure. Penalties already levied for those later periods were cancelled, and amounts already paid are refunded by the Federal Tax Authority. This article is kept as a historical explainer of the regime as it applied to 2019 to 2022. If you run a free zone business today, the live question is the adequate-substance condition attached to Qualifying Free Zone Person status under UAE Corporate Tax.
Most companies that failed the UAE Economic Substance Test did not fail because they lacked employees or assets. They failed because their decisions happened somewhere else. That remains the most common weakness in a free zone substance position today, even though the regime that named the test has gone.
Picture a board that meets by video call from London. Or a parent company in Amsterdam that sends instructions down the chain, with the UAE subsidiary rubber-stamping them in Dubai. The ESR called this the "directed and managed" test. A surprising number of companies came unstuck on it.
In short: for financial years 2019 to 2022, a licensee passed the test only if its board met in the UAE with a physical quorum, minuted real strategic decisions and had the expertise to take them. Here is what that required, and where the same logic still applies to a Qualifying Free Zone Person.
What "directed and managed" means inside the economic substance test
The directed and managed test was one of three legs in the three-part economic substance test. To pass it, a licensee had to show that its relevant activity was genuinely governed from within the UAE. A UAE address was not enough. Neither was a UAE trade licence. Real strategic decisions had to be made, by qualified people, on UAE soil.
The legal basis is Article 6(1)(b) and 6(3) of Cabinet of Ministers Resolution No. 57 of 2020, the ESR legislation that governed financial years 2019 to 2022. Be clear on what Cabinet Decision 98 of 2024 changed. It limited the ESR to financial years from 1 January 2019 to 31 December 2022.
The directed and managed test itself was never carried into Corporate Tax as a named condition. What carried over is the question underneath it: where are the decisions that generate income taken? We return to that below.
The legal standard: six requirements
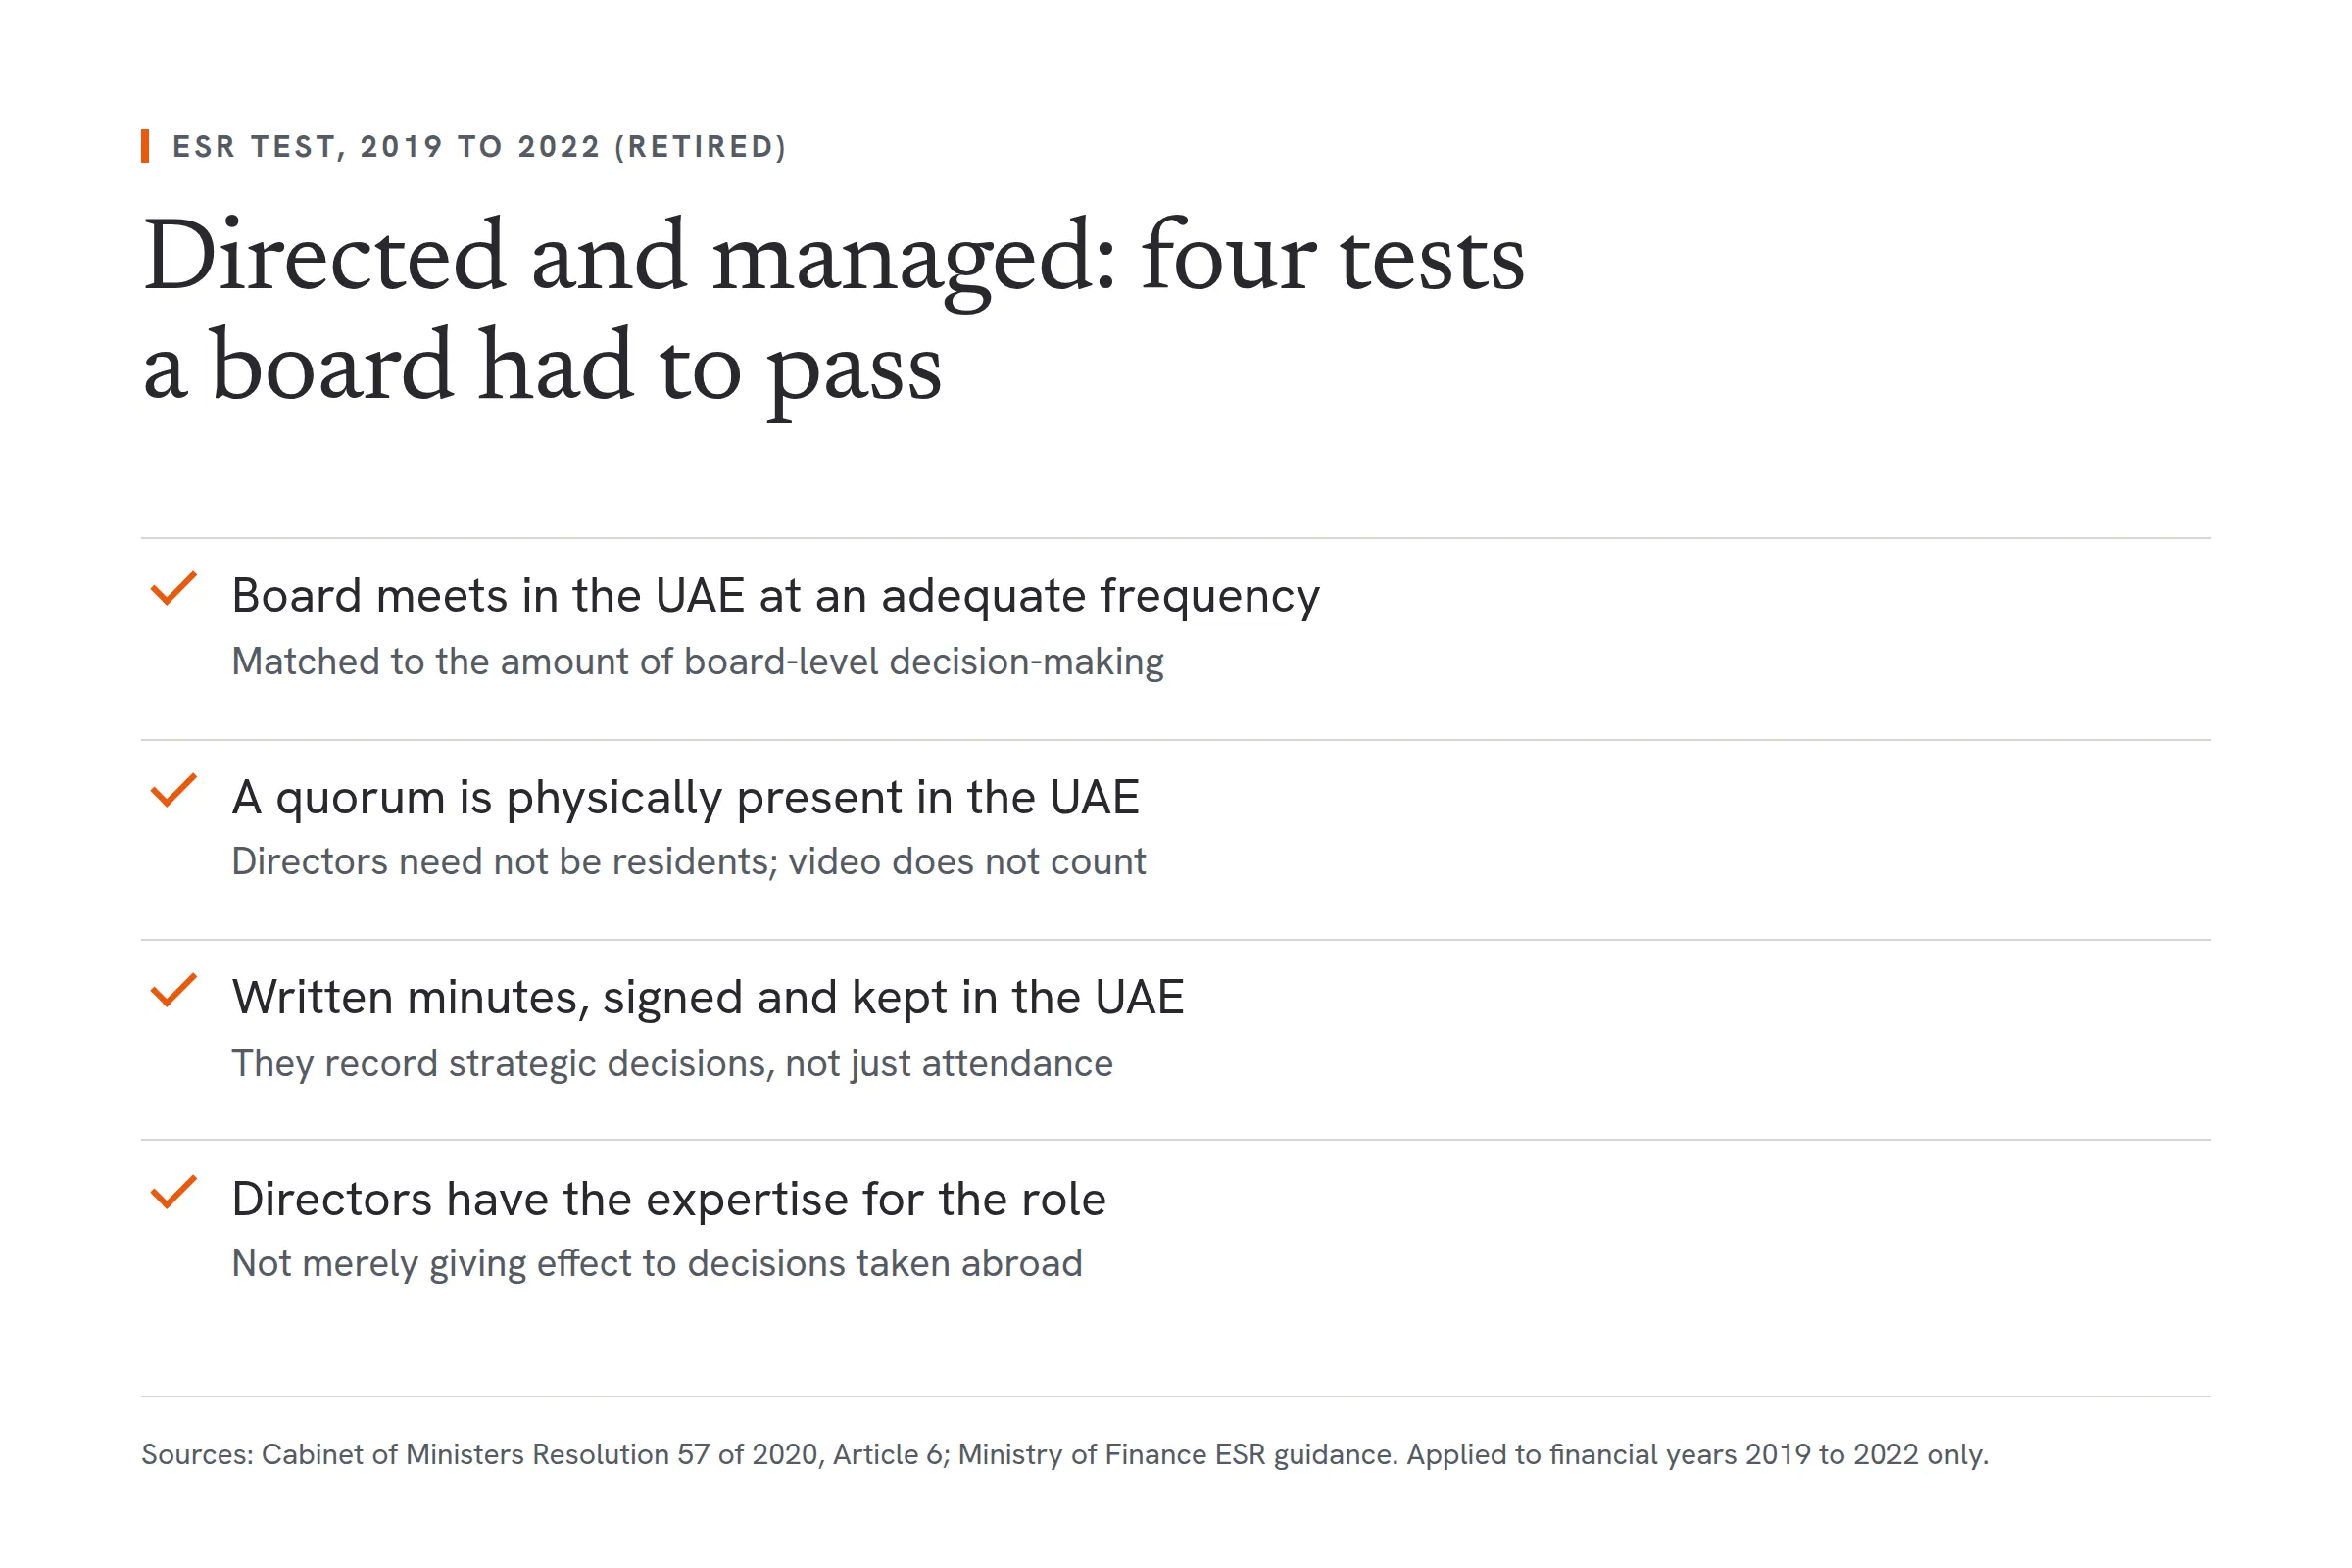
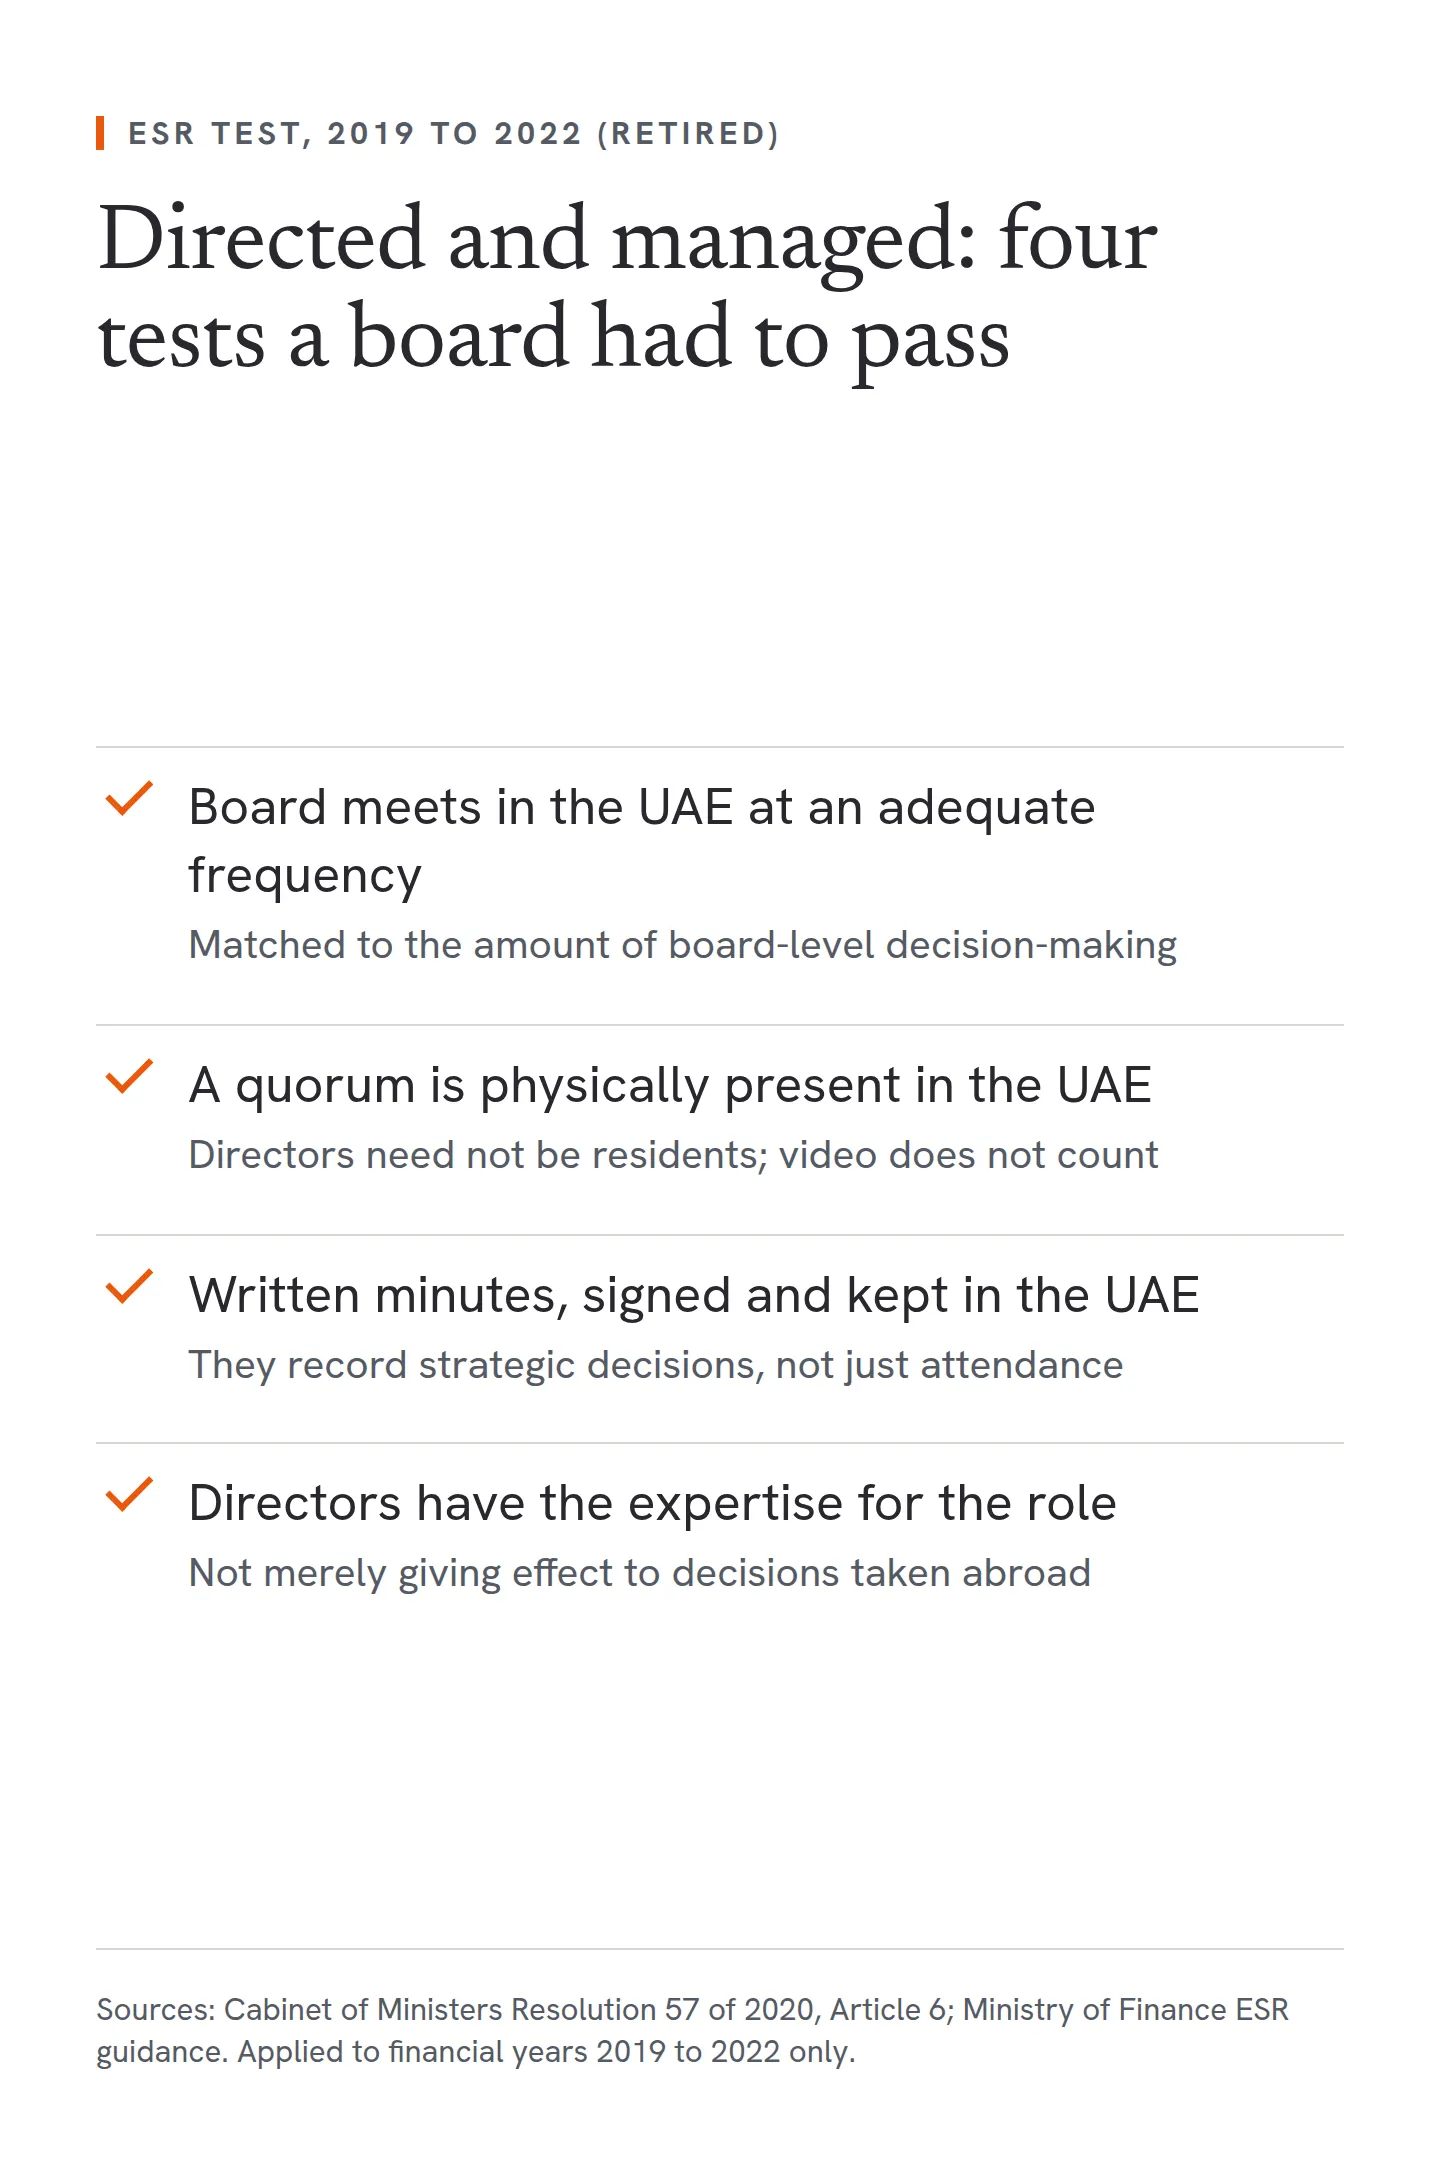
Article 6(3) of Resolution 57 set out six conditions. Four of them did most of the practical work.
Adequate frequency of UAE board meetings. The Resolution uses the word "adequate". The board had to meet in the UAE as often as its level of decision-making required. It did not specify two meetings a year or four. A passive structure with minimal transactions needed fewer meetings than a trading company making regular commercial decisions. Either way, the frequency had to be defensible if the FTA came asking.
Physical quorum in the UAE. This is where video calls caused problems. A quorum of directors had to be physically present in the UAE at each board meeting. The Ministry of Finance's guidance confirmed that directors did not have to be UAE residents, but had to be physically present in the UAE when taking strategic decisions. Dialling in from abroad did not count.
Written minutes, signed and kept in the UAE. Directors who attended had to sign written minutes of each board meeting. The minutes had to record the making of strategic decisions in relation to the relevant activity. Both the minutes and the licensee's records had to be kept in the UAE. A company secretary in London filing the minutes on a server in Dublin did not satisfy this.
Director expertise. The directors had to have the knowledge and expertise to discharge the duties of the board. This is the requirement that is easiest to overlook. The guidance added that directors must not be merely giving effect to decisions being taken outside the UAE. A UAE-based nominee director who nods along and signs documents did not pass. The test was whether directors understood the core income-generating activities they were overseeing and could make informed decisions about them.
Where a shareholder, partner or manager ran the licensee rather than a board, the same requirements applied to that person as if they were a director. A licensee whose only activity was a pure holding company business faced a reduced test. It was not required to be directed and managed in the UAE unless its licensing authority required it.
What "adequate frequency" meant in practice
Everyone asked this question. The honest answer is that the regulation gave no number.
What it gave was a principle: frequency calibrated to activity level. A licensee doing very little, such as a passive holding structure with minimal transactions, needed far less board activity than one with active operations, real revenue and ongoing strategic decisions. Investment firms and holding vehicles often sat in the lighter category.
Frequency alone was never the point. Content mattered more. A quarterly meeting that reviews management accounts, discusses the direction of the business and records genuine deliberation is worth far more to the FTA than several meetings that tick boxes. The question was whether those meetings were real governance.
The outsourcing trap: CIGAs can be outsourced, oversight cannot
A mistake we see regularly: a company outsources its operational functions to a service provider and assumes that satisfies the substance test. Then it runs a board process that is entirely nominal.
These are two separate things. The ESR allowed a licensee to outsource core income-generating activities, provided it monitored and controlled the outsourced activity and the work was performed in the UAE. But the Ministry of Finance's FAQs were explicit that a licensee could not outsource "directed and managed". The licensee had to show oversight and control of its relevant activity in the UAE itself. A qualified director or genuine decision-maker still had to be directing and managing from the UAE.
The same logic reaches QFZPs, in a different form. The FTA's Free Zone Persons guide treats a free zone fund manager that merely executes decisions taken by its foreign parent, with all the investment committee members based abroad, as not performing core income-generating activities in the free zone. Key decisions need to be made within the free zone, not merely executed there.
Common mistakes that failed this test
The patterns were consistent.
The offshore parent problem. The real decisions are made at group level, by a Chief Financial Officer (CFO) in Singapore or a board in Switzerland. The UAE entity does what it is told. The UAE board meeting is a formality, and the minutes reflect decisions already made elsewhere. That is not directed and managed from the UAE.
The telephone director. A UAE-licensed company where the only director with UAE presence is a professional nominee. The nominee signs documents but has no real knowledge of the business. The expertise requirement makes this arrangement unworkable.
Bad minute-taking. Directors attend a meeting in Dubai, but no minutes are prepared. Or a paralegal in another jurisdiction prepares them afterwards. Or they record nothing beyond the fact that a meeting occurred. Minutes must record the making of strategic decisions, not just their outcomes.
The video quorum assumption. Many companies believed that directors joining by video from overseas satisfied the physical presence requirement. It did not.
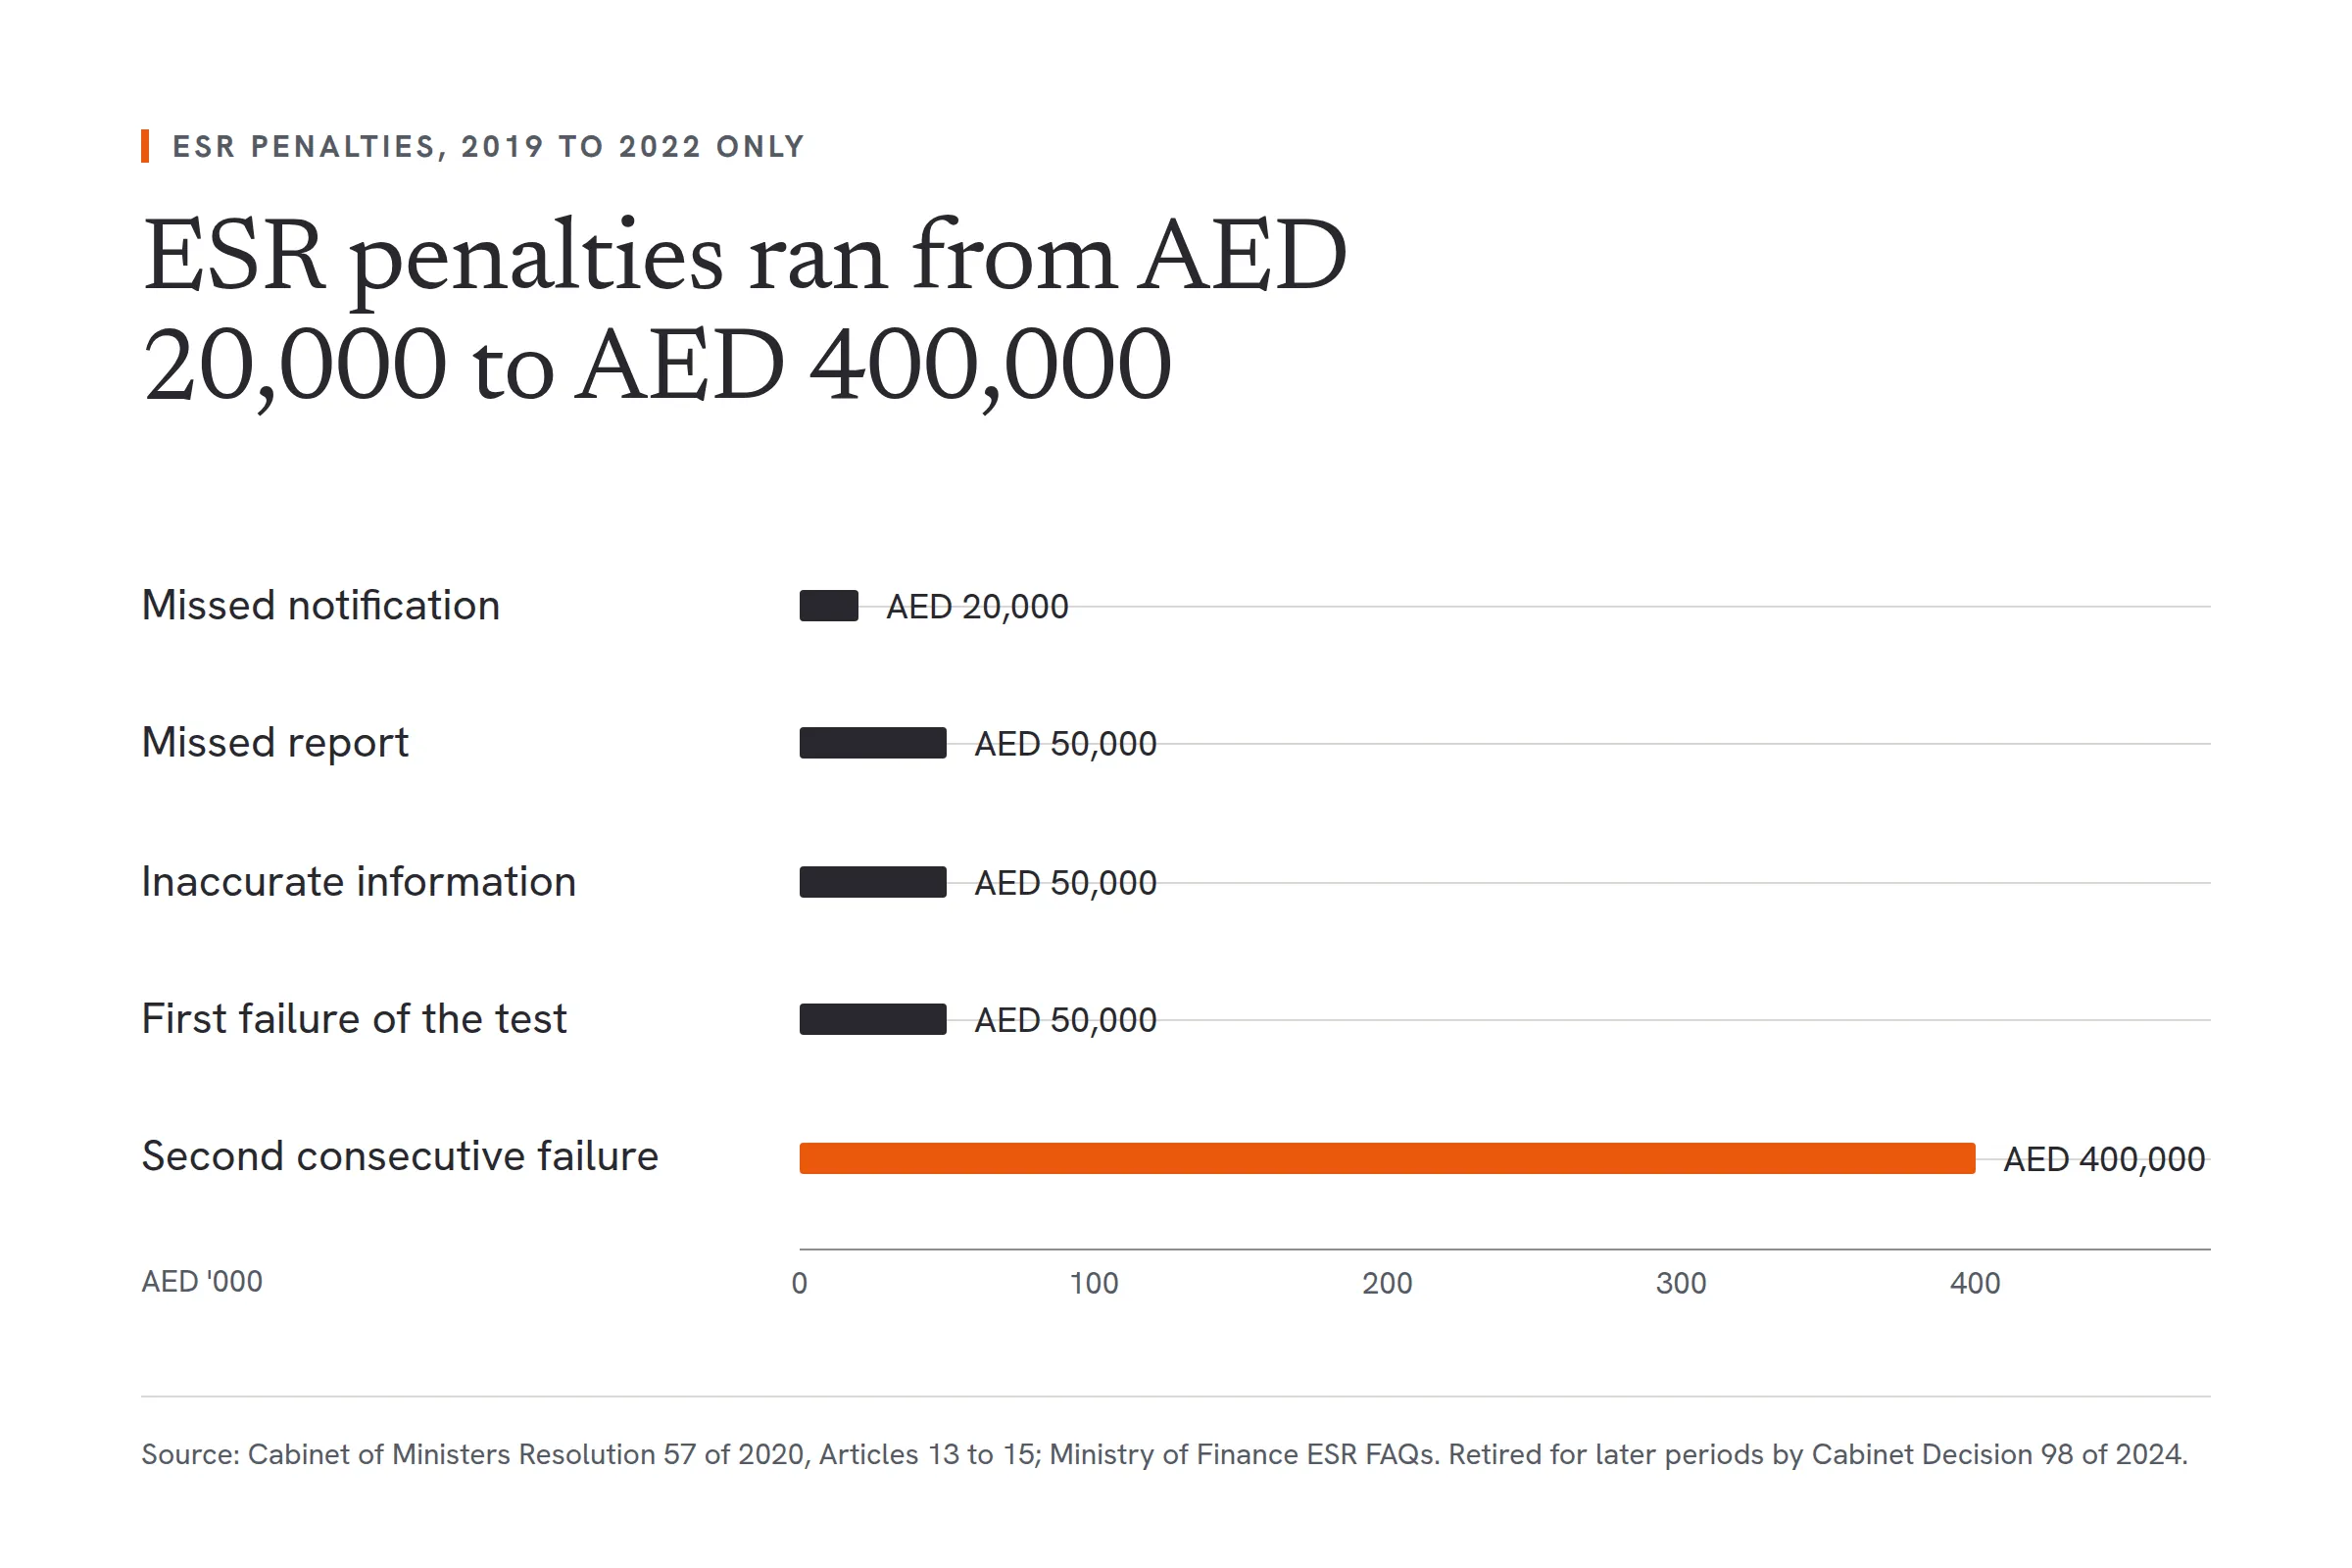
For the ESR period these failures carried the penalties set out in our review of the consequences of failing the economic substance test: AED 50,000 for a first failure and AED 400,000 for a second consecutive failure. For a QFZP the exposure is different but larger in kind. Failing any QFZP condition means ceasing to be a QFZP from the beginning of the tax period and for the following four tax periods. Income is then taxed under the standard Corporate Tax regime.
Where decision-making still matters under QFZP rules
A QFZP must perform its core income-generating activities in a free zone, with adequate assets, qualified full-time employees and operating expenditure there. There is no board-quorum test. But for businesses whose income comes from decisions rather than operations, the board is the activity.
The FTA's guide gives the example of a free zone holding company with no employees whose board takes investment decisions. It is treated as having adequate substance provided the decision-making takes place in the free zone, for example evidenced by minutes of board meetings at its free zone office.
The lesson carries over directly from the ESR. If your income depends on decisions, take those decisions, and minute them, where you claim your substance.
How a fractional executive can support directed and managed
Many SMEs and free zone companies face a simple problem. They cannot justify, or simply do not need, a full-time senior executive resident in the UAE. But they do need a UAE-based, qualified person to provide or attend board-level oversight.
A fractional executive can provide this for directed and managed purposes when engaged as a director or board-level adviser who attends in person. They bring genuine expertise in the relevant activity and take part in real strategic deliberation. They review performance against targets and contribute to decisions rather than rubber-stamping them.
The documentation that comes with a properly structured engagement maps directly onto what the regulator expects. Meeting attendance records, signed minutes, evidence of expertise: these are not bureaucratic extras here. They are the substance test made visible.
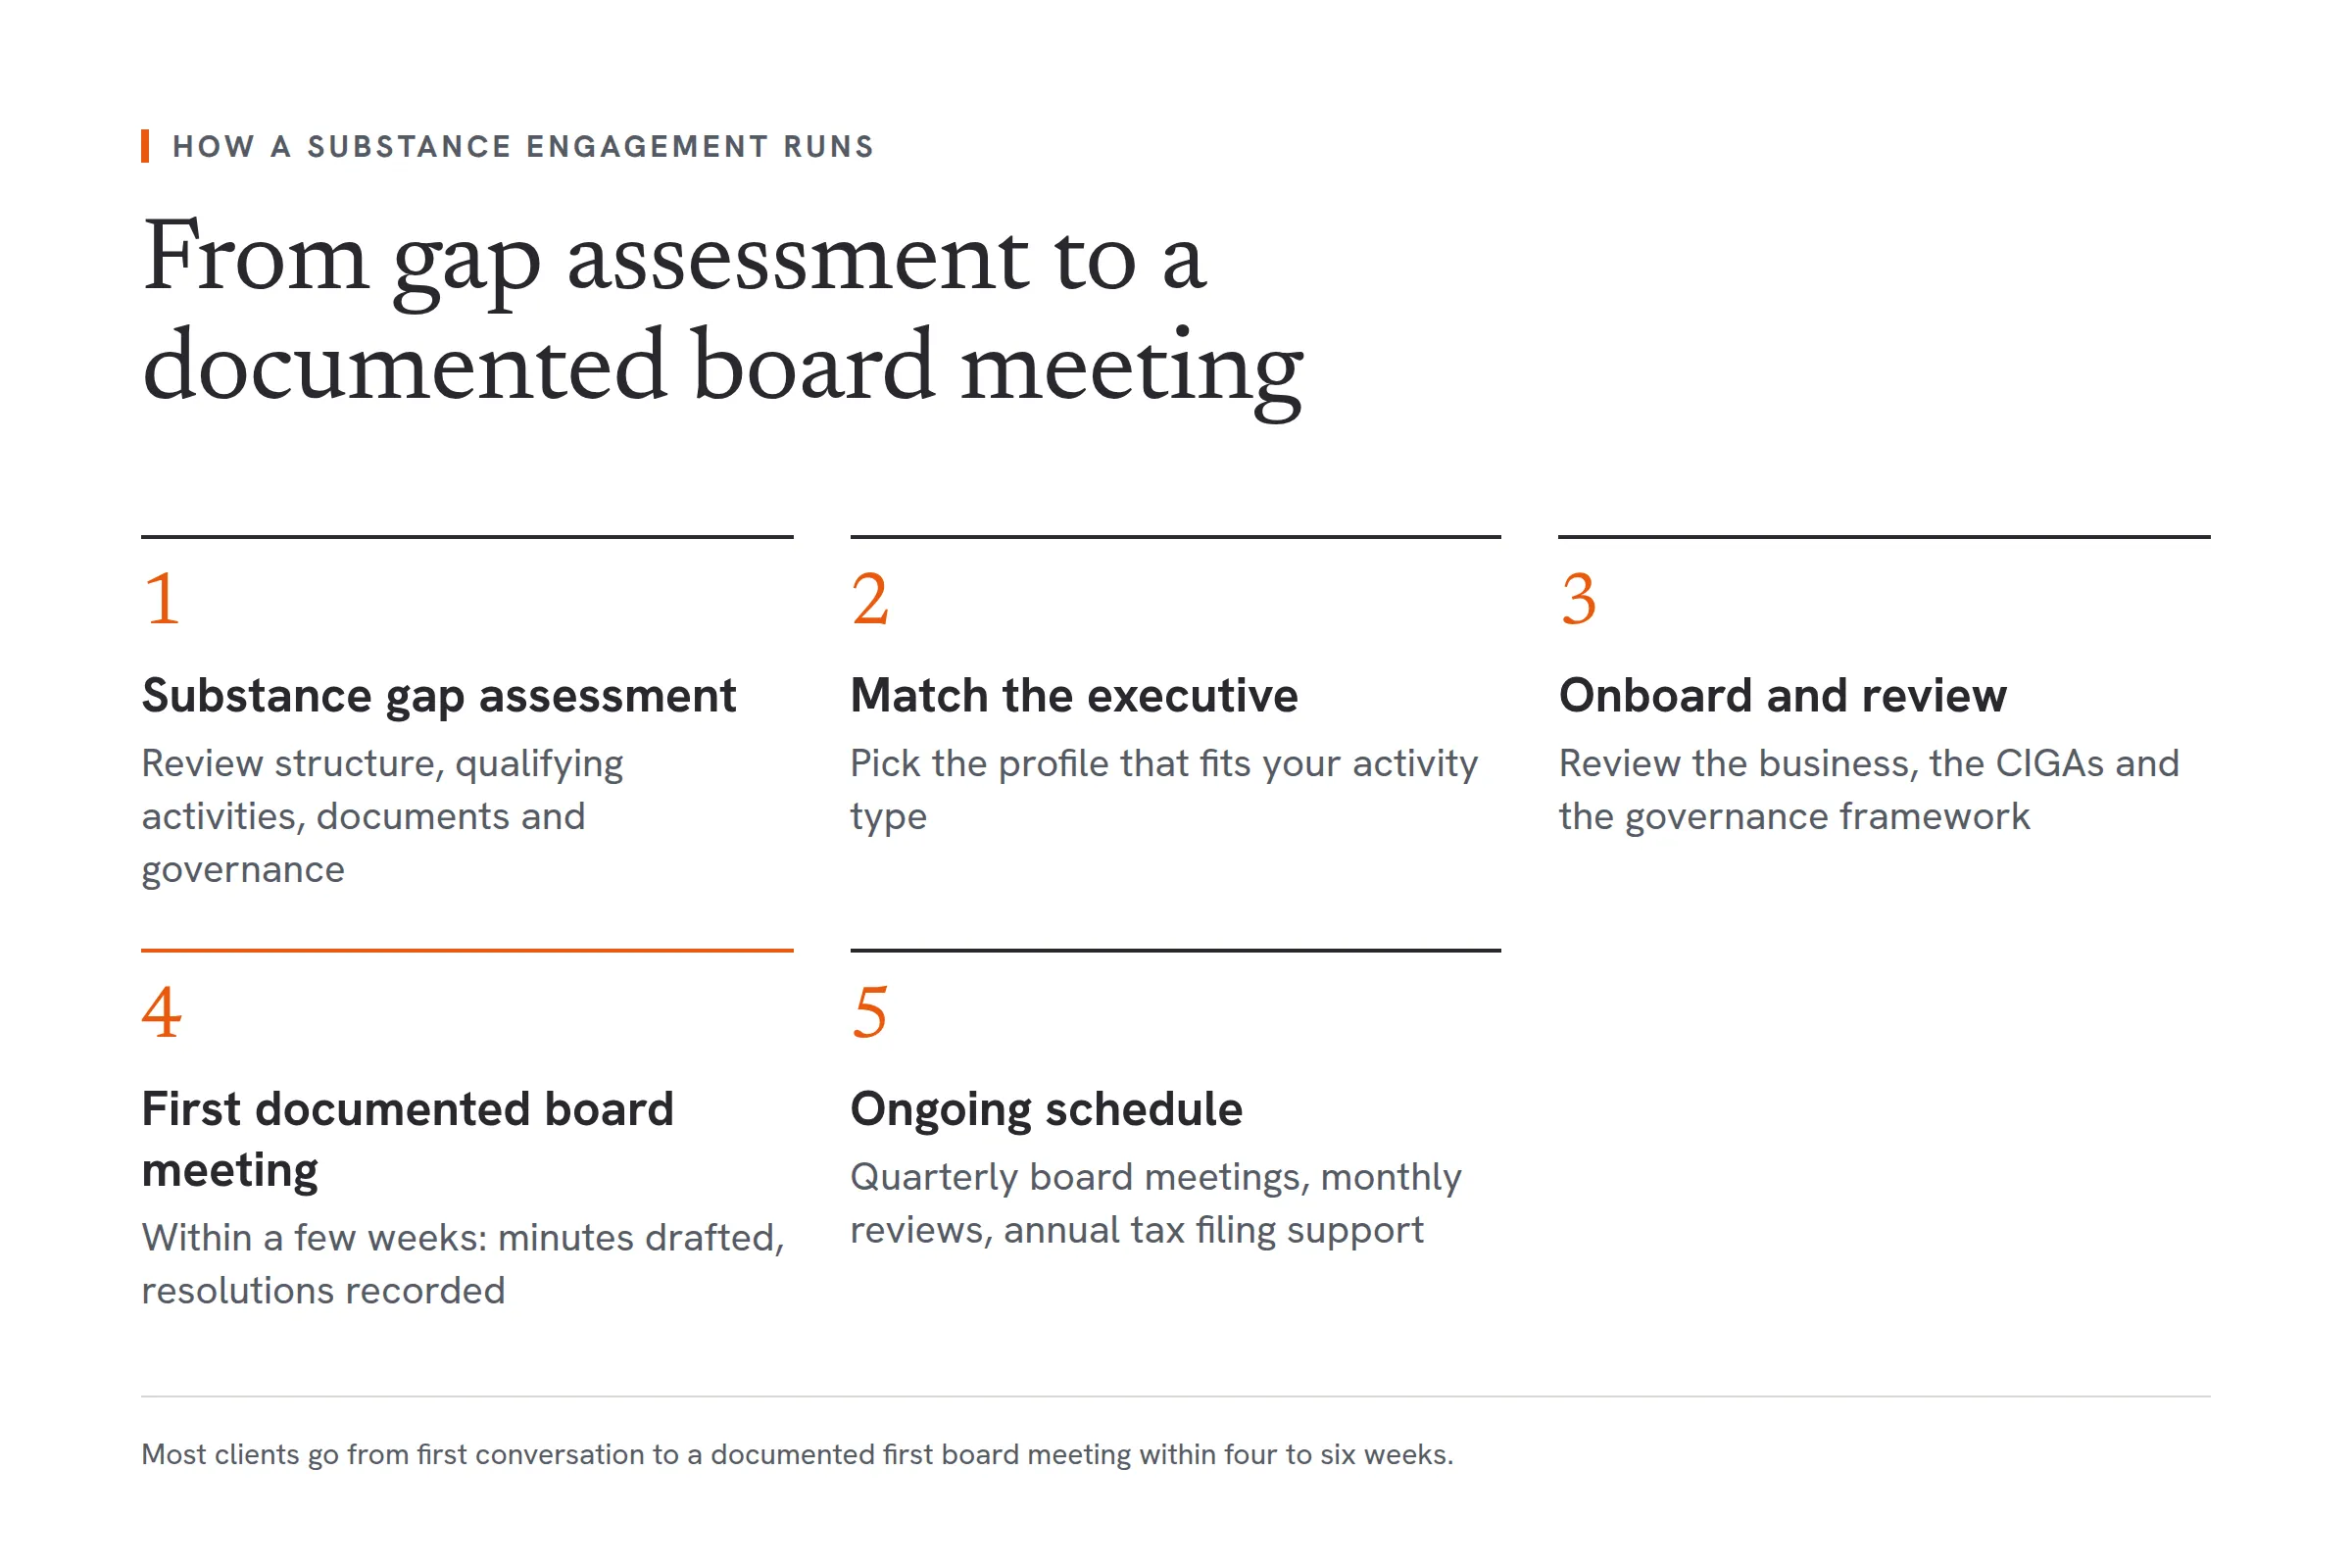
Here is how a fractional engagement is structured. It typically involves a defined scope of oversight, regular in-country attendance at governance meetings and a clear contemporaneous paper trail. Our free zone substance and tax service is designed for this purpose.
Documentation checklist: what the FTA expected
If the FTA assessed a licensee for the ESR period, a compliant directed and managed position looked like this in the file:
- Board meeting calendar showing dates, UAE locations and attendees
- Signed minutes for each meeting, stored in the UAE, recording the making of strategic decisions in relation to the relevant activity
- Evidence of physical presence in the UAE at the time of each meeting (travel records, hotel receipts or similar)
- Director CVs or profiles demonstrating expertise relevant to the relevant activity
- Outsourcing contracts (if applicable) showing the licensee's monitoring and oversight role
- Records kept in the UAE, with anything submitted to the authorities provided in English
- For QFZP entities: documentation linking board decisions to free zone operations and core income-generating activities
On timing, Article 7 of Resolution 57 lets the FTA determine a failure up to six years after the end of the financial year. Article 8 requires supporting information to be retained for six years from submission. For the ESR period, the window for 2019 closed on 31 December 2025, while 2022 stays open until 31 December 2028 (longer in cases of fraud or gross negligence). A QFZP must also keep Corporate Tax records for seven years after the end of the tax period.
Paper does not make a board real. If you are unsure whether your governance holds up, start with an honest audit of how decisions actually get made, not how they are meant to get made on paper.
Assess your directed and managed position using our readiness tool, or speak to the Fractional Dubai team to explore how a qualified UAE-based fractional CFO can anchor your substance position properly.
Frequently asked questions
Do directors need to be UAE residents to satisfy the directed and managed test?
No. The Ministry of Finance's guidance was clear that directors did not have to be UAE residents. But they had to be physically present in the UAE when strategic decisions were taken at board meetings. Residency and physical presence at meetings are different requirements.
Does a video call board meeting count for directed and managed purposes?
No. The quorum requirement specified that directors must be physically present in the UAE at the time of the meeting. Directors joining by video from another country did not count towards quorum for ESR purposes.
How many board meetings per year satisfy "adequate frequency"?
The regulation does not specify a fixed number. It calibrates to the amount of decision-making required at board level. What matters more than the number is the content. Minutes must record real strategic decisions about the relevant activity, not just that the meeting occurred.
Does the directed and managed test still apply after 2022?
Not as an ESR test. Cabinet Decision 98 of 2024 ended the ESR for financial years ending after 31 December 2022. For free zone companies seeking QFZP status there is no separate board-quorum condition. But the core income-generating activities must be performed in the free zone, and where those activities are decisions, the decisions must be taken there.
Can a fractional executive satisfy the director expertise requirement?
Yes, provided the individual has genuine knowledge of and experience in the relevant activity and attends board meetings in person in the UAE as a director or equivalent. A fractional executive who is UAE-based, sector-qualified and actively participates in strategic governance can meet both the physical presence and expertise requirements of the directed and managed test.